Renovating an investment property can help attract quality tenants, improve rental income and potentially increase the property’s market value. However, not every renovation delivers a worthwhile return. The key is to understand which improvements suit your local rental market, how much they will cost and how the expenses will affect your overall investment strategy.
Before starting work, property investors should consider the expected return on investment (ROI), financing options, potential vacancy periods and the tax treatment of renovation expenses. With careful planning, you can improve your property’s appeal while managing costs and making informed decisions about available tax deductions.
1. What Should You Consider Before Renovating an Investment Property?
Before committing to a renovation, assess whether the expected financial benefits justify the expense.
Calculate the total renovation cost
Your budget should include more than materials and labour. Consider contractor fees, council approvals, permits, rubbish removal, insurance and a contingency for unexpected expenses.
Obtain several quotes for major work and establish a realistic completion date. Unexpected structural issues, plumbing problems or electrical upgrades can quickly increase costs.
Consider rental demand in your area
Research comparable rental properties to understand what tenants are willing to pay for. For example, a modern kitchen may help attract tenants in a competitive market, while additional outdoor entertaining space may be more valuable in an area where families are seeking larger homes.
Avoid spending money on premium features that are unlikely to generate higher rent or improve resale prospects.
Account for vacancy and lost rental income
Extensive renovations may require tenants to move out or delay the next tenancy. Include any lost rental income in your calculations.
A renovation costing $15,000 could be less attractive if it also means several weeks without rent. Whenever possible, schedule work between tenancies and coordinate contractors to minimise delays.
Estimate your return on investment
Compare the total renovation cost with the expected financial benefit, including additional rental income and any potential increase in property value.
For example, if a $10,000 upgrade increases annual rent by $2,000, the additional gross rental yield on the renovation cost is 20% per year before maintenance, financing costs, vacancy and tax. This is an illustrative calculation, not a guaranteed return. Actual results depend on market conditions and the property’s performance.
2. Which Investment Property Renovations Offer the Best Value?
The most suitable upgrades depend on your property’s condition, target tenants, location and budget. The following options can improve presentation and functionality without necessarily requiring a complete renovation.
Repainting the interior and exterior
Fresh paint can make an older property look cleaner, brighter and better maintained. Neutral colours can appeal to a wider range of tenants and help rooms feel more spacious.
As an indicative guide, painting one room may cost around $400 to $1,200, while painting a single-storey exterior may cost $4,000 to $10,000 or more. Actual prices depend on preparation, property size, access and labour rates. Before proceeding, check whether the work is simply repainting an existing surface or forms part of a broader renovation. That distinction can affect the tax treatment.
Kitchen upgrades
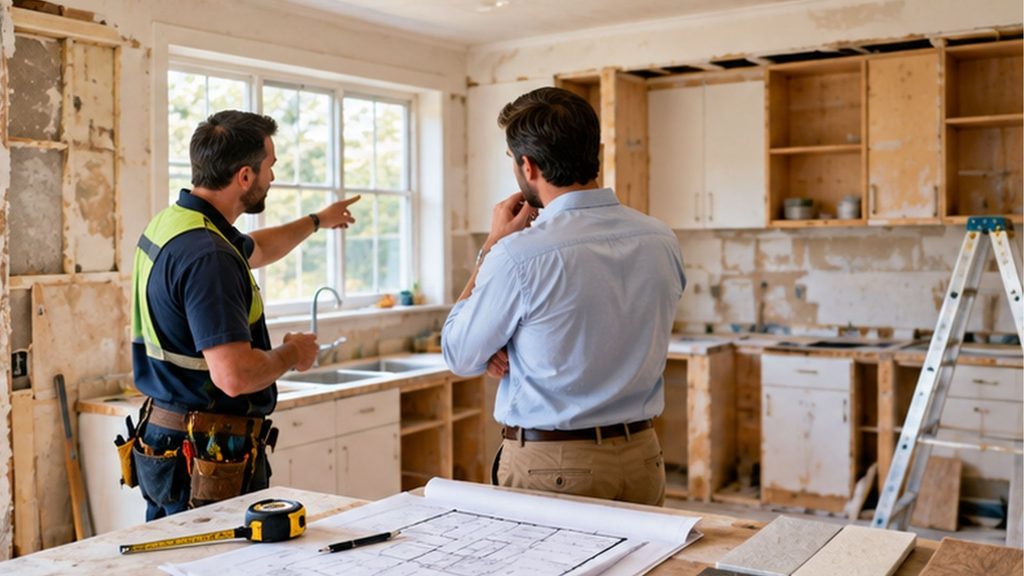
A functional kitchen can improve a property’s appeal and may support stronger rental demand. Rather than replacing everything, consider updating cabinet doors, handles, benchtops, lighting and taps. These improvements may modernise the kitchen at a lower cost than a complete replacement.
A cosmetic refresh might cost approximately $8,000 to $12,000 or more, while a full renovation could cost $20,000 to $35,000 or more.
Compare the likely benefit with the cost of materials, installation and any lost rental income before choosing a design.
Bathroom improvements
Bathrooms can influence tenant decisions, particularly where existing fittings are worn or the layout is impractical.
Replacing taps, improving ventilation, upgrading lighting and adding storage may deliver useful improvements without replacing the entire bathroom.
A more extensive renovation may cost $10,000 to $18,000 or more, depending on the scope of work, waterproofing requirements and fixtures selected.
Prioritise durability, water efficiency and easy maintenance rather than expensive finishes that may not translate into higher rent.
Flooring upgrades
Worn carpets, damaged boards and outdated flooring can make an otherwise attractive property feel neglected.
Replacing flooring with durable, easy-to-clean materials can improve presentation and reduce maintenance concerns. Indicative costs may range from $5,000 to $12,000 or more, depending on the area and materials.
Consider the property’s tenant profile when selecting flooring. For example, durable surfaces may be particularly practical for family rentals or properties with high tenant turnover.
Outdoor improvements
A tidy garden, usable patio or simple deck can improve the appeal of a property, particularly in markets where outdoor living is valued.
Basic landscaping and outdoor improvements may cost a few thousand dollars, while premium decks, outdoor kitchens and extensive landscaping can cost tens of thousands.
Keep ongoing maintenance in mind. An elaborate garden or expensive outdoor feature may add little value if local tenants prefer a low-maintenance property.
Energy-efficient upgrades
Solar panels, insulation, efficient lighting and water-saving fixtures may help reduce running costs and appeal to tenants concerned about energy expenses.
However, the financial benefit depends on the property’s characteristics, installation costs, energy usage and local demand. Some upgrades also require electrical, building or other approvals.
Obtain quotes and assess the likely savings before proceeding. Consider whether the improvements will benefit the property over the period you expect to own it.
3. How to Finance an Investment Property Renovation
The right financing option depends on the size of the project, your available equity, cash flow and existing loan arrangements.
Refinance your investment property loan
Refinancing may allow you to access available equity to fund renovations. However, lenders will generally assess your income, expenses, existing debts, property valuation and ability to service the new loan.
Compare interest rates, fees, loan features and the total borrowing cost. Increasing your loan balance may also increase repayments and financial risk.
Use available equity
Some lenders may allow eligible investors to borrow against equity in an existing property. Equity is not the same as cash readily available to spend: access depends on the lender’s valuation, lending criteria and loan-to-value ratio.
Borrowing against equity can help fund improvements, but investors should consider whether the expected rental or capital benefit justifies the additional debt.
Consider a construction or renovation loan
For substantial projects, a construction loan or a lender’s renovation finance product may be worth investigating. These products can have specific requirements around plans, quotes, approvals, progress payments and inspections. Confirm the lender’s conditions before signing building contracts.
Tips from Australian banks and finance providers
Australian lenders, including major banks and specialist mortgage providers, commonly assess renovation borrowing against the borrower’s capacity to repay and the security offered.
Before applying, consider these practical steps:
- Review your borrowing capacity: Ask your lender or mortgage broker to estimate repayments under different interest-rate scenarios.
- Obtain written quotes: A detailed scope of work and contractor quotes can help the lender assess the project.
- Check loan conditions: Confirm whether the loan permits the proposed renovation and how funds will be released.
- Compare the total cost: Look beyond the advertised rate to fees, valuation costs and any refinancing expenses.
- Keep a cash buffer: Avoid committing all available funds to the renovation. Retain reserves for unexpected work, vacancies and interest repayments.
A lender may not approve the full amount requested, even if the property has increased in value. Seek approval before relying on borrowed funds to complete the project.
4. Understand the Tax Deductions Available for Renovations
One of the most important considerations when renovating an investment property is understanding which expenses you can claim as tax deductions and when those deductions are available.
Not all renovation expenses are immediately tax-deductible. The Australian Taxation Office (ATO) distinguishes between repairs, maintenance, capital improvements and depreciating assets.
| Type of expense | Potential tax treatment |
| Repairs to damage arising during the rental period | May be immediately deductible |
| Routine maintenance, such as servicing existing equipment | May be immediately deductible |
| Initial repairs for damage that existed when you purchased the property | Generally capital expenditure, not immediately deductible |
| Structural renovations and improvements | May qualify for capital works deductions over time |
| New appliances, carpets and other depreciating assets | May qualify for depreciation deductions over time |
The correct treatment depends on the nature of the work, when the expense was incurred and the property’s use.
Repairs and maintenance versus capital improvements
For example, repairing a leaking pipe after a tenant reports a problem may qualify as an immediate deduction. However, completely renovating a bathroom or installing a new kitchen generally involves capital expenditure rather than an immediately deductible repair.
If you purchase a property knowing it needs repairs before it can be rented, those initial
A single renovation project can include both deductible repairs and capital improvements. Request itemised invoices from contractors so each component can be assessed separately.
Keep records to support your claims
To help identify eligible deductions, retain:
- Itemised invoices and receipts.
- Contractor quotes and descriptions of completed work.
- Records showing when the property was available for rent.
- Details of repairs, replacements and improvements.
- Purchase documents and records of existing defects.
- Relevant depreciation schedules and asset information.
A quantity surveyor may also help identify eligible depreciation deductions for capital works and depreciating assets.
5. How Camden Professionals Can Help You Claim Renovation Tax Deductions
Camden Professionals can help property investors review renovation expenses and determine which costs may qualify for immediate deductions, capital works deductions or depreciation over time. Our accounting team can assess invoices, distinguish repairs from capital improvements, review eligible depreciation claims and help ensure your rental property tax return reflects the deductions available under ATO rules.
Whether you are refreshing a kitchen, upgrading a bathroom or undertaking a major renovation, contact Camden Professionals before or during the project to discuss your tax position, maintain appropriate records and avoid missing legitimate deductions.
Frequently Asked Questions
Can I claim investment property renovations as a tax deduction?
Some expenses may be immediately deductible, while capital improvements and depreciating assets are generally claimed over time where eligible. The treatment depends on the work performed.
Is repainting an investment property tax-deductible?
Repainting may qualify as a repair or maintenance expense if it restores existing surfaces. Painting undertaken as part of a broader capital improvement may receive different treatment.
Can I claim renovations completed before finding a tenant?
Initial repairs to defects that existed when you acquired the property are generally capital expenses, not immediately deductible. Other costs may qualify for capital works deductions or depreciation, depending on their nature.
Can I claim interest on a loan used to fund renovations?
Interest may be deductible to the extent the borrowed funds are used for income-producing purposes. The purpose and use of the borrowed money matter, so keep clear records and seek tax advice.
Should I obtain a depreciation schedule after renovating?
A depreciation schedule may help identify eligible deductions for capital works and depreciating assets. A qualified quantity surveyor can assess the property and relevant expenditure.
Australian References and Finance Resources
- ATO: Rental property repairs, maintenance and capital expenditure — guidance on the tax treatment of renovation expenses.
- ANZ: Using equity in your property — considerations when accessing equity to fund renovations.
- NAB: Renovation lending options — equity, redraw and construction finance considerations.
- CommBank: Ways to finance a renovation — budgeting and financing options.
Note: Renovation costs in this article are indicative only. Obtain current quotes and confirm your individual tax treatment with your accountant before claiming deductions.
General Information Warning
The material on this page and on this website has been prepared for general information purposes only and is not intended to provide tax advice for any person’s specific circumstances. Tax outcomes depend on the individual facts and the law applying at the relevant time.
Before acting on the information in this article, you should obtain professional advice that takes into account your circumstances and the details of the proposed transaction or property project.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Note: This article provides general information, not legal, insolvency or personalised tax advice. Business owners should obtain advice appropriate to their circumstances before entering into a sale agreement.
Recent Comments