Christmas is an opportunity for business owners to thank their employees for their hard work throughout the year. Whether you’re planning a Christmas party, organising a team lunch or giving staff gifts, these celebrations can help recognise your team’s contribution and finish the year on a positive note.
However, before booking a venue or ordering presents, it’s worth considering the tax implications.
Fringe Benefits Tax (FBT), income tax deductions and GST credits can all affect how Christmas parties and staff gifts are treated.
The tax outcome depends on factors such as the cost per person, the type of benefit provided, where the event takes place and who attends. Planning ahead can help your business manage its tax obligations while still giving your team something to celebrate.
1. Do Christmas Parties Attract Fringe Benefits Tax?
FBT is a tax employers may pay on certain benefits provided to employees, or their associates, in addition to their salary or wages.
A Christmas party can be considered an entertainment-related fringe benefit, but FBT does not automatically apply to every celebration. The treatment depends on the circumstances, including the cost of the event, the attendees and the method used to calculate FBT. For example, a modest Christmas lunch held at your business premises during a working day may receive different treatment from an expensive evening function at an external venue.
The Australian Taxation Office (ATO) provides guidance on work-related entertainment and the FBT rules that may apply. Before committing to a venue or activity, consider the expected cost per attendee and whether an FBT exemption or concession may be available.
2. The $300 Minor Benefits Exemption
One important consideration is the minor benefits exemption.
Broadly, a benefit may be exempt from FBT where its value is less than $300, including GST, and it would be unreasonable to treat it as a fringe benefit, considering factors such as how frequently similar benefits are provided and the circumstances in which they are given. The exemption is not an automatic allowance for every expense below $300. The relevant conditions must be assessed for each benefit.
For example, a relatively inexpensive staff gift or an occasional Christmas celebration may qualify, depending on the circumstances. However, multiple benefits, recurring entertainment and the nature of the expenditure can affect the outcome.
Businesses should also distinguish between the minor benefits exemption and other FBT concessions, as different conditions apply.
3. Does It Matter Where the Christmas Party Is Held?
Yes. The location and circumstances of the event can influence its FBT treatment.
Christmas parties held on business premises
A Christmas party held on a working day at the employer’s business premises may qualify for an exemption for employees, subject to the relevant conditions. However, the treatment of partners and other employee associates may differ. The business should also consider whether the expenditure relates to entertainment and how any associated tax deduction or GST credit is affected.
Christmas parties held at an external venue
A function held at a restaurant, hotel or other external venue may be subject to different rules. The minor benefits exemption may apply where the relevant conditions are satisfied. Alternatively, the employer may need to calculate FBT under an applicable method.
The cost per attendee, the type of benefit and the people attending should all be considered before deciding how the expense will be treated.
There is no single FBT rule that applies to every Christmas party, so businesses should assess their own arrangements rather than relying on what another employer does.
4. Are Christmas Gifts to Employees Subject to FBT?
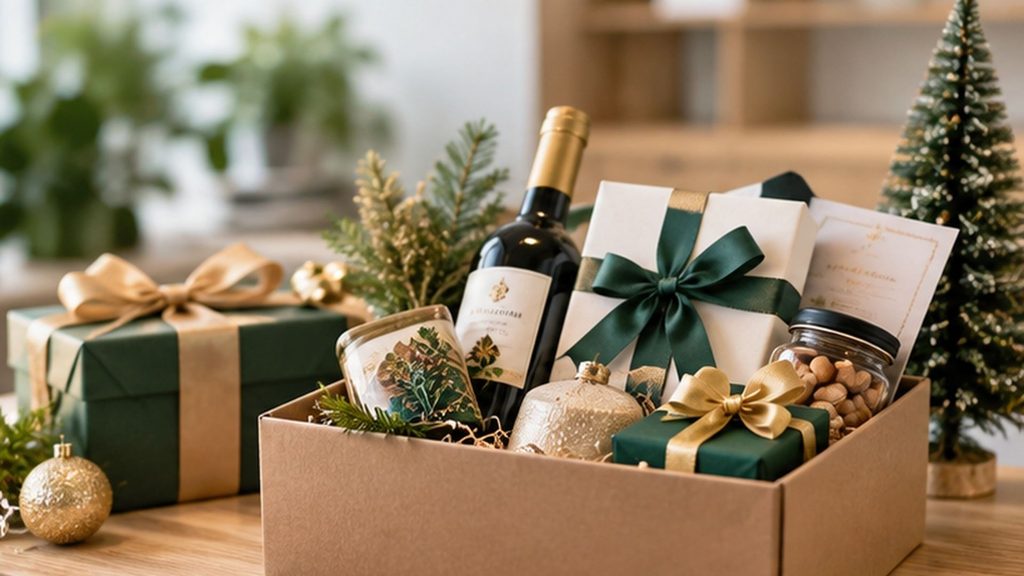
Staff gifts are another common year-end expense. Businesses may give employees hampers, wine, chocolates, gift cards, flowers or other presents to thank them for their contribution.The tax treatment depends on the nature and value of the gift.
Non-entertainment gifts
Non-entertainment gifts may include hampers, flowers, eligible gift vouchers and other tangible presents that do not constitute entertainment.
Where a gift is provided infrequently and costs less than $300, it may qualify for the minor benefits exemption, subject to the relevant conditions.
If the gift is subject to FBT, the employer may be able to claim an income tax deduction and GST credit, where the usual requirements are met.
Entertainment gifts
Entertainment gifts may include tickets to sporting events, concerts, theatre performances or similar experiences.
These benefits can have different tax consequences from ordinary gifts. Even where a benefit costs less than $300, the exemption and any related deduction or GST credit must be considered carefully.
Tip: If you’re buying gifts for your team, keep a record of what was purchased, its value, who received it and whether the gift was entertainment related. This makes it easier to assess the correct tax treatment.
5. What About Gift Cards and Vouchers?
Gift cards and vouchers are popular because employees can choose something they genuinely want.
For tax purposes, however, the treatment depends on how the card or voucher can be used and the circumstances in which it is provided.
A gift card that can be exchanged for ordinary retail goods may be treated differently from a voucher for a restaurant meal, concert or other entertainment experience.
Businesses should not assume that all gift cards receive the same treatment. Consider the value of each benefit, whether the minor benefits exemption applies and whether any other FBT rules are relevant.
6. What If Clients Attend the Christmas Party?
Some businesses use Christmas events to thank clients, suppliers and other business contacts.
However, employee entertainment and client entertainment can have different tax consequences. Client entertainment is generally not subject to FBT because clients are not employees or their associates. However, the expenditure may be non-deductible for income tax purposes, and GST credits may be restricted.
Where employees and clients attend the same function, it is important to retain enough information to identify the attendees and assess the different tax treatments.
Keeping a guest list and recording the purpose of the event can help your accountant determine the appropriate treatment.
7. Can Your Business Claim Tax Deductions and GST Credits?
FBT is only one part of the tax considerations associated with Christmas parties and gifts.
An expense that is exempt from FBT does not automatically qualify for an income tax deduction or GST credit.
For example, entertainment expenses may be non-deductible for income tax purposes and may not qualify for GST credits, even where no FBT is payable.
Conversely, where FBT applies to a benefit, the employer may generally be entitled to a deduction and GST credit if the relevant requirements are satisfied. The correct treatment depends on the nature of the expense, the FBT rules, the business’s GST registration and the applicable income tax provisions.
Reviewing all three areas together can help prevent errors in your business accounts and tax reporting.
8. Keep Accurate Records of Christmas Spending
December is often a busy period for business owners. Between staff parties, client functions, gifts, payroll and office closures, it can be easy to overlook receipts or lose track of spending.
Good record keeping makes it easier to determine the correct tax treatment and prepare any required FBT calculations.
Keep records of:
- Receipts and invoices for parties, meals and gifts.
- The total cost and cost per attendee.
- Names or categories of attendees, including employees, partners and clients.
- The date, location and purpose of each event.
- Details of gifts provided, including their value and nature.
- Any FBT exemption, concession or calculation method relied upon.
Organising these records before the Christmas break can reduce the administrative burden when your accountant reviews the expenses later.
9. Plan Your Christmas Budget Before Spending
The easiest time to address FBT questions is before you commit to an expense.
If you are organising a large function, buying gifts for employees or inviting clients to an event, ask your accountant to review the proposed arrangements.
This can help you compare options, understand potential tax costs and decide how to structure the event within your business budget.
It is also worth considering other year-end obligations, including payroll processing, employee leave, supplier payments and cash flow during the holiday period.
A little preparation can make your Christmas celebrations easier to manage and help avoid unexpected tax liabilities after the festivities.
How Camden Professionals Can Help
Camden Professionals can help business owners understand the FBT implications of Christmas parties, staff gifts and client entertainment. Our accounting team can review your planned expenses, assess potential exemptions, clarify income tax deduction and GST credit rules, and help maintain the records needed for accurate reporting.
We can also assist with broader year-end tax planning, payroll and business accounting so you can finish the financial year with greater confidence.
Contact Camden Professionals before your Christmas celebrations to discuss your arrangements and understand the potential tax implications for your business.
Frequently Asked Questions
1. Are Christmas parties always subject to FBT?
No. Some events may qualify for an exemption or concession, depending on their cost, location, attendees and other circumstances.
2. Can I give employees gifts worth less than $300 without paying FBT?
Potentially. The minor benefits exemption generally requires a benefit to be worth less than $300 and for it to be unreasonable to treat it as a fringe benefit. Other relevant circumstances must also be considered.
3. Are gift cards subject to FBT?
They can be. The treatment depends on the type of voucher, its value, how it can be used and whether an exemption applies.
4. Can I claim a tax deduction for the Christmas party?
Not necessarily. Entertainment expenses are often non-deductible unless a relevant exception applies. If FBT is payable, a deduction may generally be available, subject to the usual rules.
5. Do I need to keep receipts and attendee records?
Yes. Keeping invoices, attendee details, costs and information about the benefits provided helps your accountant assess FBT, deductions and GST credits accurately.
6. When should I speak to my accountant?
Ideally, before booking the event or purchasing gifts. Early advice can help you understand the tax implications and budget accordingly.
General Information Warning
The material on this page and on this website has been prepared for general information purposes only and is not intended to provide tax advice for any person’s specific circumstances. Tax outcomes depend on the individual facts and the law applying at the relevant time.
Before acting on the information in this article, you should obtain professional advice that takes into account your circumstances and the details of the proposed transaction or property project.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Note: This article provides general information, not legal, insolvency or personalised tax advice. Business owners should obtain advice appropriate to their circumstances before entering into a sale agreement.
Recent Comments