




Downsizer Contributions: How Selling Your Home Could Boost Your Superannuation
For many Australians approaching retirement, selling the family home can be about more than finding a smaller or more manageable property. It can also create an opportunity to strengthen retirement savings through a downsizer contribution to superannuation.
The Australian Government’s downsizer rules allow eligible homeowners to contribute some of the proceeds from selling their home directly into superannuation. For eligible individuals, the contribution can be up to $300,000, while an eligible couple may potentially contribute up to $600,000 between them, subject to each person’s eligibility and the applicable rules.
- The eligible age for a downsizer contribution is currently 55 years or older.
- Since 1 January 2023, you must be at least 55 years old when making the contribution.
- There is no maximum age limit for a downsizer contribution, provided you meet the other eligibility requirements.
However, downsizing does not automatically mean there will be hundreds of thousands of dollars available to put into super. Property prices, selling costs and the cost of the replacement home all need to be considered.Understanding the rules before selling is important because there are specific eligibility requirements, contribution deadlines and conditions that need to be satisfied.
Why Downsizing Doesn’t Always Mean Having More Cash
The term “downsizing” can sometimes create the impression that selling a large family home will automatically release a substantial amount of money.
That is not necessarily the case.
Many Australians sell their existing home and purchase another property in a desirable location. They may choose a newer apartment, a low-maintenance townhouse or a property closer to family, the coast, healthcare services or a major city.
In some areas, the replacement property can cost almost as much as the home being sold. There are also selling costs, legal fees, moving expenses, stamp duty where applicable and other transaction costs to consider. This means the amount available for a downsizer contribution will depend on the individual’s circumstances and the actual proceeds available from the sale. For those who do have surplus funds, however, the downsizer rules can provide an opportunity to move a significant amount into the superannuation system.
Downsizer Contribution Eligibility: What Are the Rules?
The ATO sets out a few conditions that must be met before a contribution can qualify as a downsizer contribution.
Generally, you must:
- Be 55 years of age or older when making the contribution.
- Have owned the property for at least 10 years before the sale, generally measured from the date of acquisition to the date of disposal.
- Have owned the property as an individual or jointly with your spouse.
- You or your spouse must have held an ownership interest in the property, and the relevant 10-year ownership requirement must be satisfied.
- Make the contribution from the proceeds of selling an eligible Australian residential property.
- Satisfy the relevant main residence requirements.
- Make the contribution within the required timeframe.
- Have not previously made a downsizer contribution from the sale of another dwelling.
The ATO states that the contract for sale must generally have been entered into on or after 1 July 2018. The contribution must generally be made within 90 days of the change of ownership, unless the Commissioner grants an extension. It is therefore important not to treat the downsizer contribution as an informal arrangement that can be organised whenever convenient after settlement.
The 90-Day Downsizer Contribution Deadline
One of the most important practical considerations is timing. Eligible downsizer contributions generally need to be made within 90 days from the change of ownership of the property. The ATO can grant an extension in certain circumstances.
This means homeowners planning to use the downsizer rules should consider their superannuation arrangements before the property settles. Waiting until after settlement to investigate the rules could create unnecessary pressure, particularly if there are questions about eligibility or the amount that can be contributed. The timing should also be considered alongside the settlement of the replacement property, because selling the existing home and buying another property can involve significant cash-flow requirements.
How Much Can You Contribute?
An eligible individual can generally make a downsizer contribution of up to $300,000 from the proceeds of selling an eligible home. The ATO states that the maximum amount an individual can contribute from the sale of one home is the lesser of:
- $300,000, or
- the sale proceeds remaining after taking into account other downsizer contributions made by the individual or their spouse.
Importantly, multiple downsizer contributions can potentially be made from the sale of the same home, provided the total does not exceed the applicable maximum. For example, an eligible homeowner might contribute $150,000 shortly after settlement and another $150,000 later, provided the relevant conditions are met. A couple may also be able to contribute up to $300,000 each if both individuals meet the requirements.
Does a Downsizer Contribution Count Towards Your Normal Super Contribution Caps?
A qualifying downsizer contribution does not count towards your concessional or non-concessional contribution caps. This can make the downsizer rules particularly useful for people who may otherwise have limited opportunities to contribute a significant amount into super. However, once contributed, the money becomes part of your superannuation balance and the normal superannuation rules will apply. The contribution should therefore be considered as part of your broader retirement and superannuation strategy rather than in isolation.
Can Downsizer Contributions Help Build Retirement Wealth?
For homeowners who have substantial equity in their property, downsizer contributions can provide another way to structure retirement savings. Money held in the family home can provide security and reduce housing costs, but it does not generally produce investment income in the same way as assets held within superannuation.
Moving some surplus capital into super may allow the money to form part of a broader retirement investment strategy. However, contributing money to super also means the funds become subject to the superannuation rules.
The decision should therefore be considered as part of an overall retirement plan rather than simply as a tax strategy. The appropriate approach will depend on factors such as:
- Age
- Existing superannuation balances
- Pension arrangements
- Investment objectives
- Cash-flow requirements
- Estate planning
What Does This Have to Do with SMSFs?
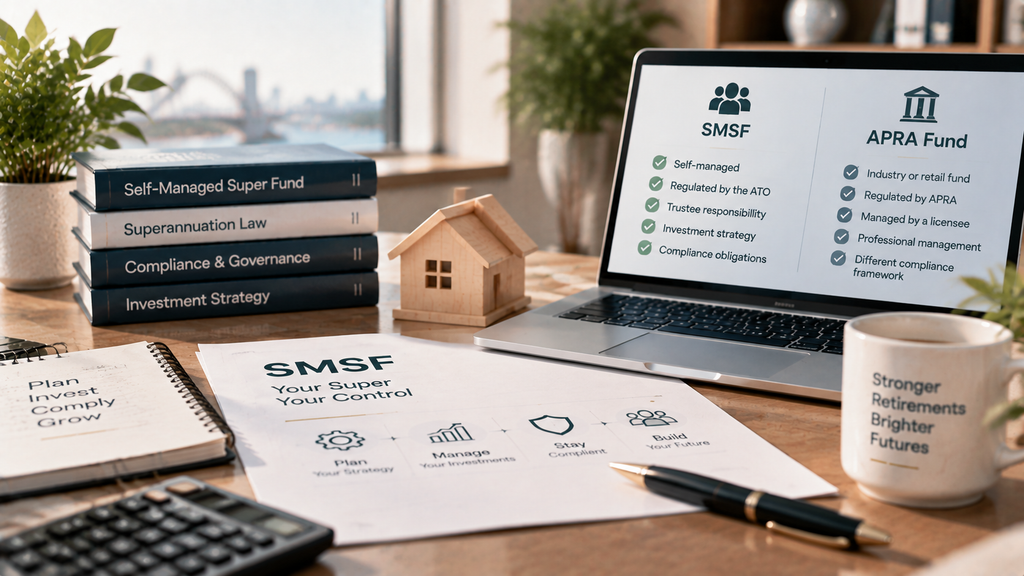
Downsizer contributions can also be relevant to people who have a Self-Managed Super Fund (SMSF). An SMSF is a superannuation fund that members manage themselves. SMSFs are regulated by the Australian Taxation Office, rather than APRA. APRA’s own licensing guidance confirms that SMSFs are not RSEs and are instead regulated by the ATO.
This distinction is important. An SMSF trustee remains responsible for ensuring that contributions are correctly accepted and recorded and that the fund complies with superannuation legislation. The supplied material also highlights that SMSF trustees remain responsible for the fund’s investment strategy and compliance even where professional investment managers or other advisers are engaged.
SMSFs vs APRA-Regulated Super Funds
Most Australians have their superannuation with an APRA-regulated fund, such as an industry or retail super fund. APRA oversees registrable superannuation entities and their licensed trustees. APRA’s prudential framework includes requirements covering areas such as:
- Governance
- Investment governance
- Risk management
- Insurance
- Member outcomes
For example, APRA’s SPS 530 Investment Governance requires RSE licensees to maintain an investment governance framework, establish investment objectives and strategies, conduct due diligence and undertake stress testing. APRA’s SPS 510 Governance also establishes minimum governance requirements for RSE licensees and places ultimate responsibility for sound and prudent management with the board. These APRA requirements apply to APRA-regulated superannuation entities and should not be confused with the regulatory framework governing SMSFs.
Most industry and retail super funds are regulated by APRA, while SMSFs are regulated by the ATO. The key practical difference is that SMSF trustees take direct responsibility for the fund’s compliance, investment strategy and administration. For SMSF members, the ATO is the key regulator.
What Are the Risks of an SMSF?
Having greater control over superannuation can also mean greater responsibility. SMSF trustees are responsible for making sure the fund’s investment strategy is appropriate, keeping records, meeting reporting obligations and complying with the superannuation laws. SMSFs do not have the same protections available to members of APRA-regulated funds.
There are also ongoing costs, including:
- Accounting
- Administration
- Auditing
- Regulatory levies
- Investment advice
- Potentially legal and insurance expenses
This means an SMSF should not be established simply because a downsizer contribution is available. The decision to use an SMSF should be considered separately from the decision about whether a downsizer contribution is appropriate.
Can You Use a Downsizer Contribution More Than Once?
Generally, no. The downsizer rules contain a once-only requirement. The ATO states that an individual must not have previously made a downsizer contribution from the sale of any dwelling. This can include multiple partial disposals of an ownership interest in the same dwelling.
This makes it particularly important to understand the rules before making the contribution. A decision to make a downsizer contribution can have long-term consequences because the opportunity generally cannot simply be repeated when another property is sold in the future.
What About the Capital Gains Tax Rules?
The property must generally satisfy the relevant main residence requirements for the downsizer rules. The ATO’s eligibility guidance refers to both an ownership test and a main residence test. This is an important area where professional advice can be useful, particularly where a property has been:
- Used partly as an investment property
- Rented out for periods
- Inherited
- Jointly owned
- Subject to other ownership arrangements
Not every residential property transaction will automatically qualify.
Downsizer Contributions and Capital Gains Tax (CGT)
Selling a property may also create Capital Gains Tax considerations.The tax outcome will depend on the individual’s circumstances, including:
- How the property was used
- Whether it was used to produce income
- Ownership history
- The period the property was held
- Whether any exemptions or concessions apply
The downsizer contribution rules and Capital Gains Tax rules are separate considerations.Meeting the downsizer contribution requirements does not automatically mean there are no CGT implications. Understanding both areas before selling can help avoid unexpected tax outcomes.
Is Downsizing the Right Strategy for You?
Downsizing can be an effective retirement planning strategy for some Australians, but it is not suitable for everyone.The decision involves more than just the opportunity to contribute money into superannuation.Factors to consider may include:
- Future housing needs
- Lifestyle preferences
- Access to funds
- Retirement income requirements
- Superannuation position
- Tax implications
- Estate planning objectives
For some people, remaining in their current home may continue to be the preferred option. For others, selling the family home and contributing surplus funds into superannuation may better align with their retirement goals.
What Should You Consider Before Making a Downsizer Contribution?
Before selling your home, consider:
Your Eligibility
Make sure all downsizer contribution requirements are satisfied before proceeding.
Your Financial Position
Review:
- The expected sale proceeds
- Replacement property costs
- Selling expenses
- Available cash reserves
Your Superannuation Strategy
Consider how the contribution fits with:
- Your existing super balance
- Retirement income plans
- Investment strategy
Your Estate Planning
A significant contribution into superannuation may affect how your assets are structured and passed on in the future.
How Professional Advice Can Help
Downsizer contributions involve several rules and requirements that need careful consideration. Professional advice can help you understand:
- Whether you qualify
- How much you may be able to contribute
- How the contribution fits into your retirement strategy
- Potential tax considerations
- The impact on your broader financial position
Planning before selling your home can help ensure the decision supports your long-term retirement objectives.
Final Thoughts
Downsizer contributions provide eligible Australians with an opportunity to move some proceeds from the sale of their home into superannuation. For some homeowners, this can help strengthen retirement savings and provide greater flexibility. However, selling a home is a significant financial decision and should be considered carefully. The downsizer rules should be reviewed alongside:
- Retirement plans
- Superannuation strategy
- Tax considerations
- Investment objectives
- Estate planning arrangements
Understanding the requirements before selling can help ensure decisions are made with a clear understanding of the potential outcomes.
Frequently Asked Questions
What is a downsizer contribution?
A downsizer contribution allows eligible Australians to contribute some proceeds from selling their home into their superannuation fund.
How much can I contribute through downsizer rules?
Eligible individuals may be able to contribute up to $300,000 from the sale of an eligible home.
Can couples both make downsizer contributions?
Yes. If both individuals meet the eligibility requirements, each person may be able to contribute up to $300,000.
What age do I need to be to make a downsizer contribution?
You must generally be at least 55 years old when making the contribution and meet the other eligibility requirements.
Does a downsizer contribution count towards normal contribution caps?
No. A qualifying downsizer contribution does not count towards concessional or non-concessional contribution caps.
Can I make a downsizer contribution more than once?
Generally, no. The downsizer rules include a once-only requirement.
Can I make a downsizer contribution into an SMSF?
Yes, provided the SMSF accepts the contribution and all eligibility requirements are satisfied.
How Can We Help?
If you are considering selling your home and want to understand how downsizer contributions may apply to your retirement strategy, Camden Professionals can help review your options.
Our team can assist with:
- Retirement planning considerations
- Superannuation strategies
- Tax implications
- Wealth planning
- Financial structuring considerations
Contact Camden Professionals to discuss your circumstances.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Should You Make a Downsizer Contribution to Superannuation?
If you’re planning to sell your home later in life, you may have a valuable opportunity to supercharge your retirement savings — even if you’re already retired or have a high super balance.
Since 1 January 2023, Australians aged 55 or older can contribute up to $300,000 each (per person) into superannuation from the proceeds of selling their primary residence, without impacting their usual contribution caps. Known as a downsizer contribution, this strategy is designed to help older Australians boost their super balances as they transition to retirement — but it comes with specific rules, and it may not be suitable for everyone.
Here’s what you need to know to decide if this opportunity is right for you.
Key Eligibility Rules
To qualify for the downsizer contribution:
- You must be 55 years or older at the time of contributing.
- The home must have been owned for 10 years or more, by you or your spouse.
- The home must have been your main residence at some point.
- The contribution must be made within 90 days of settlement.
- You must submit the ATO “Downsizer contribution into super” form before or when the contribution is made.
- You can’t claim a tax deduction for the contribution.
- You must not have made a downsizer contribution previously.
Importantly, the $300,000 limit applies per person — so a couple could contribute up to $600,000 combined, provided the total sale proceeds allow for it.
Reference: ATO – Downsizer contributions
Pros of Making a Downsizer Contribution
- Super is a Tax-Effective Investment Structure
Downsizer contributions go into your tax-free component of super. Earnings on these contributions in retirement phase are generally tax-free, and the balance may not be taxed upon death when passed to non-dependent beneficiaries.
- You Can Contribute Regardless of Super Balance or Work Status
Even if your super balance is over $2 million, or you’ve already retired, you can still make a downsizer contribution — unlike many other types of contributions that are limited by these factors.
- Helps Reduce Future Death Tax
Because downsizer contributions increase your tax-free component, they can help reduce or eliminate the 15% tax that may otherwise apply if your super is passed to non-dependents (like adult children) after your death.
- Property Doesn’t Need to Be Fully CGT-Exempt
Downsizer contributions are allowed even if:
- The home was partly rented
- The land is over 2 hectares
- The home was rebuilt or built on previously purchased land
- You only owned a share of the property (e.g. as a tenant in common)
- Flexibility to Use Assets
You can contribute assets you already own (e.g. shares, other investments) into your super to fund the downsizer contribution, provided they match the cash value of your sale — particularly useful if the cash from your home sale is needed to purchase a new residence.
Considerations and Drawbacks
No Immediate Tax Deduction
Downsizer contributions are non-concessional and not deductible, so if you have a high taxable income, you may want to explore making a concessional (deductible) contribution instead — especially if you have carry-forward concessional cap room.
You Can Only Use It Once
The downsizer opportunity is a one-time-only benefit, so if you might benefit more from using your standard non-concessional cap or future concessional caps, timing is important.
Access to Super May Be Limited
If you’re under age 65 and still working, you may not yet meet a condition of release. This means the money will be locked in super until you retire or satisfy another release condition — which could be an issue if you need those funds to buy your next home.
Centrelink Impacts
While your principal home is exempt from Centrelink’s assets test, once the sale proceeds are moved into super (and you’re over pension age), the balance may be deemed and assessed under both the income and assets test — potentially reducing your Age Pension or eligibility for the Commonwealth Seniors Health Card.
What Will You Live In Next?
Selling your home to make a contribution sounds appealing, but be sure to consider the cost of your next residence. Will there be enough money left to fund your downsizer strategy?
Summary of Downsizer Contribution Rules
| Requirement | Details |
| Minimum Age | 55 years (from 1 Jan 2023) |
| Contribution Limit | $300,000 per person |
| Ownership Period | 10+ years (you/spouse), includes land |
| Residency Requirement | Must have lived in the property at some point |
| Timing of Contribution | Within 90 days of property settlement |
| Form Required | ATO Downsizer contribution into super form |
| Can you deduct the contribution? | No |
| Can it be used more than once? | No |
Conclusion: Is the Downsizer Strategy Right for You?
The downsizer contribution scheme is one of the most generous superannuation concessions available to older Australians — offering a rare opportunity to boost your super balance, even after retirement or when your super is already above standard contribution limits.
But just because you can make a downsizer contribution doesn’t mean you should. Consider your:
- Access to super
- Taxable income
- Centrelink entitlements
- Next housing needs
- Estate planning goals
Because superannuation rules can be complex — and the decision can have lasting tax, income and social security implications — it’s wise to speak with your financial adviser or tax professional before making a move.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Unlocking Value by Subdividing Your Land
Many retirees find themselves in a familiar predicament: they are cash-poor but asset-rich. For those living on larger properties, one potential strategy to unlock financial resources is subdividing and selling unused land. This approach can provide much-needed funds for income-producing assets, but it’s essential to understand the implications, particularly regarding capital gains tax (CGT) and downsizer contribution limitations.
The Subdivision Strategy
Subdividing a block of land involves creating separate titles for newly created blocks, which are then treated as distinct assets for tax purposes. This can be an effective way to release equity tied up in your property. For example, if you have a large family home with additional land, you might consider subdividing off a portion of that land, selling it, and using the proceeds to supplement your retirement income or invest in other opportunities.
However, it’s crucial to recognize that selling a subdivided block triggers CGT. Typically, selling your main residence is exempt from CGT, provided it hasn’t been used for income-producing purposes. Yet, this exemption becomes complex when dealing with subdivided blocks.
Capital Gains Tax Considerations
The main residence CGT exemption applies to your dwelling and up to two hectares of adjacent land used primarily for private or domestic purposes. This includes the land beneath your home. However, if you subdivide and sell a block of land that is now on a new title, it no longer qualifies as part of your dwelling. As a result, that portion is subject to CGT.
This means that if you sell a subdivided block, any capital gain made on that sale will be taxable, which could significantly reduce the financial benefit you hoped to gain from the subdivision. Understanding the potential tax liabilities is crucial to evaluating whether this strategy is financially viable for your situation.
Downsizer Contributions
Another financial consideration is the ability to make downsizer contributions to your superannuation. Under current regulations, you can contribute the proceeds from the sale of your home to your super fund as a downsizer contribution, provided certain conditions are met. The contribution must equal part or all of the sale proceeds from a dwelling that qualifies for the downsizer scheme.
However, if you have subdivided and sold a portion of your land, only the sale of your main residence qualifies for this contribution. This distinction means that the funds from selling a subdivided block may not be eligible for downsizer contributions, limiting your options for boosting your retirement savings.
Seeking Expert Advice
Before proceeding with any subdivision plans, seeking expert advice is paramount. A qualified financial advisor or tax professional can help you navigate the complexities of CGT implications and ensure compliance with current regulations. They can also assist in developing a strategic plan that aligns with your retirement goals.
Moreover, it’s essential to consider local zoning laws and regulations, as these can significantly affect the feasibility of subdividing your property. Engaging with a land surveyor or town planner can provide valuable insights into what is possible within your specific circumstances.
Conclusion
Subdividing your family home’s land can be an effective way to unlock value and generate funds for retirement. However, it is not without its challenges and tax implications. By understanding the potential CGT liabilities and the limitations on downsizer contributions, you can make informed decisions that better align with your financial objectives. Proper planning and expert guidance are key to ensuring that this strategy supports your overall retirement strategy effectively.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.