Renovating, rebuilding, adding a granny flat or subdividing your property can be exciting, but it can also create unexpected tax consequences.
For many homeowners, the starting point is simple: What will happen to the property when the project is finished?
Will it remain your family home, become an investment, be subdivided or will one of the new properties be sold?
The answer can affect your capital gains tax (CGT) position, particularly with the proposed changes applying from 1 July 2027.
The important thing is not to make a property decision based on tax alone. Instead, understand the potential tax consequences before you demolish, subdivide or start construction.
Why 1 July 2027 Could Matter
The proposed 2026 CGT reforms create an important transition point from 1 July 2027.
For properties qualifying for the main residence exemption, their value around 30 June 2027 may be relevant to future CGT calculations.
If you plan to demolish, subdivide or redevelop, documenting the property’s condition and value before work begins may be important.
However, starting a project after 1 July 2027 does not automatically mean a better tax outcome, as this depends on the property’s circumstances and future use.
Start by Defining Your Property Project
Before worrying about CGT, consider what you are trying to achieve.
The proposed 2026 CGT reforms create an important transition point from 1 July 2027.
The way gains arising before and after that date are treated may become relevant where a property is only partly exempt from CGT or is later subdivided, developed or used to produce income.
If you plan to demolish, subdivide or redevelop, keeping good records of the property’s condition, use and relevant values around key dates may be important.
Whether a formal valuation is required will depend on the circumstances and the final form of the legislation.
Starting a project after 1 July 2027 does not automatically mean a better tax outcome.
Common Property Projects
- Extending your existing home?
- Building a granny flat for family members?
- Subdividing your backyard?
- Building a duplex?
- Keeping one property and selling another?
- Developing the property with the intention of selling?
These projects can have very different tax outcomes.
The purpose of the project, your intentions and what happens to the property afterwards can all affect whether the main residence exemption, CGT rules, income tax or GST apply.
Knock-Down Rebuild: Replacing Your Family Home
A knock-down rebuild can be straightforward from a tax perspective if you replace your existing family home with a new home that you move into as your main residence.
Under the current rules, the main residence exemption can generally continue while the new home is being built, for up to four years, if the relevant conditions are met.
To access this rule, specific conditions must be satisfied, including generally moving into the new dwelling as soon as practicable after construction and continuing to use it as your main residence for at least three months.
For example, if you demolish your old Perth home, rent somewhere temporarily and build a new family home on the same land, the property may continue to qualify for the main residence exemption during construction.
However, the outcome can change if:
- Construction takes longer than permitted
- You do not move into the new property as required
- Part of the property is rented
- Part of the land is sold
- You have another property that you treat as your main residence
Before demolishing the existing home, it is worth checking how the rules apply to your circumstances.
Renovations, Extensions and Granny Flats
A renovation or extension will generally not create a CGT problem simply because you have spent money improving your home.
If the entire property continues to be your main residence, the main residence exemption will generally remain important.
The position can become more complicated when part of the property is used to generate income.
For example, you might build a granny flat and later rent it out, use part of the home as a business premises or convert a separate area into a long-term rental.
In these situations, keep records showing:
- When the income-producing use started
- The area being used
- Building and renovation costs
- Rental agreements
- Plans and drawings
- Relevant property valuations
Tip: Keep your renovation invoices even if you do not expect to sell the property soon.
Good records can become valuable if the property’s use changes in the future.
Subdividing Your Property
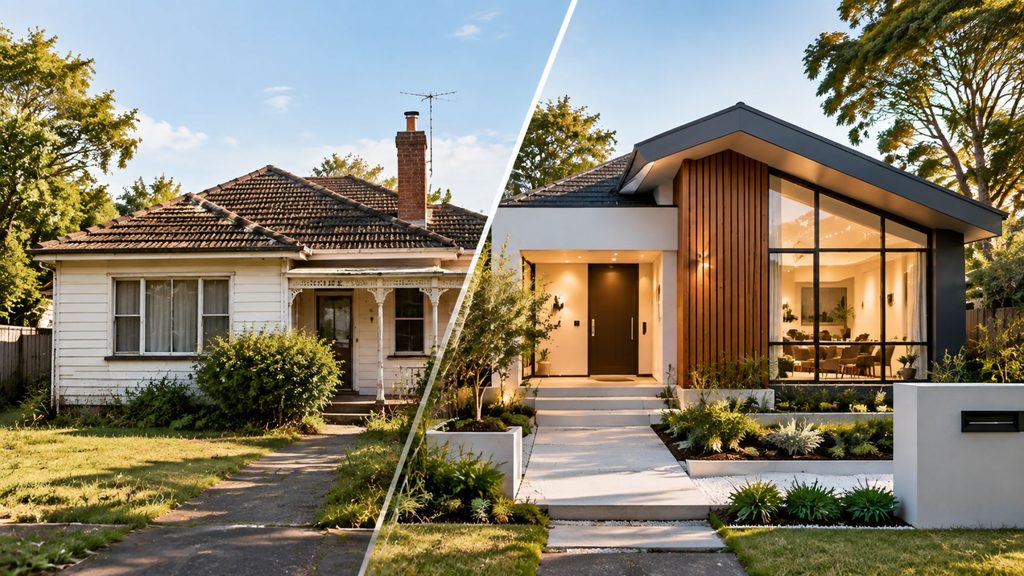
Subdividing your block and selling part of it can create a good opportunity, but it may also have tax consequences.
For example, if you subdivide your backyard and sell the new vacant block separately from your home, the main residence exemption generally does not apply to the sale of that vacant block.
The tax treatment will depend on factors such as the size and use of the land, your intentions and whether the sale is treated as a capital transaction or a profit-making activity.
A valuation may also be useful to establish the value of different parts of the property at relevant dates.
What About Building a Duplex?
A duplex project can be more complicated because you may intend to live in one dwelling and sell the other.
For example, you may own an existing family home, demolish it and construct two new dwellings.
You then move into one and sell the other.
The tax outcome will depend on a range of factors, including:
- The property’s status before development
- The timing of the project
- The proposed CGT transition rules
- How the land is allocated between the two dwellings
- Your intention when the development began
- Whether the sale is treated as capital or ordinary income
- Whether GST applies
The proposed 1 July 2027 CGT changes make the timing and documentation of these projects particularly important.
However, homeowners should not assume that delaying a project until after 1 July 2027 will automatically reduce tax.
The project should be assessed on its own facts before demolition, subdivision or construction begins.
The Important Question: Are You Building to Sell?
One of the biggest potential traps is assuming that the profit from selling a newly developed property will automatically be treated as a capital gain.
That is not necessarily the case.
If you develop a property with the intention of making a profit from selling it, the resulting profit may potentially be treated as ordinary income rather than a capital gain.
GST may also need to be considered where new residential premises are sold.
Factors that may be relevant include:
- Your original intention
- The scale of the development
- How the project is financed
- The extent of construction
- Whether you have undertaken similar projects
- Whether the property was intended to be held or sold
This is particularly important for homeowners considering a duplex or subdivision where one or more properties will be sold.
Tip: Get tax advice before signing building contracts or committing to a development if selling is part of the plan.
What If the Project Is Already Underway?
The transition to the proposed new CGT rules can become more complicated if your property has already been demolished or development has started before 1 July 2027.
The tax outcome may depend on:
- The property’s use
- The stage of the project
- How the final legislation applies to gains arising before and after the transition date
Detailed records of the property’s condition and the work completed around relevant dates may therefore become important.
Keep evidence such as:
- Dated photographs
- Council approvals
- Development applications
- Building plans
- Demolition invoices
- Building contracts
- Progress claims
- Finance records
- Property valuations
These records can help establish what the property looked like and what work had been completed at important dates.
Don’t Forget Inherited Properties
Inherited properties can have their own CGT rules.
For example, special rules can apply when a deceased person’s main residence is inherited and subsequently sold.
The tax outcome can change if the property is:
- Rented
- Occupied
- Subdivided
- Redeveloped
after the inheritance.
If you inherit a property and are considering a major renovation, subdivision or development, get advice before starting work.
A valuation at the date of death may be relevant depending on the CGT history of the property.
Records and, where appropriate, valuation evidence around other relevant dates may also become important under the proposed reforms.
Keep Good Property Records
Property owners should not wait until they are ready to sell before looking for their records.
Keep:
- Purchase contracts
- Settlement statements
- Property valuations
- Renovation invoices
- Building contracts
- Council approvals
- Development applications
- Surveyor reports
- Subdivision costs
- Legal costs
- Finance records
- Dated photographs
- Records showing when the property was occupied or rented
Tip: Create a digital property folder and save documents as the project progresses.
It is much easier than trying to reconstruct years of costs later.
What Should Property Owners Do Now?
If you are considering renovating, rebuilding or developing your home, start with the purpose of the project rather than the tax outcome.
Before you begin:
- Work out what you intend to do with the property.
- Consider whether the property will remain your main residence.
- Check whether part of the property will be rented or sold.
- Consider the potential CGT and GST implications.
- Obtain a valuation where appropriate.
- Keep detailed records before demolition or construction begins.
- Get professional advice before making major commitments.
The Bottom Line for Property Owners
Renovating, rebuilding or developing your home can create significant opportunities, but the tax implications should be considered before work begins.
The proposed 1 July 2027 CGT changes make timing, documentation and record keeping particularly relevant for homeowners considering major property projects.
Whether you are planning a knock-down rebuild, granny flat, subdivision or duplex, the best approach is to understand the tax implications before you demolish, develop or sell.
How Can We Help?
Property tax outcomes can depend heavily on decisions made before a project begins.
If you are considering a knock-down rebuild, granny flat, subdivision, duplex or other development, we recommend speaking with us before you demolish, sign building contracts, change the property’s use or commit to a sale.
We can help you understand the potential CGT, income tax and GST implications and identify the records or valuations that may be required.
Contact Camden Professionals on 08 9221 5522 or email info@camdenprofessionals.com.au to discuss your circumstances.
Frequently Asked Questions
Does renovating my home trigger CGT?
Generally, renovating your main residence does not by itself trigger CGT.
However, tax issues can arise if part of the property is used to generate income or if the property is later subdivided or sold.
Does a knock-down rebuild affect my main residence exemption?
Potentially.
The main residence rules can allow the exemption to continue during qualifying construction periods, generally for up to four years.
Specific conditions apply.
Should I get my property valued before 1 July 2027?
For some property owners, valuation evidence around the transition date may be useful, particularly where the property is partly taxable, is being redeveloped or subdivided, or its use is changing.
Whether a formal valuation is required will depend on your circumstances and the final legislation, so obtain advice before commissioning one solely for tax purposes.
Will waiting until after 1 July 2027 reduce my CGT?
Not necessarily.
The proposed reforms may produce different outcomes depending on the property and project.
The timing should be assessed alongside the main residence exemption, transition rules and intended use of the property.
Is building a duplex subject to CGT?
It can be.
The tax treatment depends on factors including how the property was used, your intention, whether one dwelling is sold and whether the activity is treated as a capital transaction or a profit-making development.
Can GST apply when I sell a new property?
GST can potentially apply to the sale of new residential premises in certain circumstances.
This should be considered before starting a development intended for sale.
General Information Warning
The material on this page and on this website has been prepared for general information purposes only and is not intended to provide tax advice for any person’s specific circumstances.
Tax outcomes depend on the individual facts and the law applying at the relevant time.
Before acting on the information in this article, you should obtain professional advice that takes into account your particular circumstances and the details of the proposed transaction or property project.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Recent Comments