




Division 296 Tax Explained: What Australia’s New Super Tax Means for Balances Over $3 Million
For many Australians, superannuation has been one of the most effective long-term wealth-building structures due to its concessional tax treatment. However, from 1 July 2026, changes under Division 296 tax will reduce some of the tax advantages available to individuals with larger superannuation balances.
The introduction of Division 296 tax means individuals with superannuation balances above certain thresholds need to carefully consider how they structure their retirement savings, investments and future contributions. For the 2026–27 financial year, the first threshold is set at $3 million, with a second threshold applying at $10 million.
These thresholds will be indexed in future years.
What Is Division 296 Tax?
Division 296 is a new tax measure that applies an additional tax on earnings associated with superannuation balances above specified thresholds. The purpose of the measure is to reduce the tax concessions available to individuals with very large superannuation balances.
For the 2026–27 financial year:
- The first threshold is $3 million
- A second threshold applies at $10 million
- Thresholds will be indexed over time
The additional tax does not mean your entire superannuation balance is taxed at a higher rate once it exceeds the threshold.Instead, the tax applies only to the relevant proportion of earnings connected to the amount above the applicable threshold.
How Does Division 296 Tax Work?
Division 296 tax is calculated based on the proportion of your superannuation balance that exceeds the relevant threshold.It does not apply to your entire superannuation balance.For example, if your superannuation balance is slightly above $3 million, the additional tax applies only to the portion relating to the amount above the threshold.
The calculation considers:
- Your total superannuation balance
- The applicable threshold
- The earnings attributable to the excess amount
This means the impact can vary significantly between individuals depending on their balance, investment performance and circumstances.
Does Division 296 Tax Mean Super Is Taxed at 30%?
No. A common misunderstanding is that once your super balance exceeds $3 million, your entire superannuation balance will automatically be taxed at 30%.
This is not how Division 296 works. The additional tax applies only to the relevant proportion of earnings associated with the balance above the threshold. Your existing superannuation tax treatment continues to apply to the portion within the normal limits.
What Happens Above the $10 Million Threshold?
A higher threshold applies for individuals with very large superannuation balances.
For the 2026–27 financial year:
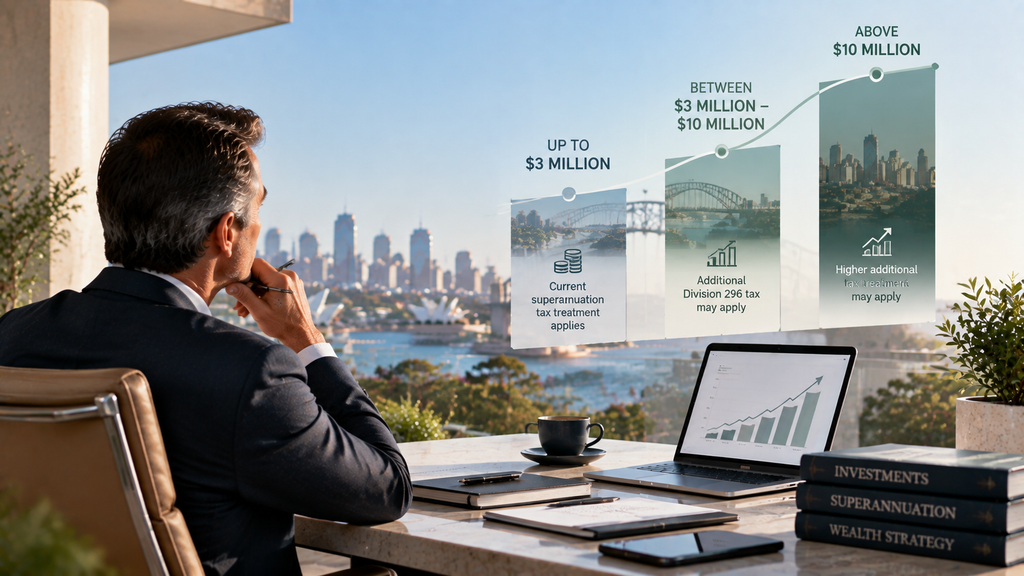
| Superannuation Balance | Additional Division 296 Treatment |
|---|---|
| Up to $3 million | Existing superannuation tax treatment applies |
| Between $3 million and $10 million | Additional Division 296 tax may apply |
| Above $10 million | Higher additional tax treatment may apply |
The purpose of the second threshold is to apply a higher level of taxation to extremely large superannuation balances.
How Are Earnings Calculated Under Division 296?
An important aspect of Division 296 is that the calculation is based on earnings determined under the legislation. The calculation considers changes in the value of superannuation interests and other relevant factors. For individuals with complex superannuation arrangements, including self-managed super funds (SMSFs), the calculation can become more complicated. Factors that may affect the outcome include:
- Investment income
- Capital gains
- Pension interests
- Changes in account balances
- Timing of contributions and withdrawals
Are Unrealised Gains Taxed Under Division 296?
The final Division 296 rules changed from earlier proposals. The calculation does not simply tax every unrealised increase in investment value. An increase in the value of an investment is not automatically taxed just because the market value has increased and the asset has not been sold. However, the calculation remains complex and depends on the specific circumstances of the individual.
Does Division 296 Mean Super Is No Longer Tax Effective?
No. Superannuation can still remain one of the most tax-effective investment structures available. Super continues to provide significant tax benefits, including:
- Concessional tax treatment in accumulation phase
- Potential tax-free earnings in eligible retirement-phase pensions
The introduction of Division 296 does not remove the benefits of superannuation. Instead, it changes the way individuals with very large balances need to think about future wealth accumulation.
Should You Stop Contributing to Super After Reaching $3 Million?
Not necessarily. Reaching the $3 million threshold does not automatically mean that superannuation is no longer suitable. The right strategy depends on factors such as:
- Your retirement goals
- Your investment strategy
- Your personal tax position
- Your access requirements
- Your estate planning objectives
For some individuals, continuing to use super may still provide significant advantages. For others, building wealth outside super may become an important consideration.
Superannuation vs Building Wealth Outside Super
As super balances grow, some individuals may consider whether future investments should remain inside super or be held through alternative structures.
Key considerations include:
| Consideration | Superannuation | Outside Super |
|---|---|---|
| Tax treatment | Generally concessional | Depends on structure |
| Access | Restricted until conditions of release are met | Generally greater flexibility |
| Investment options | Subject to super rules | Wider range of structures available |
| Estate planning | Specific superannuation rules apply | Depends on ownership structure |
The decision is not only about tax. Other factors, including access, flexibility and estate planning, should also be considered.
Could an Investment Company Be an Alternative?
For some individuals with significant wealth, an investment company may form part of a broader wealth strategy. An investment company may allow profits to remain within the company and be reinvested. This can be useful for individuals who:
- Are still accumulating wealth
- Do not require investment income personally each year
- Want greater control over investment capital
However, an investment company is not automatically better than super.
The structure has its own considerations, including:
- Corporate tax rates
- Administration costs
- Loss of some capital gains tax concessions
- Tax implications when extracting funds

Estate Planning Considerations
Division 296 discussions should not focus only on tax during your lifetime. Estate planning is also an important consideration for individuals with large superannuation balances. Superannuation does not automatically form part of your estate.
The outcome depends on:
- Beneficiary nominations
- Super fund rules
- Estate planning arrangements
Super Death Benefits Tax
The tax treatment of superannuation death benefits depends on who receives the benefit.
Generally:
- Payments to eligible dependants may receive concessional treatment.
- Payments to non-dependants, such as some adult children, may have different tax consequences.
For individuals with significant super balances, planning ahead can help manage potential tax outcomes for beneficiaries.
What Should High-Balance Super Members Do?
Individuals approaching or exceeding the $3 million threshold should review their overall wealth strategy. Important areas to consider include:
- Superannuation balance management
- Investment structure
- Contribution strategy
- Retirement planning
- Estate planning
The introduction of Division 296 does not mean immediate action is required for everyone. However, understanding the potential impact early can help create a more effective long-term strategy.
Final Thoughts
Division 296 tax represents a significant change for Australians with larger superannuation balances. However, it does not mean superannuation is no longer valuable. The key is understanding how the new rules interact with your personal circumstances and long-term goals. For some individuals, continuing to maximise superannuation benefits may remain the right approach. For others, combining super with investments held outside super may provide greater flexibility and control. A strategic review can help determine the most appropriate approach for your situation.
Frequently Asked Questions
Is super still tax effective after Division 296?
Yes. Superannuation can still provide significant tax advantages, even after Division 296 applies to larger balances.
Does Division 296 tax my entire super balance?
No. The additional tax applies only to the relevant proportion of earnings connected to amounts above the applicable threshold.
Does Division 296 apply from 1 July 2026?
Yes. The measure applies from the 2026–27 financial year.
Will everyone with more than $3 million in super pay Division 296 tax?
Not necessarily. The outcome depends on your balance, earnings and individual circumstances.
Should I move money out of super once I reach $3 million?
Not automatically. The decision depends on your retirement objectives, tax position, investment strategy and estate planning needs.
Is an investment company better than super?
Not always. An investment company may provide flexibility, but it also has different tax and administration considerations.
How Can We Help?
If your superannuation balance is approaching or exceeding $3 million, Camden Professionals can help review your current position and understand how the Division 296 changes may affect your broader wealth strategy. Professional advice can help you assess:
- Superannuation strategies
- Investment structures
- Retirement planning
- Estate planning considerations
Contact Camden Professionals to discuss your circumstances and explore your available options.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Tax Treatment of Buying and Selling ETFs in Australia
Exchange-Traded Funds (ETFs) have become increasingly popular in Australia as a convenient and cost-effective way for investors to gain exposure to a diverse range of asset classes, from equities and bonds to commodities and global markets. However, like any investment, buying and selling ETFs comes with its own set of tax implications that Australian investors need to be aware of. This article outlines the key tax considerations when investing in ETFs from an Australian perspective.
What is an ETF?
Before diving into the tax treatment, let’s first define what an ETF is. An ETF is a type of investment fund that is listed on a stock exchange, and it generally tracks the performance of a specific index, sector, commodity, or asset class. ETFs are bought and sold like stocks, making them an accessible and liquid investment option. They offer investors diversification, lower costs, and ease of trading compared to individual securities.
Tax Treatment When Buying ETFs
For tax purposes, buying an ETF in Australia is no different from purchasing any other type of security, such as shares or bonds. There are no immediate tax consequences at the time of purchase; you are simply acquiring an asset that will be subject to tax at the time of sale, dividend receipt, or any capital gains events.
However, it’s important to note that the nature of the underlying assets in the ETF can influence how tax is applied. For example:
- Australian-domiciled ETFs: These ETFs hold Australian assets and are generally subject to Australian tax rules. If the ETF distributes income or capital gains, these will typically be taxed according to Australian tax laws.
- International-domiciled ETFs: If the ETF invests in international assets, you may need to deal with additional tax implications, such as foreign withholding tax on dividends.
Tax on Dividends from ETFs
One of the key tax events when holding an ETF is the receipt of dividends. ETFs that invest in Australian stocks typically distribute dividends to investors, which may be franked (if the underlying company has paid tax) or unfranked.
- Australian ETFs (Franked Dividends): If you hold an Australian-domiciled ETF and receive franked dividends, you are entitled to claim a franking credit. Franking credits represent the tax already paid by the underlying company on the dividend, which can be used to reduce your tax liability. For example, if you receive a $100 dividend with a $30 franking credit, your gross income for tax purposes is $130.
- Unfranked Dividends: If the dividends are unfranked, they will be included in your taxable income and taxed at your marginal tax rate. There are no franking credits to offset the tax.
- Foreign ETFs (Foreign Dividends): When receiving dividends from an international ETF, you may be subject to foreign withholding tax. The rate of withholding tax will depend on the country where the underlying securities are located. You may be able to claim a foreign income tax offset to reduce the impact of foreign tax paid.
Capital Gains Tax (CGT) on Selling ETFs
When you sell an ETF, any profit you make may be subject to Capital Gains Tax (CGT). The tax treatment of capital gains on ETFs follows the same general rules as the sale of shares and other investments in Australia.
- Capital Gain or Loss: The capital gain or loss is calculated by subtracting the purchase price of the ETF (including any associated costs such as brokerage fees) from the sale price. If the sale price is higher than the purchase price, you make a capital gain; if it’s lower, you incur a capital loss.
- CGT Discount for Individuals: If you hold the ETF for more than 12 months, you may be eligible for the CGT discount. For individual investors, this means you can discount the capital gain by 50%. For example, if you sell an ETF and make a capital gain of $10,000, and you’ve held the ETF for more than a year, only $5,000 of that gain will be taxable.
- Capital Losses: If you sell an ETF for a loss, you can use the capital loss to offset other capital gains you may have made during the financial year. If you do not have any capital gains to offset, you can carry forward the loss to offset future capital gains.
- Foreign-Domiciled ETFs: If the ETF is foreign-domiciled, the same CGT rules apply, but you may need to account for any foreign taxes or exchange rate movements when calculating your gain or loss.
Tax on Distributions and Reinvestments
Some ETFs offer reinvestment plans, where the distributions are automatically reinvested in additional units of the ETF. From a tax perspective, reinvested dividends or distributions are treated the same as cash dividends. Even if you don’t receive the cash, the dividend is included in your taxable income for the year. This means that you are still liable to pay tax on the distributions, regardless of whether they were reinvested or taken as cash.
Tax Implications of Synthetic ETFs
Synthetic ETFs use derivatives to replicate the performance of an index, rather than directly owning the underlying assets. While the tax treatment for synthetic ETFs is similar to that of traditional ETFs, there are some additional complexities, particularly around income distributions. Synthetic ETFs may generate capital gains or income in ways that are less transparent to investors, which may affect their tax reporting.
Tax Reporting and Record-Keeping
It is essential to maintain accurate records of all ETF transactions, including purchase prices, sale prices, dividends received, and any associated fees. Australian tax authorities (the Australian Taxation Office or ATO) require taxpayers to report any capital gains or losses, as well as income received from ETFs, on their annual tax return. The ATO’s myTax system can help streamline this process, and many online brokerages also provide annual tax summaries that can be useful when completing your return.
For investors holding foreign ETFs, it’s important to keep records of any foreign taxes withheld, as this may be relevant when claiming a foreign income tax offset.
Summary of Key Tax Considerations for ETFs in Australia
- Dividends:
- Franked dividends: Eligible for franking credits to reduce your tax liability.
- Unfranked dividends: Taxable at your marginal tax rate.
- Foreign dividends: Subject to foreign withholding tax, potentially offset by foreign income tax credits.
- Capital Gains Tax (CGT):
- Any gain from selling an ETF is subject to CGT.
- If held for more than 12 months, eligible for a 50% CGT discount.
- Capital losses can be used to offset capital gains.
- Reinvested Distributions: Even if you reinvest distributions, they are still taxable in the year they are paid out.
- Record-Keeping: Maintain accurate records of all ETF transactions, dividends, and fees to ensure correct reporting at tax time.
In conclusion, while ETFs provide an efficient and diversified way to invest, it is important for Australian investors to understand the tax implications involved. From dividend taxation to capital gains, the right tax strategy and diligent record-keeping can ensure you optimize your investment returns while remaining compliant with Australian tax laws. Always consider seeking advice from a qualified tax professional to ensure you are managing your tax obligations effectively, especially if you are investing in international ETFs.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How to Build Wealth Using Passive Income
In recent years, the term passive income has become a buzzword, often associated with easy money and financial freedom. But what exactly is passive income, and how can you use it to build wealth?
At its core, passive income is the idea of earning money with minimal ongoing effort after an initial investment of time or resources. Instead of working a traditional 9-to-5 job, passive income allows you to set up income streams that, once established, continue to generate cash flow with little day-to-day involvement.
If you’re looking to start building wealth through passive income, here are some popular ways you can do so through investments in property, shares, and other options.
Property Investment
Investing in property has long been a popular choice for building wealth, especially in Australia. Property investment offers the potential for both regular income and long-term growth. Here’s how property investments can generate passive income:
- Rental Income
When you own a rental property, tenants pay you rent, which can become a steady income stream. While you’ll need to manage the property or hire a property manager to handle the day-to-day tasks, this can be relatively hands-off if you choose the right property and a reliable manager. With good maintenance and smart pricing, rental income can provide a regular cash flow to help grow your wealth over time.
- Capital Growth (Increasing Property Value)
Over time, properties can increase in value, especially if you buy in areas that are experiencing economic growth or infrastructure development. This means you can sell the property in the future for more than what you originally paid. Think of it as a long-term investment strategy where you benefit from both rental income and the appreciation of the property’s value.
- Things to Keep in Mind
While property can provide both regular income and potential long-term capital growth, it’s important to remember there are costs involved. Maintenance, property management fees, and other expenses can add up. Property investing isn’t a “set and forget” strategy, but with proper planning and the right advice, it can be a relatively straightforward way to generate wealth.
Shares: Dividends and Capital Gains
Shares are another popular way to generate passive income. Here’s how investing in the stock market can pay off:
- Dividends
Some companies pay a portion of their profits to shareholders in the form of dividends. These dividends provide a regular income stream, often paid quarterly. In Australia, dividends may come with franking credits, which reduce the amount of tax you owe on the income. This tax benefit can be a significant advantage for investors, especially those in higher tax brackets.
- Capital Gains
Shares can also provide passive income through capital gains. As companies grow and perform well, their share price tends to increase, allowing you to sell shares at a higher price than you paid for them. However, it’s important to remember that share prices can also decline, so while the upside potential is significant, the risks are also present.
- Reinvesting Dividends
One way to grow your investment without having to add extra money is by reinvesting your dividends into buying more shares. This strategy, known as dividend reinvestment, allows your investment to compound over time, helping your wealth grow steadily.
Exploring Other Investment Options for Passive Income
While property and shares are the most common forms of passive income, there are other options available that can suit different risk profiles and preferences. Here are a few alternatives:
- Cash Investments: A Low-Risk Option
For those who prefer low-risk investments, cash investments like term deposits or high-interest savings accounts can be a good way to generate passive income. These investments earn interest over time, providing a predictable return. Although the returns tend to be modest compared to other options, they are stable and offer easy access to funds in case of emergencies.
Cash investments can also help diversify your portfolio by providing a steady, low-risk income stream. They’re a good introduction to passive income and can be used as a reliable source of cash flow while you build up more aggressive investment options.
- Managed Funds
If you want passive income but prefer not to manage individual stocks or assets yourself, managed funds might be an ideal option. With managed funds, professional fund managers handle the investments, diversifying your money across a range of assets such as shares, bonds, and property. This approach takes the guesswork out of investing and offers a hands-off way to grow your wealth.
- Bonds
Bonds are essentially loans you give to governments or corporations in exchange for periodic interest payments. While they offer a predictable stream of income, bonds also come with risks—particularly with longer-term bonds or those with lower credit ratings. Still, bonds can be a solid part of a passive income strategy, especially for conservative investors looking for reliable income with less market volatility.
Why Understanding Passive Income Matters
Knowing how to build passive income streams is an important first step in wealth-building, but it’s equally important to have realistic expectations. Passive income isn’t a “get rich quick” strategy. In fact, most passive income options require careful planning, research, and sometimes a bit of upfront work.
There are always risks involved, whether it’s the volatility of the stock market, the costs of property maintenance, or the possibility that interest rates will change. That’s why it’s important to:
- Do your research: Learn about the various investment options and understand the potential risks and rewards.
- Start small: If you’re new to investing, it’s wise to begin with smaller investments and gradually increase as you become more comfortable.
- Diversify your portfolio: Spreading your investments across different asset classes (property, shares, bonds, etc.) can help reduce risks and create a more stable passive income stream.
Final Thoughts
Building wealth using passive income is a realistic goal when you take a strategic, informed approach. Property and shares are some of the most common ways to generate income without ongoing effort, but there are many other options to explore, depending on your risk tolerance and financial goals.
Whether you start with a high-interest savings account, invest in dividend-paying stocks, or buy rental property, the key is to take the first step, learn as you go, and stick with a long-term strategy. With patience and the right guidance, you can create multiple passive income streams that work for you, helping you build wealth for the future.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
When can I access my super?
Generally, superannuation is designed to provide retirement income and your savings can’t be accessed until you reach a certain age and retire. In this article we look at how you can access your super.
It sounds simple enough, but in practice there are multiple ways you may be eligible to legally access your super under Australian legislation. These are known collectively as conditions of release.
The five most common conditions of release are:
- Being over preservation age and retiring
- Being over preservation age and starting a transition-to-retirement income stream (TRIS)
- Being 60 or over and ceasing an employment arrangement
- Being 65 or over
- Death Benefit
Preservation age or over and retiring
Your preservation age is between the ages of 55 and 60, depending on your date of birth.
If your date of birth is:
- Before 1 July 1960, your preservation age is 55
- Between 1 July 1960 and 30 June 1961, your preservation age is 56
- Between 1 July 1961 and 30 June 1962, your preservation age is 57
- Between 1 July 1962 and 30 June 1963, your preservation age is 58
- Between 1 July 1963 and 30 June 1964, your preservation age is 59
- On or after 1 July 1964, your preservation age is 60.
Once you’ve reached your preservation age and you retire from the workforce, you can access your super.
However, if you access your super prior to turning 60, you may have to pay tax on any payments you receive, regardless of the type of payment you get (i.e. lump sum or super pension). The amount of tax you’ll have to pay depends on whether your payment contains a taxable component, a tax-free component or a combination of both.
Preservation age or over and starting a transition-to-retirement income stream (TTR or TRIS)
If you reach your preservation age (see above), you can start a transition-to-retirement income stream (TRIS). This is a superannuation pension stream that you can draw while you’re still working. It can be a way to scale back your working hours and plan effectively for your retirement. For example, you can work less hours or salary sacrifice into super to save tax, while using your TRIS to supplement your salary so you can maintain your lifestyle.
Age 60 or over and ceasing employment
You can access your super if you’re aged 60 and over and you stop working, even if you subsequently get another job with another employer. As mentioned earlier, super payments are generally tax free once you turn 60.
Age 65 or over
This is the simplest condition of release. Once you turn 65, you can access your super even if you haven’t retired.
Death Benefit
- When you die, your dependants or nominated beneficiaries will be entitled to receive what’s left of your super. If the recipients are your dependants, such as a spouse or child under the age of 18, your super balance can be paid either as a lump sum or an income stream.
- If your beneficiary (or beneficiaries) are not your dependants, the payments must be made as lump sums. Lump sum payments are generally tax free when paid to a dependent. Tax may be payable on income streams, depending on whether they have a taxable component, a tax-free component or a combination of both.
Early Release of Super
There are additional conditions of release that will allow you to access your super early if you meet strict eligibility criteria:
- On compassionate grounds
- If you’re suffering severe financial hardship
- If you’re diagnosed with a terminal medical condition
- If you’re temporarily incapacitated
- If you’re permanently incapacitated
- Through the First Home Super Saver Scheme
- If you’re a temporary resident departing Australia
- If you terminate gainful employment with less than $200 in your super account
On Compassionate grounds
You may be able to access your super early on compassionate grounds provided you meet strict eligibility conditions, and your super fund allows it. If you’re approved, the amount is paid and taxed as a lump sum.
Compassionate grounds can include the need to:
- Pay for your own medical treatment or transport (or for the treatment or transport of one of your dependants, such as a spouse or child)
- Make a mortgage or council rates payment to prevent you from losing your home
- Pay expenses to accommodate yourself or a dependant with a severe disability
- Pay for the palliative care of yourself or a dependent
- Pay for the death, funeral or burial expenses of a dependant
In addition, the government is currently considering extending the compassionate grounds early release provisions to include dental treatment for life-threatening conditions, or those that cause chronic or acute pain. If you’re approved to access some of your super early on compassionate grounds, the amount is paid and taxed as a lump sum.
Severe financial hardship
Accessing super early due to severe financial hardship is also possible, provided you meet strict eligibility conditions and your super fund allows it.
The Australian Taxation Office (ATO) will consider you to be in severe financial hardship if you meet the following three criteria:
- You have received government welfare payments from the Department of Human Services (DHS) for at least 26 consecutive weeks (except for ABSTUDY, Austudy or Youth Allowance student payments)
- You are still receiving those payments when you apply for the early release
- You are unable to pay your reasonable and immediate family living expenses.
If you’re approved to access some of your super early due to severe financial hardship, the amount is paid and taxed as a lump sum.
Terminal medical condition
If you have a terminal medical condition, two medical practitioners must certify that you have an illness or injury that will result in your death within 24 months of the date of the certificate. At least one of these medical practitioners must be a specialist in the area of your terminal illness or injury.
You can choose to access all or some of your super, subject to the rules of your fund. There are no legal restrictions on the amount you can access, but withdrawals must be taken as tax-free lump sums.
Temporary incapacity
You can access super benefits early due to temporary incapacity provided the benefits come from specific sources.You’re temporarily incapacitated (according to Australian super legislation) if either physical or mental ill-health issues cause you to temporarily:
- Be unable to work at all
- Work less hours than you normally would.
If you’re temporarily incapacitated and you need to supplement your income via your super, you may be able to access two potential benefits:
- Income protection insurance benefits
- Any voluntary employer-funded benefits that you may have in your super fund.
This includes any super contributions made by your employer that are more than the 10% compulsory superannuation guarantee contributions that they are required to make on your behalf. Both these potential benefits must be paid as a taxable income stream. They cannot be converted to a lump sum.
Permanent incapacity
You can access your super benefits early due to permanent incapacity provided you meet these eligibility conditions.
Two medical practitioners must certify that you have physical or mental health issues that are likely to stop you from working ever again in the job you’re qualified to do.
If you’re permanently incapacitated, you can access:
- Any total and permanent disability (TPD) insurance benefits that you may have in your super fund (either as a lump sum or income stream)
- Any other super benefits you have accumulated. There are no restrictions on the amount of your own benefits that you can access, and you can access them as a lump sum or as a regular income stream of payments.
If the payments you receive via your super fund are TPD insurance benefits, these payments are tax free. However, if you’re accessing permanent incapacity benefits from your super fund that aren’t TPD insurance payments, these payments are taxable.
The First Home Super Saver Scheme
The first home super saver (FHSS) scheme allows you to make personal voluntary contributions into your super fund to help you save for your first home.
- Concessional contributions are taxed at only 15%, which is usually less than your marginal income tax rate. Assessable FHSS amounts also benefit from a 30% FHSS tax offset.
- You can withdraw up to $15,000 of your voluntary contributions from any one financial year, up to a total of $50,000 across multiple years, plus associated earnings.
You don’t need to be an Australian citizen or Australian resident for tax purposes to use the FHSS scheme. It’s important not to sign any property contract before you request a FHSS determination.
When you’re ready to use the funds to help buy a home in Australia, you can submit a request to release your FHSS amount plus associated earnings.
Temporary resident departing Australia
The Departing Australia Superannuation Payment (DASP) is available to departed temporary residents who worked and earned super in Australia. It is not available for permanent Australian residents, nor for Australian and New Zealand citizens.
In addition to having accumulated super while working as a temporary resident in Australia:
- Your temporary visa to work in Australia must have expired
- You must have left Australia.
Temporary residents working in Australia must have a work visa to be employed legally. A range of work visas are available, including skilled worker visas and working holiday-maker visas. The type of work visa you have is important, as it affects how much tax you’ll pay when you receive your DASP.
The Australian tax payable on a DASP depends on three factors:
- Whether you have a working holidaymaker visa or another type of visa that enables you to work in Australia
- Whether your DASP contains taxable and non-taxable (tax-free) components
- Whether the taxable component of your DASP contains taxed and untaxed elements.
If you’re a temporary resident departing Australia who has paid or is liable to pay Division 293 tax, you can apply to the Australian Taxation Office (ATO) to be released from both your current and future tax obligations. You must have received a DASP payment prior to making this application. You may also be entitled to a refund of some of the Division 293 tax you have paid. The ATO will make this assessment based on your specific situation.
To apply for DASP you should contact your super fund. In some cases your super fund may have transferred your super balance to the ATO if it’s been six months or more since you left Australia, or if your visa has expired. The ATO will class your super balance as unclaimed super money that you’re entitled to claim as a DASP.
Terminating gainful employment with a super balance less than $200
You can access your super benefits early under Australian law if you have a fund balance of less than $200 and your employment has been terminated – whether you lost your job or you resigned.
To apply for release you should contact your super fund. In some cases the super fund may have transferred your super money to the ATO, for example if there has been no activity on your super account for 12 months. You can check online if the ATO is holding any of your super via your myGov account.
Whether you’re applying to your super fund or to the ATO for the early release of balances less than $200, you’ll generally need to provide the following supporting documentation:
- A letter from your employer confirming that your employment has been terminated (or an Employment Separation Certificate)
- Your payment summary from the relevant employer (including details of any termination payment that you may have received when your employment ceased).
No tax is payable on any payments you receive due to your super fund balance being less than $200.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 10-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help? if you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How Much Do You Need for a Comfortable Retirement
Planning for retirement can be daunting, especially when trying to determine how much money you will need to live comfortably. In Australia, several factors influence the amount required, including lifestyle preferences, healthcare costs, and life expectancy. Find out how much you need for a comfortable retirement.
Defining a Comfortable Retirement
The Association of Superannuation Funds of Australia (ASFA) provides guidelines on what constitutes a “comfortable” retirement. According to ASFA, a comfortable retirement lifestyle enables an older, healthy retiree to be involved in a broad range of leisure and recreational activities and maintain a good standard of living. This lifestyle includes owning a reasonable car, occasional international travel, and the ability to dine out regularly.
ASFA Retirement Standard
ASFA updates its Retirement Standard quarterly, providing estimates for both “comfortable” and “modest” retirement lifestyles. As of the latest update in May 2024, the annual income required for a comfortable retirement is:
- Single person: Approximately $49,000 per year
- Couple: Approximately $69,000 per year
These figures assume retirees own their home outright and are relatively healthy.
Calculating Your Retirement Needs
To estimate how much you need for a comfortable retirement, consider the following factors:
- Current Age and Retirement Age: Determine how many years you have until retirement and how many years you expect to be in retirement. The average life expectancy in Australia is around 82 years for men and 85 years for women.
- Desired Lifestyle: Reflect on the lifestyle you want in retirement. This includes your travel plans, hobbies, dining preferences, and other activities.
- Annual Expenses: Based on the ASFA Retirement Standard, estimate your annual living expenses. Adjust these figures according to your personal lifestyle preferences and inflation.
- Existing Savings and Superannuation: Assess your current superannuation balance, other savings, and investments. The average superannuation balance at retirement for Australians aged 60-64 is approximately $270,000 for men and $157,000 for women.
- Additional Income Sources: Consider other income sources you may have in retirement, such as rental income, part-time work, or the Age Pension. The Age Pension can provide a safety net, but it is designed to cover only basic living expenses.
Retirement Savings Target
A common rule of thumb is to aim for a retirement income of about 70% of your pre-retirement income. However, this can vary based on individual circumstances. Here’s a simplified approach to calculate your retirement savings target:
- Estimate Your Annual Retirement Income Needs: For a comfortable retirement, use ASFA’s estimates or adjust based on your lifestyle. For example, if you anticipate needing $50,000 per year and expect to be in retirement for 25 years, you’ll need $1.25 million.
- Consider Investment Returns and Inflation: Factor in the potential investment returns and inflation over your retirement period. A financial advisor can help you estimate these variables more accurately.
- Account for Additional Costs: Include potential healthcare costs, home maintenance, and other unexpected expenses in your calculations.
When you picture your retirement, are you anxiously tracking your expenses or are you engaging in all the activities that you wanted to, confident that your money won’t run out? Ideally, it’s the latter — but there’s no guarantee things will pan out that way.
Soaring inflation, a volatile share market, and even changing preferences can all spark worry about not having enough to last you in your post-work years. Fortunately, there’s a lot you can do to lay the groundwork for the retirement you want.
Steps to Achieve Your Retirement Goal
- Increase Super Contributions: Maximize your superannuation contributions to take advantage of tax benefits and compound interest. Consider salary sacrificing or making additional after-tax contributions.
- Review Your Investment Strategy: Ensure your superannuation is invested in a way that aligns with your risk tolerance and retirement goals. As you approach retirement, consider shifting to a more conservative investment strategy to protect your savings.
- Minimise Debt: Aim to pay off your mortgage and other debts before retiring to reduce your living expenses.
- Track Your Progress: Regularly review your retirement savings plan to ensure you are on track. Adjust your savings rate and investment strategy as needed.
- Seek Professional Advice: Consult with a financial advisor to develop a personalized retirement plan. They can help you navigate the complexities of superannuation, investments, and retirement income streams.
Will you take up part-time work?
Whether it’s out of necessity, boredom or some other reason, many people choose to re-enter the workforce after retiring. While there are no rules against doing this, you’ll have to be mindful of the potential tax implications, as well as how it might affect your Age Pension (if you receive one).
Under the Work Bonus rules, you can earn up to $300 from work each fortnight without it impacting your Age Pension. Anything more will be included in the income test, which along with the assets test, may reduce your entitlements.
As for your super, superannuation guarantee payments from your employer will resume, and you’ll also be able to make voluntary contributions of your own. You can keep contributing to your super until you turn 75. From the ages of 67 to 75, however, you’ll need to satisfy the work test if you intend to claim a tax deduction on any personal contributions. This involves showing that you were gainfully employed for at least 40 hours in a consecutive 30-day period within a given financial year.
Determining how much you need for a comfortable retirement in Australia requires careful planning and consideration of various factors. By understanding your desired lifestyle, estimating annual expenses, and maximizing your savings, you can work towards a financially secure and enjoyable retirement. Regularly reviewing your plan and seeking professional advice can help ensure you stay on track to meet your retirement goals.
How can we help? if you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How to Give Your Super an Annual Checkup
Superannuation is a crucial part of your retirement planning in Australia, and ensuring your super is on track can significantly impact your financial future. An annual checkup of your superannuation account helps you stay informed, make necessary adjustments, and maximize your retirement savings. Ignoring your superannuation is never a good idea. After all, it is probably your biggest or second biggest asset if you own a home. Give your super an annual check up.
But because retirement is a long way off, some Australians adopt a set-and-forget approach. Leaving it, unchecked until their impending retirement. By then, it could be too late. If super payments have been missed or you have been underpaid, it is almost impossible to fix.
Superannuation apps and online services help make it easy to check your super payments and balance regularly. Here’s a step-by-step guide on how to give your superannuation an effective annual checkup.
- Review Your Superannuation Balance
Start by checking the current balance of your superannuation account. Compare it to the previous year’s balance to track growth. Your balance should ideally be increasing each year, reflecting contributions and investment returns.
- Assess Your Contributions
Ensure that the contributions being made to your superannuation are accurate. This includes:
- Employer Contributions: Confirm that your employer is making the correct super guarantee (SG) contributions, which should be at least 11% of your ordinary time earnings.
- Personal Contributions: Review any personal contributions you’ve made, such as concessional (before-tax) and non-concessional (after-tax) contributions. Check if you are maximizing your contribution caps.
The tax office has an ‘estimate my super’ tool and the regulator’s moneysmart has an ’employer contributions calculator’ to help you work out how much super guarantee (SG) should be paid. It tells you the four dates a year that your employer must legally pay the SG.
The SG is rising on July 1, 2024, from 11% to 11.5%. The super guarantee will increase by a further 0.5% on July 1, 2025. Be sure to check your super to make sure you’re receiving these increases.
- Evaluate Investment Options
Superannuation funds offer various investment options ranging from conservative to aggressive. Assess the performance of your chosen investment option over the past year. Consider the following:
- Returns: Compare your investment returns against the fund’s benchmark and other available options.
- Risk Level: Ensure the risk level of your investments aligns with your retirement goals and time horizon.
- Check Fees and Charges
Fees can significantly impact your super balance over time. Review the fees you are paying, including administration, investment management, and advice fees. Compare these fees with other super funds to ensure you are getting value for money. If the fees seem high, consider switching to a lower-cost fund.
- Review Insurance Coverage
Many superannuation accounts include insurance for life, total and permanent disability (TPD), and income protection. Check:
- Coverage Levels: Ensure the coverage is adequate for your current circumstances.
- Premium Costs: Assess whether the premiums are reasonable and do not excessively erode your super balance.
- Beneficiary Nominations: Make sure your beneficiary nominations are up-to-date, reflecting any changes in your personal circumstances.
- Consider Consolidation
If you have multiple superannuation accounts, consolidating them into one account can save on fees and simplify management. Use the ATO’s online tools to locate and consolidate your super accounts. Before consolidating, check for any exit fees and compare the insurance and investment options.
- Utilize Government Incentives
Check if you are eligible for government incentives, such as the super co-contribution or the low-income super tax offset (LISTO). These incentives can boost your super balance, especially if you are a low or middle-income earner.
- Plan for Retirement
Estimate how much you’ll need for a comfortable retirement and compare it to your current super balance. Use retirement calculators provided by super funds or the ASIC MoneySmart website. This can help you determine if you need to adjust your contributions or investment strategy.
- Review Your Fund’s Performance
Compare the performance of your super fund with other funds in the market. Consistently underperforming funds may warrant a switch to a better-performing fund.
- Seek Professional Advice
If you’re unsure about any aspect of your superannuation, consider seeking advice from a licensed financial advisor. They can provide personalized advice tailored to your financial situation and retirement goals.
An annual superannuation checkup is essential to ensure your retirement savings are on track. By reviewing your balance, contributions, investment options, fees, insurance coverage, and taking advantage of government incentives, you can optimize your superannuation strategy. Stay informed and proactive about your super to secure a comfortable and financially stable retirement.
How can we help? if you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How to take advantage of the 1 July super cap increase
Starting from July 1st, 2024, there will be an increase in the maximum amount you can contribute to your superannuation. We’ll guide you on how to make the most of this change.
Contribution limits for superannuation will rise from $27,500 to $30,000 for concessional contributions and from $110,000 to $120,000 for non-concessional contributions, effective July 1st, 2024. These caps are adjusted in accordance with the growth in wages, as measured by the average weekly ordinary times earnings (AWOTE) of the preceding year’s December quarter. The recent notable growth in wages has prompted the first increase in contribution caps in three years.
Other areas impacted by indexation include:
- The Government super co-contribution – Income threshold
- The super guarantee maximum contribution base (the limit for compulsory super guarantee payments)
- The tax-free thresholds for redundancy payments
- The CGT contribution cap (amount that can be contributed to super following the sale of eligible business assets)
For individuals with available income to spare, superannuation presents an appealing option, boasting a 15% tax rate on concessional super contributions and the potential for tax-free withdrawals upon retirement. For business proprietors experiencing a prosperous year or concluding a business sale, capitalizing on this opportunity to bolster their superannuation holdings is advisable. However, strategic timing of contributions becomes crucial for optimizing outcomes.
If you anticipate a capital gains tax obligation in a given year, employing ‘catch-up’ contributions allows you to make larger-than-normal contributions. Utilising the associated tax deduction can effectively mitigate your capital gains tax liability. But, this strategy will only work if you meet the eligibility criteria to make catch up contributions and you lodge a Notice of intent to claim or vary a deduction for personal super contributions, with your super fund.
Optimising the timing of your contributions can significantly enhance your tax position. For those anticipating a capital gains tax event, utilising ‘catch-up’ contributions can be a strategic move. This approach allows for larger contributions that boost your super balance and offer a tax deduction that can mitigate your capital gains tax liability. It’s essential to meet the eligibility criteria and notify your super fund with a Notice of Intent to claim a deduction for these contributions.
Using the ‘Bring Forward Rule’
Under the bring forward rule, you have the option to consolidate up to two years’ worth of upcoming non-concessional contributions into the current year, provided your total superannuation balance allows it and you are under the age of 75.
If you activate the bring forward rule prior to June 30th, the maximum allowable contribution is $330,000. However, delaying the activation of the bring forward rule until or after July 1st increases the maximum contribution under this provision to $360,000.
Catch Up Contributions
If your super balance is below $500,000 on the prior 30 June, and you want to quickly increase the amount you hold in super, you can utilise any unused concessional super contributions amounts from the last 5 years.
Let’s look at the example of Gary who has only been using $15,000 of his concessional super cap for the last few years. Gary’s super balance at 30 June 2023 was $300,000, so he is well within the limit to make catch up contributions.
| Concessional Cap | Used | Unused | |
| 2018-19 | $25,000 | $15,000 | $10,000 |
| 2019-20 | $25,000 | $15,000 | $10,000 |
| 2020-21 | $25,000 | $15,000 | $10,000 |
| 2021-22 | $27,500 | $15,000 | $12,500 |
| 2022-23 | $27,500 | $15,000 | $12,500 |
| 2023-24 | $27,500 | ? | ? |
Gary could access his $27,500 concessional cap for 2023-24 plus the unused $55,000 from the prior 5 financial years. If Gary doesn’t access the unused amounts from 2018-19 by 30 June 2024, the $10,000 will no longer be available.
Transfer balance cap unchanged
The transfer balance cap which limits the amount of capital that can be transferred into a tax-exempt retirement phase will not increase for the 2024–2025 income year, based on the release of December 2023 consumer price index (CPI) numbers from the Australian Bureau of Statistics (ABS). This means the figure will remain at $1.9 million for the 2023–2024 and 2024–2025 income years.
The transfer balance cap is a lifetime limit on the amount an individual can transfer into one or more retirement phase accounts. Individuals will have a personal transfer balance cap equal to the general transfer balance cap when a retirement phase income stream is commenced for the first time. For example, if an individual commences a retirement stream in the 2024–2025 income year, their personal transfer balance cap will be $1.9 million.
For individuals who started their retirement phase income stream in an earlier year with a lower general transfer balance cap, if the full amount of the personal transfer balance cap was never used, proportional indexing may apply. This means the individual’s personal transfer balance cap will be indexed based on the highest ever balance in the transfer balance account.
Where an individual exceeds their personal transfer balance cap, the excess is required to be commuted and excess transfer balance tax needs to be paid.
How can we help? if you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.