




Downsizer Contributions: How Selling Your Home Could Boost Your Superannuation
For many Australians approaching retirement, selling the family home can be about more than finding a smaller or more manageable property. It can also create an opportunity to strengthen retirement savings through a downsizer contribution to superannuation.
The Australian Government’s downsizer rules allow eligible homeowners to contribute some of the proceeds from selling their home directly into superannuation. For eligible individuals, the contribution can be up to $300,000, while an eligible couple may potentially contribute up to $600,000 between them, subject to each person’s eligibility and the applicable rules.
- The eligible age for a downsizer contribution is currently 55 years or older.
- Since 1 January 2023, you must be at least 55 years old when making the contribution.
- There is no maximum age limit for a downsizer contribution, provided you meet the other eligibility requirements.
However, downsizing does not automatically mean there will be hundreds of thousands of dollars available to put into super. Property prices, selling costs and the cost of the replacement home all need to be considered.Understanding the rules before selling is important because there are specific eligibility requirements, contribution deadlines and conditions that need to be satisfied.
Why Downsizing Doesn’t Always Mean Having More Cash
The term “downsizing” can sometimes create the impression that selling a large family home will automatically release a substantial amount of money.
That is not necessarily the case.
Many Australians sell their existing home and purchase another property in a desirable location. They may choose a newer apartment, a low-maintenance townhouse or a property closer to family, the coast, healthcare services or a major city.
In some areas, the replacement property can cost almost as much as the home being sold. There are also selling costs, legal fees, moving expenses, stamp duty where applicable and other transaction costs to consider. This means the amount available for a downsizer contribution will depend on the individual’s circumstances and the actual proceeds available from the sale. For those who do have surplus funds, however, the downsizer rules can provide an opportunity to move a significant amount into the superannuation system.
Downsizer Contribution Eligibility: What Are the Rules?
The ATO sets out a few conditions that must be met before a contribution can qualify as a downsizer contribution.
Generally, you must:
- Be 55 years of age or older when making the contribution.
- Have owned the property for at least 10 years before the sale, generally measured from the date of acquisition to the date of disposal.
- Have owned the property as an individual or jointly with your spouse.
- You or your spouse must have held an ownership interest in the property, and the relevant 10-year ownership requirement must be satisfied.
- Make the contribution from the proceeds of selling an eligible Australian residential property.
- Satisfy the relevant main residence requirements.
- Make the contribution within the required timeframe.
- Have not previously made a downsizer contribution from the sale of another dwelling.
The ATO states that the contract for sale must generally have been entered into on or after 1 July 2018. The contribution must generally be made within 90 days of the change of ownership, unless the Commissioner grants an extension. It is therefore important not to treat the downsizer contribution as an informal arrangement that can be organised whenever convenient after settlement.
The 90-Day Downsizer Contribution Deadline
One of the most important practical considerations is timing. Eligible downsizer contributions generally need to be made within 90 days from the change of ownership of the property. The ATO can grant an extension in certain circumstances.
This means homeowners planning to use the downsizer rules should consider their superannuation arrangements before the property settles. Waiting until after settlement to investigate the rules could create unnecessary pressure, particularly if there are questions about eligibility or the amount that can be contributed. The timing should also be considered alongside the settlement of the replacement property, because selling the existing home and buying another property can involve significant cash-flow requirements.
How Much Can You Contribute?
An eligible individual can generally make a downsizer contribution of up to $300,000 from the proceeds of selling an eligible home. The ATO states that the maximum amount an individual can contribute from the sale of one home is the lesser of:
- $300,000, or
- the sale proceeds remaining after taking into account other downsizer contributions made by the individual or their spouse.
Importantly, multiple downsizer contributions can potentially be made from the sale of the same home, provided the total does not exceed the applicable maximum. For example, an eligible homeowner might contribute $150,000 shortly after settlement and another $150,000 later, provided the relevant conditions are met. A couple may also be able to contribute up to $300,000 each if both individuals meet the requirements.
Does a Downsizer Contribution Count Towards Your Normal Super Contribution Caps?
A qualifying downsizer contribution does not count towards your concessional or non-concessional contribution caps. This can make the downsizer rules particularly useful for people who may otherwise have limited opportunities to contribute a significant amount into super. However, once contributed, the money becomes part of your superannuation balance and the normal superannuation rules will apply. The contribution should therefore be considered as part of your broader retirement and superannuation strategy rather than in isolation.
Can Downsizer Contributions Help Build Retirement Wealth?
For homeowners who have substantial equity in their property, downsizer contributions can provide another way to structure retirement savings. Money held in the family home can provide security and reduce housing costs, but it does not generally produce investment income in the same way as assets held within superannuation.
Moving some surplus capital into super may allow the money to form part of a broader retirement investment strategy. However, contributing money to super also means the funds become subject to the superannuation rules.
The decision should therefore be considered as part of an overall retirement plan rather than simply as a tax strategy. The appropriate approach will depend on factors such as:
- Age
- Existing superannuation balances
- Pension arrangements
- Investment objectives
- Cash-flow requirements
- Estate planning
What Does This Have to Do with SMSFs?
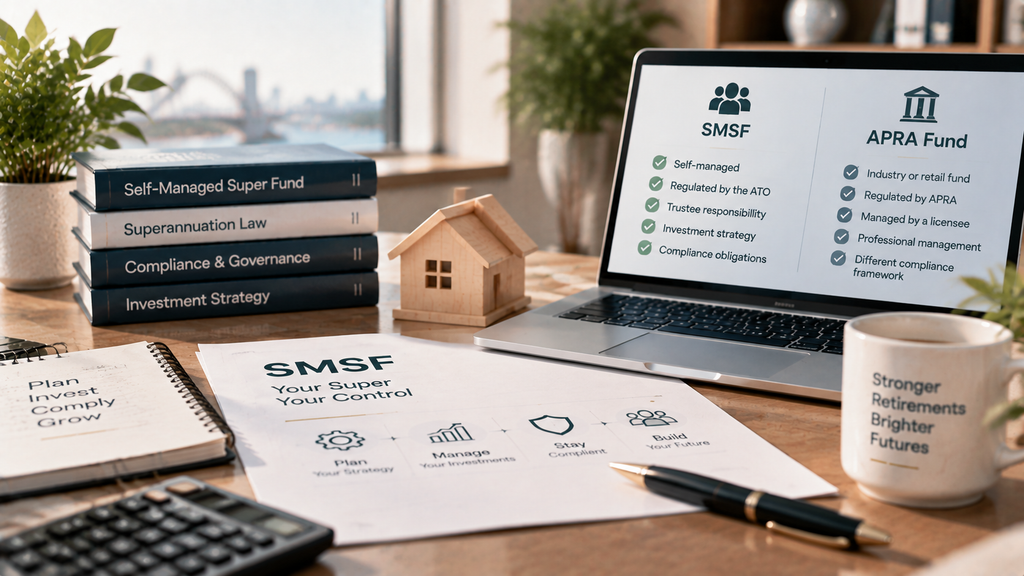
Downsizer contributions can also be relevant to people who have a Self-Managed Super Fund (SMSF). An SMSF is a superannuation fund that members manage themselves. SMSFs are regulated by the Australian Taxation Office, rather than APRA. APRA’s own licensing guidance confirms that SMSFs are not RSEs and are instead regulated by the ATO.
This distinction is important. An SMSF trustee remains responsible for ensuring that contributions are correctly accepted and recorded and that the fund complies with superannuation legislation. The supplied material also highlights that SMSF trustees remain responsible for the fund’s investment strategy and compliance even where professional investment managers or other advisers are engaged.
SMSFs vs APRA-Regulated Super Funds
Most Australians have their superannuation with an APRA-regulated fund, such as an industry or retail super fund. APRA oversees registrable superannuation entities and their licensed trustees. APRA’s prudential framework includes requirements covering areas such as:
- Governance
- Investment governance
- Risk management
- Insurance
- Member outcomes
For example, APRA’s SPS 530 Investment Governance requires RSE licensees to maintain an investment governance framework, establish investment objectives and strategies, conduct due diligence and undertake stress testing. APRA’s SPS 510 Governance also establishes minimum governance requirements for RSE licensees and places ultimate responsibility for sound and prudent management with the board. These APRA requirements apply to APRA-regulated superannuation entities and should not be confused with the regulatory framework governing SMSFs.
Most industry and retail super funds are regulated by APRA, while SMSFs are regulated by the ATO. The key practical difference is that SMSF trustees take direct responsibility for the fund’s compliance, investment strategy and administration. For SMSF members, the ATO is the key regulator.
What Are the Risks of an SMSF?
Having greater control over superannuation can also mean greater responsibility. SMSF trustees are responsible for making sure the fund’s investment strategy is appropriate, keeping records, meeting reporting obligations and complying with the superannuation laws. SMSFs do not have the same protections available to members of APRA-regulated funds.
There are also ongoing costs, including:
- Accounting
- Administration
- Auditing
- Regulatory levies
- Investment advice
- Potentially legal and insurance expenses
This means an SMSF should not be established simply because a downsizer contribution is available. The decision to use an SMSF should be considered separately from the decision about whether a downsizer contribution is appropriate.
Can You Use a Downsizer Contribution More Than Once?
Generally, no. The downsizer rules contain a once-only requirement. The ATO states that an individual must not have previously made a downsizer contribution from the sale of any dwelling. This can include multiple partial disposals of an ownership interest in the same dwelling.
This makes it particularly important to understand the rules before making the contribution. A decision to make a downsizer contribution can have long-term consequences because the opportunity generally cannot simply be repeated when another property is sold in the future.
What About the Capital Gains Tax Rules?
The property must generally satisfy the relevant main residence requirements for the downsizer rules. The ATO’s eligibility guidance refers to both an ownership test and a main residence test. This is an important area where professional advice can be useful, particularly where a property has been:
- Used partly as an investment property
- Rented out for periods
- Inherited
- Jointly owned
- Subject to other ownership arrangements
Not every residential property transaction will automatically qualify.
Downsizer Contributions and Capital Gains Tax (CGT)
Selling a property may also create Capital Gains Tax considerations.The tax outcome will depend on the individual’s circumstances, including:
- How the property was used
- Whether it was used to produce income
- Ownership history
- The period the property was held
- Whether any exemptions or concessions apply
The downsizer contribution rules and Capital Gains Tax rules are separate considerations.Meeting the downsizer contribution requirements does not automatically mean there are no CGT implications. Understanding both areas before selling can help avoid unexpected tax outcomes.
Is Downsizing the Right Strategy for You?
Downsizing can be an effective retirement planning strategy for some Australians, but it is not suitable for everyone.The decision involves more than just the opportunity to contribute money into superannuation.Factors to consider may include:
- Future housing needs
- Lifestyle preferences
- Access to funds
- Retirement income requirements
- Superannuation position
- Tax implications
- Estate planning objectives
For some people, remaining in their current home may continue to be the preferred option. For others, selling the family home and contributing surplus funds into superannuation may better align with their retirement goals.
What Should You Consider Before Making a Downsizer Contribution?
Before selling your home, consider:
Your Eligibility
Make sure all downsizer contribution requirements are satisfied before proceeding.
Your Financial Position
Review:
- The expected sale proceeds
- Replacement property costs
- Selling expenses
- Available cash reserves
Your Superannuation Strategy
Consider how the contribution fits with:
- Your existing super balance
- Retirement income plans
- Investment strategy
Your Estate Planning
A significant contribution into superannuation may affect how your assets are structured and passed on in the future.
How Professional Advice Can Help
Downsizer contributions involve several rules and requirements that need careful consideration. Professional advice can help you understand:
- Whether you qualify
- How much you may be able to contribute
- How the contribution fits into your retirement strategy
- Potential tax considerations
- The impact on your broader financial position
Planning before selling your home can help ensure the decision supports your long-term retirement objectives.
Final Thoughts
Downsizer contributions provide eligible Australians with an opportunity to move some proceeds from the sale of their home into superannuation. For some homeowners, this can help strengthen retirement savings and provide greater flexibility. However, selling a home is a significant financial decision and should be considered carefully. The downsizer rules should be reviewed alongside:
- Retirement plans
- Superannuation strategy
- Tax considerations
- Investment objectives
- Estate planning arrangements
Understanding the requirements before selling can help ensure decisions are made with a clear understanding of the potential outcomes.
Frequently Asked Questions
What is a downsizer contribution?
A downsizer contribution allows eligible Australians to contribute some proceeds from selling their home into their superannuation fund.
How much can I contribute through downsizer rules?
Eligible individuals may be able to contribute up to $300,000 from the sale of an eligible home.
Can couples both make downsizer contributions?
Yes. If both individuals meet the eligibility requirements, each person may be able to contribute up to $300,000.
What age do I need to be to make a downsizer contribution?
You must generally be at least 55 years old when making the contribution and meet the other eligibility requirements.
Does a downsizer contribution count towards normal contribution caps?
No. A qualifying downsizer contribution does not count towards concessional or non-concessional contribution caps.
Can I make a downsizer contribution more than once?
Generally, no. The downsizer rules include a once-only requirement.
Can I make a downsizer contribution into an SMSF?
Yes, provided the SMSF accepts the contribution and all eligibility requirements are satisfied.
How Can We Help?
If you are considering selling your home and want to understand how downsizer contributions may apply to your retirement strategy, Camden Professionals can help review your options.
Our team can assist with:
- Retirement planning considerations
- Superannuation strategies
- Tax implications
- Wealth planning
- Financial structuring considerations
Contact Camden Professionals to discuss your circumstances.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Why Your Super Insurance Might Not Cover What You Expect
Many Australians are surprised to learn they already have life insurance through their superannuation fund. In fact, millions of super accounts include some form of insurance cover, often without members actively choosing it.
While insurance inside super can be a cost-effective way to protect yourself and your family, it’s also one of the least understood aspects of retirement savings. Many people don’t know what type of cover they have, how much they’re insured for, what exclusions apply, or when their insurance could be cancelled.
Assuming your default insurance will always provide enough protection can be a costly mistake. Changes to superannuation laws, account inactivity rules and differences between funds mean your cover may not be as comprehensive as you think.
Before relying on the insurance attached to your super, it’s worth understanding how it works, when it may stop, and whether it still meets your financial needs.
What Insurance Is Available Through Superannuation?
Many Australian superannuation funds offer members insurance as part of their account.
Depending on the fund, this may include:
- Life insurance (Death Cover) – Pays a benefit if you die or are diagnosed with a terminal medical condition.
- Total and Permanent Disability (TPD) Insurance – Provides a benefit if illness or injury permanently prevents you from working, subject to the policy’s definitions.
- Income Protection Insurance – Replaces part of your income for a limited period if you’re temporarily unable to work due to illness or injury.
The amount and type of insurance available varies between super funds and is subject to each insurer’s terms, conditions and eligibility criteria.
Myth 1: “Everyone Automatically Gets Insurance Through Super”
Automatic Cover Is No Longer Guaranteed
A common misconception is that every superannuation member automatically receives insurance.
Since changes to Australian superannuation legislation, this is no longer the case.
Generally, insurance is not automatically provided if:
- You are under 25 years of age.
- Your account balance is less than $6,000.
- You have not elected to receive insurance.
Some exceptions apply, particularly for employees working in hazardous occupations where certain super funds provide automatic cover under specific arrangements. If you’re starting your first job or are early in your career, it’s worth checking whether you actually have any insurance at all.
Myth 2: “Default Cover Will Be Enough”
Default Insurance Is a Starting Point—Not a Personal Financial Plan
Insurance offered through super is designed to provide basic protection across a large group of members.It isn’t tailored to your personal financial situation.
Your current cover may be insufficient if you have:
- A mortgage.
- Young children.
- A partner who relies on your income.
- Investment loans.
- Business debts.
- Other financial commitments.
Many Australians require significantly more insurance than their default super policy provides.
Check for Exclusions and Premium Loadings
Not every policy provides the same level of protection.
It’s important to understand:
- Waiting periods.
- Benefit periods.
- Occupational exclusions.
- Medical exclusions.
- Pre-existing condition exclusions.
- Definitions used for disability claims.
Some members also pay premium loadings.
A premium loading is an increase above the standard insurance premium and may apply if you:
- Work in a high-risk occupation.
- Smoke or use tobacco products.
- Have certain medical conditions.
- Participate in hazardous activities.
If your occupation or smoking status has changed, you should review your policy to ensure you’re not paying higher premiums unnecessarily.
Myth 3: “My Insurance Will Move with Me If I Change Super Funds”
Changing Super Funds Can Cancel Your Insurance
Many Australians change super funds when changing jobs or consolidating their retirement savings. However, insurance usually does not automatically transfer with your super balance.
If you move to another fund:
- Your existing insurance may end.
- You may lose valuable cover.
- Replacing your policy could require new medical assessments.
- New premiums may be higher due to age or changes in health.
Some insurers allow policies to be converted into retail insurance outside super, but eligibility rules apply and premiums may increase.Before switching funds, always confirm what will happen to your existing insurance.
Myth 4: “If I Stop Contributing, Nothing Will Change”
Inactive Super Accounts Can Lose Insurance
Australian law requires most super funds to cancel insurance where an account has been inactive for 16 months or more.
An account is generally considered inactive if no contributions or rollovers have been received during that period. Your fund will usually attempt to contact you before insurance is cancelled. However, if your contact details are outdated, you may not receive these important notices. Insurance may also cease if:
- Your account balance becomes too low.
- Premiums can no longer be deducted.
- You exceed the policy’s maximum cover age.
Regularly checking your super account and keeping your contact details current can help prevent accidental loss of cover.
Myth 5: “More Super Accounts Mean More Insurance Protection”
Multiple Policies May Simply Mean Multiple Premiums
It’s common for Australians to accumulate several super accounts throughout their working lives. Each account may include separate insurance policies.
While this can sometimes provide additional protection, it can also result in:
- Paying multiple insurance premiums.
- Reduced retirement savings.
- Overlapping or unnecessary cover.
- Administrative complexity when making claims.
Insurance benefits are not always cumulative, and claim outcomes differ between policies. Before consolidating super accounts—or deciding to keep multiple accounts—review each policy carefully to determine whether the cover remains valuable.
Myth 6: “Insurance Through Super Is Always the Cheapest Option”
Lower Cost Doesn’t Always Mean Better Value
Because super funds purchase insurance for large groups of members, premiums are often competitive. However, cheaper premiums don’t necessarily provide better protection.
Important considerations include:
- Benefit amounts.
- Policy definitions.
- Waiting periods.
- Exclusions.
- Premium increases over time.
- Flexibility to adjust cover.
Retail insurance purchased outside super may offer broader cover or greater flexibility depending on your personal circumstances. The right choice depends on your financial goals, family situation and risk profile.
Why It’s Important to Review Your Super Insurance Regularly
Life changes and your insurance should change with it.
You should review your cover whenever you:
- Buy a home.
- Get married or enter a de facto relationship.
- Have children.
- Change jobs.
- Become self-employed.
- Take on significant debt.
- Receive an inheritance.
- Approach retirement.
A policy that suited you five years ago may no longer provide adequate protection today.
Questions to Ask When Reviewing Your Insurance
Before relying on your super insurance, consider asking:
- What type of insurance do I currently have?
- How much cover do I have?
- Is the cover sufficient for my family’s needs?
- What exclusions apply?
- Am I paying a premium loading?
- What happens if I change super funds?
- What happens if I stop working or stop contributing?
- Are there better options available?
Understanding the answers can help you make informed financial decisions.
How a Financial Adviser Can Help
Superannuation insurance can be complicated, particularly when balancing retirement savings with adequate personal protection.
A licensed financial adviser can help you:
- Review your current insurance.
- Identify gaps in your protection.
- Compare cover inside and outside super.
- Explain policy exclusions and definitions.
- Assess whether your level of cover remains appropriate.
- Coordinate insurance when consolidating super accounts.
Regular reviews ensure your insurance continues to align with your financial objectives and changing personal circumstances.
Conclusion
Insurance through superannuation provides valuable financial protection for millions of Australians, but it shouldn’t be treated as a “set and forget” benefit. Default cover is designed to provide a basic level of protection and may not reflect your income, debts, family responsibilities or long-term financial goals.
Changes to superannuation laws, account inactivity rules and differences between insurance policies mean your cover can reduce or even cease without you fully appreciating the consequences. Likewise, switching super funds or consolidating accounts without understanding the impact on your insurance could result in the loss of valuable protection. Taking the time to review your superannuation insurance, understand your policy’s terms and seek professional advice where appropriate can help ensure you and your family have the level of financial protection you expect when it matters most.
Frequently Asked Questions
Do all Australians automatically receive insurance through their super?
No. Under current legislation, most people under 25 or with a super balance below $6,000 do not automatically receive insurance unless they choose to opt in or qualify under specific exceptions.
What types of insurance are available through super?
Most super funds offer Life (Death) Cover, Total and Permanent Disability (TPD) Insurance and, in many cases, Income Protection Insurance.
Can I lose my insurance if I change super funds?
Yes. In many cases, insurance is linked to your membership with a particular super fund. Changing funds may result in your existing cover ending unless appropriate arrangements are made.
Can insurance be cancelled if I stop contributing to my super?
Yes. Most super funds are required to cancel insurance on inactive accounts after 16 months unless you instruct the fund to retain your cover, subject to legislative requirements.
Is insurance through super cheaper than buying it directly?
Often it is competitively priced because super funds purchase insurance in bulk. However, lower premiums don’t always mean the policy provides the most appropriate level of cover or features for your needs.
Why should I review my insurance regularly?
Major life events such as buying a home, starting a family, changing employment or approaching retirement can significantly affect your insurance needs. Regular reviews help ensure your cover remains appropriate.
Should I seek professional advice before changing super funds?
Yes. Before switching or consolidating super accounts, it’s important to understand how the change may affect your insurance and whether alternative cover is required.
Sources
- Australian Taxation Office (ATO)
- Australian Securities and Investments Commission (ASIC)
- Australian Prudential Regulation Authority (APRA)
- Services Australia
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
EOFY Financial Review 2026 Tips
As the new financial year begins, many Australians focus solely on lodging their tax return. But EOFY is also one of the best times to step back and review your broader financial position.
With interest rates still elevated, cost-of-living pressures continuing, superannuation changes on the horizon, and ongoing discussion around trust structures and tax reform following the Federal Budget, a proactive financial review can make a significant difference to your long-term wealth.
The Australian Government, including the ATO, Moneysmart (ASIC) and Services Australia, consistently encourages Australians to review their finances, superannuation, insurance and budgeting regularly to stay on track with their goals.
- Homeowners with a Mortgage
If you have a home loan, EOFY is an ideal time to check whether your mortgage is still competitive. Even a small reduction in your interest rate can save thousands over the life of the loan.
Review:
- Your current interest rate.
- Whether you are making use of an offset account.
- Fixed vs variable loan structure.
- Whether refinancing could improve cash flow.
According to Moneysmart, borrowers should compare home loans regularly and understand all fees and features before refinancing.
- Investors Holding Too Much Cash
Higher interest rates have improved savings account returns, but inflation can still reduce the real value of cash over time.
EOFY is a good opportunity to assess:
- Whether your savings account is earning a competitive rate.
- How much emergency cash you genuinely need.
- Whether surplus funds could be allocated to longer-term investments such as shares, ETFs, bonds or property.
Moneysmart notes that diversification and matching investments to your risk tolerance and time horizon are key principles of investing.
Market volatility can feel uncomfortable, but it can also create opportunities. EOFY is the perfect time to review your portfolio and asset allocation.
Ask yourself:
- Is my portfolio too heavily weighted to one asset class?
- Do I need more diversification?
- Should I rebalance towards fixed income now that bond yields are higher?
- Are there capital losses that could be used to offset gains for tax purposes?
The ATO provides guidance on capital gains tax (CGT) and how capital losses can be used to offset capital gains.
- Business Owners and Trust Structures
Business owners using discretionary trusts or bucket companies should pay close attention to recent developments in trust taxation and Division 7A.
The recent Bendel High Court decision and proposed Federal Budget reforms have increased scrutiny on:
- Trust distributions.
- Bucket company arrangements.
- Unpaid present entitlements (UPEs).
- Section 100A risks.
- Future trust taxation changes from 1 July 2028.
EOFY is the right time to review:
- Trust resolutions.
- Distribution strategies.
- Division 7A loan arrangements.
- Asset ownership structures.
- Succession and estate planning objectives.
- Employees and Anyone with Superannuation
Superannuation remains one of the most tax-effective investment vehicles available to Australians. EOFY is the ideal time to review your super before the new year begins.
Check:
- Your super balance.
- Investment option (growth, balanced, conservative, etc.).
- Whether you have multiple super accounts.
- Insurance held inside super.
- Whether concessional or non-concessional contributions make sense for you.
The ATO encourages Australians to consolidate multiple super accounts to reduce unnecessary fees and insurance duplication. ATO Super for Individuals and Families
- Families Reviewing Insurance and Household Budgets
Inflation and rising construction costs mean many Australians may now be underinsured.
Review:
- Home and contents insurance sums insured.
- Income protection insurance.
- Life and TPD insurance.
- Private health insurance.
- Emergency savings buffer.
ASIC’s Moneysmart website recommends reviewing insurance regularly, especially after major life events or significant changes in asset values.
Why EOFY Is More Than Just Tax Time
EOFY should not just be about preparing receipts for your accountant. It is an opportunity to:
- Reduce unnecessary borrowing costs.
- Improve cash flow.
- Rebalance investments.
- Maximise super contributions.
- Review tax structures.
- Ensure insurance cover is adequate.
- Reset financial goals for the year ahead.
In a changing economic environment, proactive planning is often more valuable than reactive decision-making.
Frequently Asked Questions (FAQs)
How often should I review my financial position?
At least annually, ideally around EOFY. You should also review your finances after major life events such as buying property, changing jobs, starting a business, getting married, or nearing retirement.
Should I refinance my mortgage in 2026?
It depends on your current rate, loan features, fees and long-term plans. Comparing loans and speaking with your lender or mortgage broker can help determine whether refinancing would improve your situation.
What should I check in my superannuation account?
Review your balance, investment option, fees, insurance cover, contribution levels and whether you have multiple accounts that could be consolidated.
Can I use capital losses to reduce tax?
Yes. Under ATO rules, capital losses can generally be used to offset capital gains in the same financial year or carried forward to future years. ATO CGT Guide
ATO CGT Guide
Do trust structures need to be reviewed after the Federal Budget?
Is holding cash still a good strategy?
Cash is important for emergencies and short-term needs, but holding excessive cash long term may reduce purchasing power due to inflation. A balanced strategy tailored to your goals and risk tolerance is usually more effective.
Final Thought
EOFY is not just a deadline for tax returns. It is a strategic checkpoint for your entire financial life. Whether you are a homeowner, investor, business owner or employee, taking the time to review your mortgage, savings, investments, super, insurance and tax structures can help ensure your money is working harder for you in the year ahead.
Sources:
- Australian Taxation Office (ATO): https://www.ato.gov.au
- ASIC Moneysmart: https://moneysmart.gov.au
- Services Australia: https://www.servicesaustralia.gov.au
- ATO Capital Gains Tax Guide: ATO CGT Guide
- Moneysmart Home Loans Guide: Moneysmart Home Loans Guide
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.