




Setting Up an SMSF: What You Need to Know Before You Start
Thinking about setting up a Self-Managed Super Fund (SMSF)? An SMSF can give you greater control over how your retirement savings are invested, but it also comes with significant responsibilities.
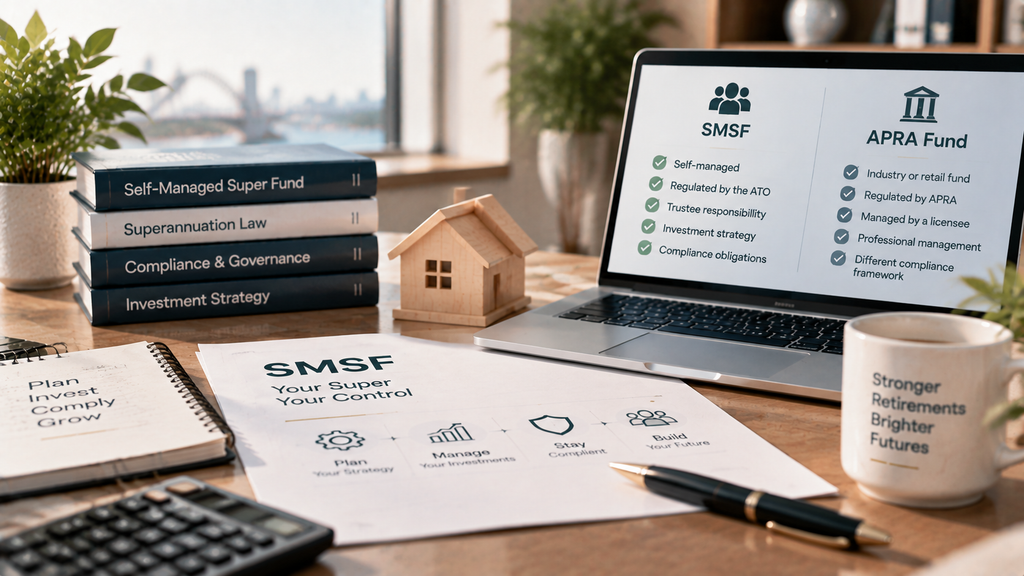
Unlike an APRA-regulated super fund, where a professional trustee is responsible for managing the fund, an SMSF puts those responsibilities largely in the hands of its trustees. That means choosing an SMSF is not simply about investment choice. You need to consider the costs, administration, investment strategy, compliance requirements and whether managing your own super is appropriate for your circumstances.
What Is an SMSF?
A Self-Managed Super Fund is a private superannuation fund established for a small number of members. The members are generally also trustees, or directors of a corporate trustee.
- The key difference is control. SMSF trustees are responsible for making investment decisions and ensuring the fund complies with superannuation and tax laws.
- The ATO requires an SMSF to have an investment strategy before it starts investing. The strategy must reflect the purpose and circumstances of the fund and its members and must be reviewed regularly.
- This makes an SMSF quite different from simply selecting an investment option within an existing super fund.
Is an SMSF Right for You?
Before establishing an SMSF, consider why you want one. An SMSF may appeal to people who want greater control over their investments, have more complex investment needs or want to manage a broader range of assets within the superannuation rules. However, control also means responsibility.
As an SMSF trustee, you are responsible for ensuring investments comply with the law, maintaining records, preparing reports, arranging an annual audit and ensuring the fund’s investment strategy remains appropriate. The ATO makes it clear that trustees remain responsible for the fund’s investments even when professional advisers are used.
1. Look at the Investment Options
One of the main reasons people consider an SMSF is investment flexibility. Depending on the fund’s investment strategy and the superannuation rules, an SMSF can invest in assets such as shares, managed investments, term deposits and property. But greater choice does not mean every investment is permitted.
The ATO states that SMSF investments must be permitted under the fund’s trust deed and superannuation law, have clear legal ownership, be made on a commercial arm’s-length basis and satisfy the sole purpose test. There are also restrictions around transactions involving members and related parties. For example, the ATO states that, subject to limited exceptions, an SMSF generally cannot acquire assets from members or related parties, provide financial assistance to members or related parties, or use fund assets to provide a present-day benefit. Before investing, make sure you understand both the opportunity and the restrictions.
2. Have a Clear SMSF Investment Strategy
The ATO says an SMSF investment strategy should consider matters including:
- Diversification
- Investment risk and likely returns
- Liquidity
- The fund’s ability to meet expenses and retirement benefits
- The circumstances and needs of members
- Members’ retirement timeframes and risk appetite
Your investment strategy should be in writing and reviewed regularly. This is important because an SMSF should not be established simply to buy a particular asset. The investment strategy needs to explain how the fund’s investments relate to the retirement objectives of its members. This is important because where an SMSF is established with a particular investment in mind, trustees still need to consider whether that investment is appropriate having regard to the fund’s overall investment strategy and the circumstances of its members.
3. Compare SMSF Costs
Running an SMSF involves ongoing costs.
These can include:
- Establishment costs
- Accounting and tax return preparation
- Annual audit fees
- ATO supervisory levy
- Administration costs
- Investment advice
- Legal costs
- Brokerage and investment expenses
- Insurance where appropriate
The important question is not simply how much an SMSF costs each year. It is whether the benefits, flexibility and control justify those costs for your circumstances. For some people, the costs and administration of an SMSF may outweigh the benefits. For others, particularly those with more complex investment requirements, the additional control may be an important consideration.
4. Consider Your Investment Performance
Investment performance should be considered carefully, but it should not be the only reason for choosing an SMSF. Past performance does not guarantee future returns. If you are comparing an existing APRA-regulated super product with the potential benefits of an SMSF, make sure you are comparing like with like. Consider:
- Investment returns
- Investment risk
- Fees and expenses
- Diversification
- Liquidity
- Asset allocation
- Your investment timeframe
APRA conducts an annual performance test for certain APRA-regulated superannuation products. The test is designed to improve transparency and hold trustees accountable for underperformance. APRA also publishes broader product performance information covering investment returns, fees and performance-test outcomes. These resources can provide useful information when comparing an existing super fund with other APRA-regulated options.
5. Don’t Forget Insurance
Insurance is another issue to consider when deciding whether to establish an SMSF. Some super funds provide members with insurance options such as:
- Life insurance
- Total and permanent disability cover
- Income protection
If you move from an existing fund to an SMSF, you should check what insurance arrangements you currently have and whether transferring or replacing that cover could affect you. Insurance should be considered separately from the investment decision because losing existing cover can have important consequences.
6. Understand the SMSF Trustee Responsibilities
Perhaps the biggest difference between an SMSF and an APRA-regulated super fund is the level of responsibility placed on the trustee. SMSF trustees need to ensure the fund:
- Complies with superannuation legislation
- Maintains appropriate records
- Has and follows an investment strategy
- Meets tax and reporting obligations
- Arranges an annual independent audit
- Makes investments on an arm’s-length basis
- Complies with contribution and payment rules
The ATO also warns SMSF trustees about investment schemes that promise unusually high returns.Trustees need to understand what they are investing in and ensure every investment decision is consistent with the fund’s purpose and legal requirements.
7. Think About Property and Other Complex Investments
The Australian Taxation Office (ATO) has strict rules governing when a self-managed super fund (SMSF) can invest in property. Generally, the property must be acquired for the sole purpose of providing retirement benefits to fund members, rather than for personal use or benefit. An SMSF generally cannot acquire residential property from a member or related party, and residential property owned by the SMSF cannot be used by members or their relatives.
Different rules can apply to eligible business real property, including commercial property used in a business. Any property investment must also be consistent with the fund’s investment strategy and comply with the relevant superannuation rules. Recent changes have also affected the ability of SMSFs to borrow to purchase residential property.
From 10 August 2026, SMSFs are generally no longer able to enter into new limited recourse borrowing arrangements (LRBAs) to acquire residential property. Existing arrangements entered into before the change may be protected under transitional rules.
Importantly, the restriction does not extend to eligible commercial property, so SMSFs may still be able to use an LRBA to acquire business or commercial property where the relevant superannuation and borrowing rules are satisfied.
For anyone considering establishing an SMSF specifically to purchase property, it is important to understand these rules before setting up the fund or entering into a purchase contract. Professional advice should be obtained to ensure the proposed investment and funding arrangement comply with the relevant superannuation and tax requirements.
8. SMSF or APRA-Regulated Super Fund?
The decision does not have to be based simply on investment choice. An APRA-regulated super fund generally provides professional trustee oversight, investment options and administration without requiring the member to manage the fund’s compliance themselves. An SMSF provides greater direct control but places considerably more responsibility on the trustees. The right structure depends on your objectives, investment preferences, circumstances, costs and willingness to take on the responsibilities of being an SMSF trustee.
Final Thoughts
Choosing an SMSF is a significant financial decision. The attraction is usually greater control and flexibility, but those benefits come with additional administration, costs and legal responsibilities. Before establishing an SMSF, consider your investment objectives, the types of assets you want to invest in, the likely costs, insurance arrangements and the time and expertise required to manage the fund. The ATO provides detailed guidance on establishing and running an SMSF, including investment strategies and investment restrictions.
APRA also publishes performance information that can help consumers understand how APRA-regulated superannuation products are performing.An SMSF should be established because it is appropriate for your overall retirement strategy, rather than simply because it offers more investment choices.
FAQs About Choosing an SMSF
What is an SMSF?
A Self-Managed Super Fund is a private superannuation fund where the members generally act as trustees and are responsible for managing the fund and complying with superannuation laws.
How many members can an SMSF have?
An SMSF can have up to six members, subject to the relevant superannuation rules.
Do SMSFs need an investment strategy?
Yes.The ATO requires an SMSF to have an investment strategy and to review it regularly.
Can an SMSF invest in property?
Yes, an SMSF can invest in certain types of property, but strict superannuation rules apply.
The investment must be consistent with the fund’s investment strategy and satisfy the relevant legal requirements.
Are SMSFs regulated by APRA?
No. SMSFs are regulated by the Australian Taxation Office (ATO). APRA regulates most large superannuation entities, including APRA-regulated super funds.
What should I consider before setting up an SMSF?
Consider investment choice, costs, administration, insurance, compliance responsibilities, your investment strategy and whether you are comfortable taking responsibility for managing your own superannuation.
How Can We Help?
If you have any questions or would like further information, please contact Camden Professionals on:
Phone: 08 9221 5522
Email: info@camdenprofessionals.com.au
You can also arrange a meeting so we can discuss your requirements in more detail.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Downsizer Contributions: How Selling Your Home Could Boost Your Superannuation
For many Australians approaching retirement, selling the family home can be about more than finding a smaller or more manageable property. It can also create an opportunity to strengthen retirement savings through a downsizer contribution to superannuation.
The Australian Government’s downsizer rules allow eligible homeowners to contribute some of the proceeds from selling their home directly into superannuation. For eligible individuals, the contribution can be up to $300,000, while an eligible couple may potentially contribute up to $600,000 between them, subject to each person’s eligibility and the applicable rules.
- The eligible age for a downsizer contribution is currently 55 years or older.
- Since 1 January 2023, you must be at least 55 years old when making the contribution.
- There is no maximum age limit for a downsizer contribution, provided you meet the other eligibility requirements.
However, downsizing does not automatically mean there will be hundreds of thousands of dollars available to put into super. Property prices, selling costs and the cost of the replacement home all need to be considered.Understanding the rules before selling is important because there are specific eligibility requirements, contribution deadlines and conditions that need to be satisfied.
Why Downsizing Doesn’t Always Mean Having More Cash
The term “downsizing” can sometimes create the impression that selling a large family home will automatically release a substantial amount of money.
That is not necessarily the case.
Many Australians sell their existing home and purchase another property in a desirable location. They may choose a newer apartment, a low-maintenance townhouse or a property closer to family, the coast, healthcare services or a major city.
In some areas, the replacement property can cost almost as much as the home being sold. There are also selling costs, legal fees, moving expenses, stamp duty where applicable and other transaction costs to consider. This means the amount available for a downsizer contribution will depend on the individual’s circumstances and the actual proceeds available from the sale. For those who do have surplus funds, however, the downsizer rules can provide an opportunity to move a significant amount into the superannuation system.
Downsizer Contribution Eligibility: What Are the Rules?
The ATO sets out a few conditions that must be met before a contribution can qualify as a downsizer contribution.
Generally, you must:
- Be 55 years of age or older when making the contribution.
- Have owned the property for at least 10 years before the sale, generally measured from the date of acquisition to the date of disposal.
- Have owned the property as an individual or jointly with your spouse.
- You or your spouse must have held an ownership interest in the property, and the relevant 10-year ownership requirement must be satisfied.
- Make the contribution from the proceeds of selling an eligible Australian residential property.
- Satisfy the relevant main residence requirements.
- Make the contribution within the required timeframe.
- Have not previously made a downsizer contribution from the sale of another dwelling.
The ATO states that the contract for sale must generally have been entered into on or after 1 July 2018. The contribution must generally be made within 90 days of the change of ownership, unless the Commissioner grants an extension. It is therefore important not to treat the downsizer contribution as an informal arrangement that can be organised whenever convenient after settlement.
The 90-Day Downsizer Contribution Deadline
One of the most important practical considerations is timing. Eligible downsizer contributions generally need to be made within 90 days from the change of ownership of the property. The ATO can grant an extension in certain circumstances.
This means homeowners planning to use the downsizer rules should consider their superannuation arrangements before the property settles. Waiting until after settlement to investigate the rules could create unnecessary pressure, particularly if there are questions about eligibility or the amount that can be contributed. The timing should also be considered alongside the settlement of the replacement property, because selling the existing home and buying another property can involve significant cash-flow requirements.
How Much Can You Contribute?
An eligible individual can generally make a downsizer contribution of up to $300,000 from the proceeds of selling an eligible home. The ATO states that the maximum amount an individual can contribute from the sale of one home is the lesser of:
- $300,000, or
- the sale proceeds remaining after taking into account other downsizer contributions made by the individual or their spouse.
Importantly, multiple downsizer contributions can potentially be made from the sale of the same home, provided the total does not exceed the applicable maximum. For example, an eligible homeowner might contribute $150,000 shortly after settlement and another $150,000 later, provided the relevant conditions are met. A couple may also be able to contribute up to $300,000 each if both individuals meet the requirements.
Does a Downsizer Contribution Count Towards Your Normal Super Contribution Caps?
A qualifying downsizer contribution does not count towards your concessional or non-concessional contribution caps. This can make the downsizer rules particularly useful for people who may otherwise have limited opportunities to contribute a significant amount into super. However, once contributed, the money becomes part of your superannuation balance and the normal superannuation rules will apply. The contribution should therefore be considered as part of your broader retirement and superannuation strategy rather than in isolation.
Can Downsizer Contributions Help Build Retirement Wealth?
For homeowners who have substantial equity in their property, downsizer contributions can provide another way to structure retirement savings. Money held in the family home can provide security and reduce housing costs, but it does not generally produce investment income in the same way as assets held within superannuation.
Moving some surplus capital into super may allow the money to form part of a broader retirement investment strategy. However, contributing money to super also means the funds become subject to the superannuation rules.
The decision should therefore be considered as part of an overall retirement plan rather than simply as a tax strategy. The appropriate approach will depend on factors such as:
- Age
- Existing superannuation balances
- Pension arrangements
- Investment objectives
- Cash-flow requirements
- Estate planning
What Does This Have to Do with SMSFs?
Downsizer contributions can also be relevant to people who have a Self-Managed Super Fund (SMSF). An SMSF is a superannuation fund that members manage themselves. SMSFs are regulated by the Australian Taxation Office, rather than APRA. APRA’s own licensing guidance confirms that SMSFs are not RSEs and are instead regulated by the ATO.
This distinction is important. An SMSF trustee remains responsible for ensuring that contributions are correctly accepted and recorded and that the fund complies with superannuation legislation. The supplied material also highlights that SMSF trustees remain responsible for the fund’s investment strategy and compliance even where professional investment managers or other advisers are engaged.
SMSFs vs APRA-Regulated Super Funds
Most Australians have their superannuation with an APRA-regulated fund, such as an industry or retail super fund. APRA oversees registrable superannuation entities and their licensed trustees. APRA’s prudential framework includes requirements covering areas such as:
- Governance
- Investment governance
- Risk management
- Insurance
- Member outcomes
For example, APRA’s SPS 530 Investment Governance requires RSE licensees to maintain an investment governance framework, establish investment objectives and strategies, conduct due diligence and undertake stress testing. APRA’s SPS 510 Governance also establishes minimum governance requirements for RSE licensees and places ultimate responsibility for sound and prudent management with the board. These APRA requirements apply to APRA-regulated superannuation entities and should not be confused with the regulatory framework governing SMSFs.
Most industry and retail super funds are regulated by APRA, while SMSFs are regulated by the ATO. The key practical difference is that SMSF trustees take direct responsibility for the fund’s compliance, investment strategy and administration. For SMSF members, the ATO is the key regulator.
What Are the Risks of an SMSF?
Having greater control over superannuation can also mean greater responsibility. SMSF trustees are responsible for making sure the fund’s investment strategy is appropriate, keeping records, meeting reporting obligations and complying with the superannuation laws. SMSFs do not have the same protections available to members of APRA-regulated funds.
There are also ongoing costs, including:
- Accounting
- Administration
- Auditing
- Regulatory levies
- Investment advice
- Potentially legal and insurance expenses
This means an SMSF should not be established simply because a downsizer contribution is available. The decision to use an SMSF should be considered separately from the decision about whether a downsizer contribution is appropriate.
Can You Use a Downsizer Contribution More Than Once?
Generally, no. The downsizer rules contain a once-only requirement. The ATO states that an individual must not have previously made a downsizer contribution from the sale of any dwelling. This can include multiple partial disposals of an ownership interest in the same dwelling.
This makes it particularly important to understand the rules before making the contribution. A decision to make a downsizer contribution can have long-term consequences because the opportunity generally cannot simply be repeated when another property is sold in the future.
What About the Capital Gains Tax Rules?
The property must generally satisfy the relevant main residence requirements for the downsizer rules. The ATO’s eligibility guidance refers to both an ownership test and a main residence test. This is an important area where professional advice can be useful, particularly where a property has been:
- Used partly as an investment property
- Rented out for periods
- Inherited
- Jointly owned
- Subject to other ownership arrangements
Not every residential property transaction will automatically qualify.
Downsizer Contributions and Capital Gains Tax (CGT)
Selling a property may also create Capital Gains Tax considerations.The tax outcome will depend on the individual’s circumstances, including:
- How the property was used
- Whether it was used to produce income
- Ownership history
- The period the property was held
- Whether any exemptions or concessions apply
The downsizer contribution rules and Capital Gains Tax rules are separate considerations.Meeting the downsizer contribution requirements does not automatically mean there are no CGT implications. Understanding both areas before selling can help avoid unexpected tax outcomes.
Is Downsizing the Right Strategy for You?
Downsizing can be an effective retirement planning strategy for some Australians, but it is not suitable for everyone.The decision involves more than just the opportunity to contribute money into superannuation.Factors to consider may include:
- Future housing needs
- Lifestyle preferences
- Access to funds
- Retirement income requirements
- Superannuation position
- Tax implications
- Estate planning objectives
For some people, remaining in their current home may continue to be the preferred option. For others, selling the family home and contributing surplus funds into superannuation may better align with their retirement goals.
What Should You Consider Before Making a Downsizer Contribution?
Before selling your home, consider:
Your Eligibility
Make sure all downsizer contribution requirements are satisfied before proceeding.
Your Financial Position
Review:
- The expected sale proceeds
- Replacement property costs
- Selling expenses
- Available cash reserves
Your Superannuation Strategy
Consider how the contribution fits with:
- Your existing super balance
- Retirement income plans
- Investment strategy
Your Estate Planning
A significant contribution into superannuation may affect how your assets are structured and passed on in the future.
How Professional Advice Can Help
Downsizer contributions involve several rules and requirements that need careful consideration. Professional advice can help you understand:
- Whether you qualify
- How much you may be able to contribute
- How the contribution fits into your retirement strategy
- Potential tax considerations
- The impact on your broader financial position
Planning before selling your home can help ensure the decision supports your long-term retirement objectives.
Final Thoughts
Downsizer contributions provide eligible Australians with an opportunity to move some proceeds from the sale of their home into superannuation. For some homeowners, this can help strengthen retirement savings and provide greater flexibility. However, selling a home is a significant financial decision and should be considered carefully. The downsizer rules should be reviewed alongside:
- Retirement plans
- Superannuation strategy
- Tax considerations
- Investment objectives
- Estate planning arrangements
Understanding the requirements before selling can help ensure decisions are made with a clear understanding of the potential outcomes.
Frequently Asked Questions
What is a downsizer contribution?
A downsizer contribution allows eligible Australians to contribute some proceeds from selling their home into their superannuation fund.
How much can I contribute through downsizer rules?
Eligible individuals may be able to contribute up to $300,000 from the sale of an eligible home.
Can couples both make downsizer contributions?
Yes. If both individuals meet the eligibility requirements, each person may be able to contribute up to $300,000.
What age do I need to be to make a downsizer contribution?
You must generally be at least 55 years old when making the contribution and meet the other eligibility requirements.
Does a downsizer contribution count towards normal contribution caps?
No. A qualifying downsizer contribution does not count towards concessional or non-concessional contribution caps.
Can I make a downsizer contribution more than once?
Generally, no. The downsizer rules include a once-only requirement.
Can I make a downsizer contribution into an SMSF?
Yes, provided the SMSF accepts the contribution and all eligibility requirements are satisfied.
How Can We Help?
If you are considering selling your home and want to understand how downsizer contributions may apply to your retirement strategy, Camden Professionals can help review your options.
Our team can assist with:
- Retirement planning considerations
- Superannuation strategies
- Tax implications
- Wealth planning
- Financial structuring considerations
Contact Camden Professionals to discuss your circumstances.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Division 296 Tax Explained: What Australia’s New Super Tax Means for Balances Over $3 Million
For many Australians, superannuation has been one of the most effective long-term wealth-building structures due to its concessional tax treatment. However, from 1 July 2026, changes under Division 296 tax will reduce some of the tax advantages available to individuals with larger superannuation balances.
The introduction of Division 296 tax means individuals with superannuation balances above certain thresholds need to carefully consider how they structure their retirement savings, investments and future contributions. For the 2026–27 financial year, the first threshold is set at $3 million, with a second threshold applying at $10 million.
These thresholds will be indexed in future years.
What Is Division 296 Tax?
Division 296 is a new tax measure that applies an additional tax on earnings associated with superannuation balances above specified thresholds. The purpose of the measure is to reduce the tax concessions available to individuals with very large superannuation balances.
For the 2026–27 financial year:
- The first threshold is $3 million
- A second threshold applies at $10 million
- Thresholds will be indexed over time
The additional tax does not mean your entire superannuation balance is taxed at a higher rate once it exceeds the threshold.Instead, the tax applies only to the relevant proportion of earnings connected to the amount above the applicable threshold.
How Does Division 296 Tax Work?
Division 296 tax is calculated based on the proportion of your superannuation balance that exceeds the relevant threshold.It does not apply to your entire superannuation balance.For example, if your superannuation balance is slightly above $3 million, the additional tax applies only to the portion relating to the amount above the threshold.
The calculation considers:
- Your total superannuation balance
- The applicable threshold
- The earnings attributable to the excess amount
This means the impact can vary significantly between individuals depending on their balance, investment performance and circumstances.
Does Division 296 Tax Mean Super Is Taxed at 30%?
No. A common misunderstanding is that once your super balance exceeds $3 million, your entire superannuation balance will automatically be taxed at 30%.
This is not how Division 296 works. The additional tax applies only to the relevant proportion of earnings associated with the balance above the threshold. Your existing superannuation tax treatment continues to apply to the portion within the normal limits.
What Happens Above the $10 Million Threshold?
A higher threshold applies for individuals with very large superannuation balances.
For the 2026–27 financial year:
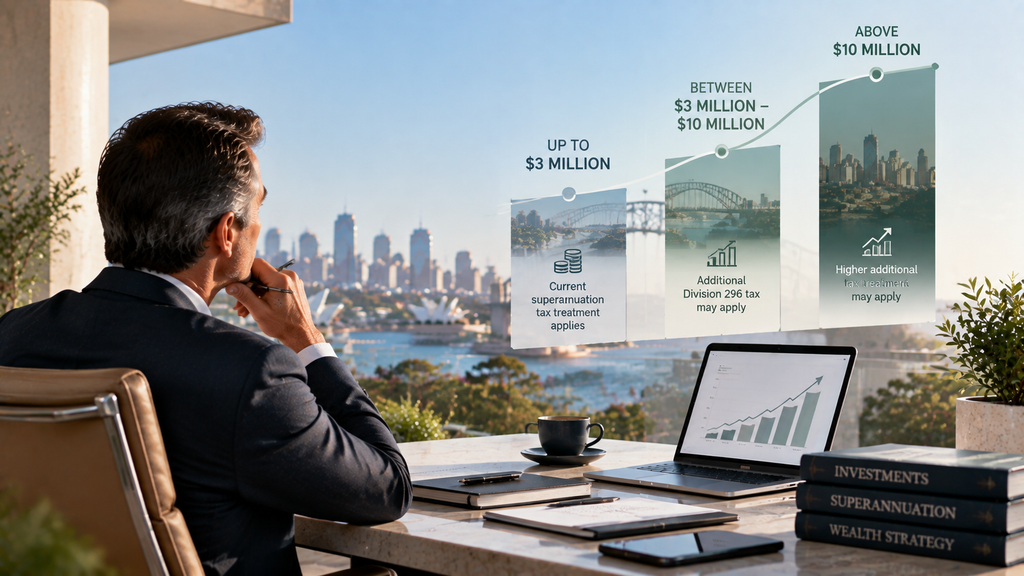
| Superannuation Balance | Additional Division 296 Treatment |
|---|---|
| Up to $3 million | Existing superannuation tax treatment applies |
| Between $3 million and $10 million | Additional Division 296 tax may apply |
| Above $10 million | Higher additional tax treatment may apply |
The purpose of the second threshold is to apply a higher level of taxation to extremely large superannuation balances.
How Are Earnings Calculated Under Division 296?
An important aspect of Division 296 is that the calculation is based on earnings determined under the legislation. The calculation considers changes in the value of superannuation interests and other relevant factors. For individuals with complex superannuation arrangements, including self-managed super funds (SMSFs), the calculation can become more complicated. Factors that may affect the outcome include:
- Investment income
- Capital gains
- Pension interests
- Changes in account balances
- Timing of contributions and withdrawals
Are Unrealised Gains Taxed Under Division 296?
The final Division 296 rules changed from earlier proposals. The calculation does not simply tax every unrealised increase in investment value. An increase in the value of an investment is not automatically taxed just because the market value has increased and the asset has not been sold. However, the calculation remains complex and depends on the specific circumstances of the individual.
Does Division 296 Mean Super Is No Longer Tax Effective?
No. Superannuation can still remain one of the most tax-effective investment structures available. Super continues to provide significant tax benefits, including:
- Concessional tax treatment in accumulation phase
- Potential tax-free earnings in eligible retirement-phase pensions
The introduction of Division 296 does not remove the benefits of superannuation. Instead, it changes the way individuals with very large balances need to think about future wealth accumulation.
Should You Stop Contributing to Super After Reaching $3 Million?
Not necessarily. Reaching the $3 million threshold does not automatically mean that superannuation is no longer suitable. The right strategy depends on factors such as:
- Your retirement goals
- Your investment strategy
- Your personal tax position
- Your access requirements
- Your estate planning objectives
For some individuals, continuing to use super may still provide significant advantages. For others, building wealth outside super may become an important consideration.
Superannuation vs Building Wealth Outside Super
As super balances grow, some individuals may consider whether future investments should remain inside super or be held through alternative structures.
Key considerations include:
| Consideration | Superannuation | Outside Super |
|---|---|---|
| Tax treatment | Generally concessional | Depends on structure |
| Access | Restricted until conditions of release are met | Generally greater flexibility |
| Investment options | Subject to super rules | Wider range of structures available |
| Estate planning | Specific superannuation rules apply | Depends on ownership structure |
The decision is not only about tax. Other factors, including access, flexibility and estate planning, should also be considered.
Could an Investment Company Be an Alternative?
For some individuals with significant wealth, an investment company may form part of a broader wealth strategy. An investment company may allow profits to remain within the company and be reinvested. This can be useful for individuals who:
- Are still accumulating wealth
- Do not require investment income personally each year
- Want greater control over investment capital
However, an investment company is not automatically better than super.
The structure has its own considerations, including:
- Corporate tax rates
- Administration costs
- Loss of some capital gains tax concessions
- Tax implications when extracting funds

Estate Planning Considerations
Division 296 discussions should not focus only on tax during your lifetime. Estate planning is also an important consideration for individuals with large superannuation balances. Superannuation does not automatically form part of your estate.
The outcome depends on:
- Beneficiary nominations
- Super fund rules
- Estate planning arrangements
Super Death Benefits Tax
The tax treatment of superannuation death benefits depends on who receives the benefit.
Generally:
- Payments to eligible dependants may receive concessional treatment.
- Payments to non-dependants, such as some adult children, may have different tax consequences.
For individuals with significant super balances, planning ahead can help manage potential tax outcomes for beneficiaries.
What Should High-Balance Super Members Do?
Individuals approaching or exceeding the $3 million threshold should review their overall wealth strategy. Important areas to consider include:
- Superannuation balance management
- Investment structure
- Contribution strategy
- Retirement planning
- Estate planning
The introduction of Division 296 does not mean immediate action is required for everyone. However, understanding the potential impact early can help create a more effective long-term strategy.
Final Thoughts
Division 296 tax represents a significant change for Australians with larger superannuation balances. However, it does not mean superannuation is no longer valuable. The key is understanding how the new rules interact with your personal circumstances and long-term goals. For some individuals, continuing to maximise superannuation benefits may remain the right approach. For others, combining super with investments held outside super may provide greater flexibility and control. A strategic review can help determine the most appropriate approach for your situation.
Frequently Asked Questions
Is super still tax effective after Division 296?
Yes. Superannuation can still provide significant tax advantages, even after Division 296 applies to larger balances.
Does Division 296 tax my entire super balance?
No. The additional tax applies only to the relevant proportion of earnings connected to amounts above the applicable threshold.
Does Division 296 apply from 1 July 2026?
Yes. The measure applies from the 2026–27 financial year.
Will everyone with more than $3 million in super pay Division 296 tax?
Not necessarily. The outcome depends on your balance, earnings and individual circumstances.
Should I move money out of super once I reach $3 million?
Not automatically. The decision depends on your retirement objectives, tax position, investment strategy and estate planning needs.
Is an investment company better than super?
Not always. An investment company may provide flexibility, but it also has different tax and administration considerations.
How Can We Help?
If your superannuation balance is approaching or exceeding $3 million, Camden Professionals can help review your current position and understand how the Division 296 changes may affect your broader wealth strategy. Professional advice can help you assess:
- Superannuation strategies
- Investment structures
- Retirement planning
- Estate planning considerations
Contact Camden Professionals to discuss your circumstances and explore your available options.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Why Your Super Insurance Might Not Cover What You Expect
Many Australians are surprised to learn they already have life insurance through their superannuation fund. In fact, millions of super accounts include some form of insurance cover, often without members actively choosing it.
While insurance inside super can be a cost-effective way to protect yourself and your family, it’s also one of the least understood aspects of retirement savings. Many people don’t know what type of cover they have, how much they’re insured for, what exclusions apply, or when their insurance could be cancelled.
Assuming your default insurance will always provide enough protection can be a costly mistake. Changes to superannuation laws, account inactivity rules and differences between funds mean your cover may not be as comprehensive as you think.
Before relying on the insurance attached to your super, it’s worth understanding how it works, when it may stop, and whether it still meets your financial needs.
What Insurance Is Available Through Superannuation?
Many Australian superannuation funds offer members insurance as part of their account.
Depending on the fund, this may include:
- Life insurance (Death Cover) – Pays a benefit if you die or are diagnosed with a terminal medical condition.
- Total and Permanent Disability (TPD) Insurance – Provides a benefit if illness or injury permanently prevents you from working, subject to the policy’s definitions.
- Income Protection Insurance – Replaces part of your income for a limited period if you’re temporarily unable to work due to illness or injury.
The amount and type of insurance available varies between super funds and is subject to each insurer’s terms, conditions and eligibility criteria.
Myth 1: “Everyone Automatically Gets Insurance Through Super”
Automatic Cover Is No Longer Guaranteed
A common misconception is that every superannuation member automatically receives insurance.
Since changes to Australian superannuation legislation, this is no longer the case.
Generally, insurance is not automatically provided if:
- You are under 25 years of age.
- Your account balance is less than $6,000.
- You have not elected to receive insurance.
Some exceptions apply, particularly for employees working in hazardous occupations where certain super funds provide automatic cover under specific arrangements. If you’re starting your first job or are early in your career, it’s worth checking whether you actually have any insurance at all.
Myth 2: “Default Cover Will Be Enough”
Default Insurance Is a Starting Point—Not a Personal Financial Plan
Insurance offered through super is designed to provide basic protection across a large group of members.It isn’t tailored to your personal financial situation.
Your current cover may be insufficient if you have:
- A mortgage.
- Young children.
- A partner who relies on your income.
- Investment loans.
- Business debts.
- Other financial commitments.
Many Australians require significantly more insurance than their default super policy provides.
Check for Exclusions and Premium Loadings
Not every policy provides the same level of protection.
It’s important to understand:
- Waiting periods.
- Benefit periods.
- Occupational exclusions.
- Medical exclusions.
- Pre-existing condition exclusions.
- Definitions used for disability claims.
Some members also pay premium loadings.
A premium loading is an increase above the standard insurance premium and may apply if you:
- Work in a high-risk occupation.
- Smoke or use tobacco products.
- Have certain medical conditions.
- Participate in hazardous activities.
If your occupation or smoking status has changed, you should review your policy to ensure you’re not paying higher premiums unnecessarily.
Myth 3: “My Insurance Will Move with Me If I Change Super Funds”
Changing Super Funds Can Cancel Your Insurance
Many Australians change super funds when changing jobs or consolidating their retirement savings. However, insurance usually does not automatically transfer with your super balance.
If you move to another fund:
- Your existing insurance may end.
- You may lose valuable cover.
- Replacing your policy could require new medical assessments.
- New premiums may be higher due to age or changes in health.
Some insurers allow policies to be converted into retail insurance outside super, but eligibility rules apply and premiums may increase.Before switching funds, always confirm what will happen to your existing insurance.
Myth 4: “If I Stop Contributing, Nothing Will Change”
Inactive Super Accounts Can Lose Insurance
Australian law requires most super funds to cancel insurance where an account has been inactive for 16 months or more.
An account is generally considered inactive if no contributions or rollovers have been received during that period. Your fund will usually attempt to contact you before insurance is cancelled. However, if your contact details are outdated, you may not receive these important notices. Insurance may also cease if:
- Your account balance becomes too low.
- Premiums can no longer be deducted.
- You exceed the policy’s maximum cover age.
Regularly checking your super account and keeping your contact details current can help prevent accidental loss of cover.
Myth 5: “More Super Accounts Mean More Insurance Protection”
Multiple Policies May Simply Mean Multiple Premiums
It’s common for Australians to accumulate several super accounts throughout their working lives. Each account may include separate insurance policies.
While this can sometimes provide additional protection, it can also result in:
- Paying multiple insurance premiums.
- Reduced retirement savings.
- Overlapping or unnecessary cover.
- Administrative complexity when making claims.
Insurance benefits are not always cumulative, and claim outcomes differ between policies. Before consolidating super accounts—or deciding to keep multiple accounts—review each policy carefully to determine whether the cover remains valuable.
Myth 6: “Insurance Through Super Is Always the Cheapest Option”
Lower Cost Doesn’t Always Mean Better Value
Because super funds purchase insurance for large groups of members, premiums are often competitive. However, cheaper premiums don’t necessarily provide better protection.
Important considerations include:
- Benefit amounts.
- Policy definitions.
- Waiting periods.
- Exclusions.
- Premium increases over time.
- Flexibility to adjust cover.
Retail insurance purchased outside super may offer broader cover or greater flexibility depending on your personal circumstances. The right choice depends on your financial goals, family situation and risk profile.
Why It’s Important to Review Your Super Insurance Regularly
Life changes and your insurance should change with it.
You should review your cover whenever you:
- Buy a home.
- Get married or enter a de facto relationship.
- Have children.
- Change jobs.
- Become self-employed.
- Take on significant debt.
- Receive an inheritance.
- Approach retirement.
A policy that suited you five years ago may no longer provide adequate protection today.
Questions to Ask When Reviewing Your Insurance
Before relying on your super insurance, consider asking:
- What type of insurance do I currently have?
- How much cover do I have?
- Is the cover sufficient for my family’s needs?
- What exclusions apply?
- Am I paying a premium loading?
- What happens if I change super funds?
- What happens if I stop working or stop contributing?
- Are there better options available?
Understanding the answers can help you make informed financial decisions.
How a Financial Adviser Can Help
Superannuation insurance can be complicated, particularly when balancing retirement savings with adequate personal protection.
A licensed financial adviser can help you:
- Review your current insurance.
- Identify gaps in your protection.
- Compare cover inside and outside super.
- Explain policy exclusions and definitions.
- Assess whether your level of cover remains appropriate.
- Coordinate insurance when consolidating super accounts.
Regular reviews ensure your insurance continues to align with your financial objectives and changing personal circumstances.
Conclusion
Insurance through superannuation provides valuable financial protection for millions of Australians, but it shouldn’t be treated as a “set and forget” benefit. Default cover is designed to provide a basic level of protection and may not reflect your income, debts, family responsibilities or long-term financial goals.
Changes to superannuation laws, account inactivity rules and differences between insurance policies mean your cover can reduce or even cease without you fully appreciating the consequences. Likewise, switching super funds or consolidating accounts without understanding the impact on your insurance could result in the loss of valuable protection. Taking the time to review your superannuation insurance, understand your policy’s terms and seek professional advice where appropriate can help ensure you and your family have the level of financial protection you expect when it matters most.
Frequently Asked Questions
Do all Australians automatically receive insurance through their super?
No. Under current legislation, most people under 25 or with a super balance below $6,000 do not automatically receive insurance unless they choose to opt in or qualify under specific exceptions.
What types of insurance are available through super?
Most super funds offer Life (Death) Cover, Total and Permanent Disability (TPD) Insurance and, in many cases, Income Protection Insurance.
Can I lose my insurance if I change super funds?
Yes. In many cases, insurance is linked to your membership with a particular super fund. Changing funds may result in your existing cover ending unless appropriate arrangements are made.
Can insurance be cancelled if I stop contributing to my super?
Yes. Most super funds are required to cancel insurance on inactive accounts after 16 months unless you instruct the fund to retain your cover, subject to legislative requirements.
Is insurance through super cheaper than buying it directly?
Often it is competitively priced because super funds purchase insurance in bulk. However, lower premiums don’t always mean the policy provides the most appropriate level of cover or features for your needs.
Why should I review my insurance regularly?
Major life events such as buying a home, starting a family, changing employment or approaching retirement can significantly affect your insurance needs. Regular reviews help ensure your cover remains appropriate.
Should I seek professional advice before changing super funds?
Yes. Before switching or consolidating super accounts, it’s important to understand how the change may affect your insurance and whether alternative cover is required.
Sources
- Australian Taxation Office (ATO)
- Australian Securities and Investments Commission (ASIC)
- Australian Prudential Regulation Authority (APRA)
- Services Australia
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Payday Super – What’s Changing from 1 July 2026
Significant superannuation changes in Australia are on the way. From 1 July 2026, the new Payday Super rules will fundamentally change how and when employers pay Super Guarantee (SG) contributions.
Instead of paying super quarterly, employers will need to pay super at the same time as wages. For businesses, payroll teams, and SMSF trustees, this represents one of the most important compliance shifts in recent years.
What Is Payday Super?
Payday Super requires employers to pay Super Guarantee contributions at the same time as salary and wages, rather than quarterly.
Under the new rules:
- Super must be received by the employee’s super fund within seven business days of payday
- Quarterly super payments will no longer apply
- The rule applies to all employers, including companies, sole traders, partnerships, and trusts
This is commonly referred to as the “payday plus 7 business days rule.”
Key Payday Super Requirements
From 1 July 2026:
- Super must be calculated at 12% of Qualifying Earnings (ordinary time earnings plus any salary sacrifice super)
- Contributions must reach the fund within seven business days of each pay run
- Super funds must allocate contributions to members within three business days of receipt or return them if they cannot be accepted
- SMSFs must have a valid Electronic Service Address (ESA) and be SuperStream compliant in order to receive employer contributions
The most critical compliance point is timing. It is not enough to process the payment. The contribution must be received by the fund within the required timeframe.
Why Timing Is Now a Major Risk
Under the new ATO Payday Super model, processing delays and rejected payments become far more serious.
This is particularly relevant for:
- Businesses paying weekly or fortnightly wages
- Employers running payroll close to weekends or public holidays
- Employees with incomplete or incorrect SMSF details
If a contribution is rejected, employers still only have the original seven-business-day window to correct and resubmit the payment. Missing that deadline may trigger the Super Guarantee Charge (SGC), daily interest, and penalties. The ATO has confirmed it will closely monitor superannuation contributions, especially related-party transactions, to prevent non-arm’s length arrangements.
How Payday Super Affects SMSFs
The changes will directly impact self-managed superannuation funds (SMSFs).
The ATO estimates approximately 366,000 individuals across 244,000 SMSFs will be affected, particularly where members receive contributions from unrelated employers.
Important points for SMSFs:
- SMSFs receiving contributions from related employers must comply with the new timing rules
- SuperStream electronic data requirements are not mandatory for related-party contributions
- SMSFs must maintain regulated status and lodge annual returns on time
If an SMSF annual return is overdue, the fund may lose its regulated status and become ineligible to receive employer contributions or rollovers.
For employers the key risk is administrative error. Incorrect bank details, missing ESA information, or member mismatches can cause rejected payments and late super.
Changes to SG Rates and Contribution Caps
Alongside Payday Super, there are broader Super Guarantee updates employers must understand.
- From 1 July 2025, the minimum SG rate increased to 12% of ordinary time earnings
- For 2025–26, the Maximum Contribution Base (MCB) is $62,500 per quarter
- From 1 July 2026, the MCB shifts to an annual limit of $250,000
- The maximum SG liability becomes $30,000 per employee per financial year
- SG applies to all employees aged 18 and over regardless of earnings
- Employees under 18 qualify if they work at least 30 hours per week
Employers should review payroll systems to ensure accurate SG calculations under the updated contribution caps.
Exceptions to SuperStream Requirements
SuperStream is not required:
- For sole traders paying their own super
- Where the employer and SMSF are related parties
However, the timing requirements still apply.
What Employers Should Do Now: Practical Payday Super Checklist
- Map Your Pay Cycles and Cash Flow
Payday Super shifts SG from a quarterly expense to a pay-run expense.
Actions:
- Forecast SG across weekly, fortnightly, and monthly cycles
- Review working capital requirements
- Budget for SG like PAYG withholding: routine and scheduled
- Review Payroll Software Readiness
Your payroll system must support frequent, compliant super payments.
Actions:
- Confirm your payroll software is Payday Super ready
- Ensure correct SG calculations on Qualifying Earnings
- Validate your super payment method is reliable and auditable
- Clean Up Employee Super Fund Data
This step is critical, especially for employees with SMSFs.
Employers must verify:
- Correct bank account details
- Valid Electronic Service Address (ESA)
- Accurate member identifiers
- That the SMSF is complying
A single data error can result in a rejected payment and late contribution risk.
- Create a Process for Payment Failures
Under Payday Super, issues must be identified and fixed quickly.
Actions:
- Set payroll alerts for failed super transactions
- Assign responsibility to resolve errors within 24 to 48 hours
- Maintain clear documentation of payment attempts and corrections
- Update Employment Contracts and Policies
If contracts refer to quarterly super payments, they should be updated to reflect the new payday model.
- Engage Experienced Advisors
The biggest risk for many employers is not understanding the rule, but implementing it incorrectly.
Working with an SMSF accountant, payroll specialist, or superannuation advisor can help you:
- Confirm correct SG calculations
- Establish compliant workflows
- Reduce rejected contributions
- Support employees with SMSF reporting requirements
How Payday Super Affects Employees with SMSFs
Employers do not need to treat SMSFs differently in principle, but SMSFs are more sensitive to administrative errors.
Common issues include:
- Incorrect SMSF bank details
- Missing electronic service information
- Member name or TFN mismatches
- Contributions sent to non-complying SMSFs
If you employ staff with SMSFs, consider conducting an annual SMSF detail verification before 1 July 2026.
The Closure of SBSCH
With the Small Business Superannuation Clearing House closing from 1 July 2026, employers must reassess how they process super payments and ensure systems align with the new Payday Super framework.
Conclusion
The introduction of Payday Super from 1 July 2026 marks a major compliance shift in Australian superannuation. Employers must ensure that Super Guarantee contributions are paid on payday and received by the fund within seven business days.
Businesses that prepare early will manage this transition smoothly. That means upgrading payroll systems, cleaning employee super data, adjusting cash flow planning, and building processes to manage payment exceptions.
For employers with staff in self-managed super funds, preparation is even more critical. Administrative accuracy will be the difference between seamless compliance and costly Super Guarantee penalties.
If you want clarity on how the Payday Super changes affect your business, now is the time to review your systems and seek professional advice before the 2026 deadline.
Facts Sheets
- Fact Sheet 1 – Pay Day Super Employers Key Changes
- Fact Sheet 2 – Qualifying Earnings
- Fact Sheet 3 – SuperStream
- Fact Sheet 4 – Employer Checklist
- Fact Sheet 5 – Small Business Super Clearing House
Source: ATO
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Super tax update – Proposed changes to Division 296
The Federal Government has responded to industry feedback on its proposed new tax for superannuation balances exceeding $3 million, announcing several significant adjustments aimed at making the measure fairer and more practical.*
*Note: However, the proposal is not yet legislated, and further consultation with industry stakeholders is expected before it is introduced to parliament. If passed by parliament, the measure will begin from July 2026.On 13 October 2025, Treasurer Jim Chalmers provided a long-awaited announcement regarding the status of the proposed Division 296 tax on superannuation balances exceeding $3 million, confirming it would proceed effective 1 July 2026 but with some significant changes to the methodology and thresholds – such as the exclusion of unrealised capital gains from the tax.
While the revised proposal is arguably more positive for most individuals than the previously announced versions, this change in approach means many people with large or growing superannuation balances will need to take yet another turn on the road to planning the most suitable structures in which to hold their wealth
Under the revised proposal:
- Indexation of the cap – the $3 million threshold will be indexed to CPI, increasing in $150,000 increments to reflect inflation
- Tiered tax rates – earnings on super balances between $3 million and $10 million will attract a 30 per cent tax, while balances above $10 million will face a 40 per cent rate on the proportion above that amount. The $10 million cap will be indexed in $500,000 increments
- Removal of tax on unrealised gains – importantly, the government has dropped the contentious plan to tax unrealised earnings, opting instead to tax actual income, aligning the proposal with established Australian tax principles
- Deferred commencement – the measure will now start from 1 July 2026, with the first notices of assessment expected in the 2027–28 financial year.
Treasury example
To illustrate how the changes will work in practice, Treasury provided the following example:
Megan, aged 58, has a total superannuation balance of $4.5 million, with $2.3 million in an APRA-regulated fund and $2.2 million in an SMSF.
In the 2026–27 financial year, she earns $300,000 in realised income ($100,000 from her APRA fund and $200,000 from her SMSF).
The proportion of her balance above the $3 million threshold is 33.33 per cent, with no portion above $10 million. Her additional tax under the proposed Better Targeted Superannuation Concessions (BTSC) measure would therefore be: $15,000 = 0.15 × 0.3333 × $300,000
What does this mean for super fund members?
The proposed tax increase was announced more than two years ago and was meant to be in effect from July 2025. However, it was met with criticism, and the bill was never introduced to parliament.
The revised proposal represents a positive shift, particularly the removal of the unrealised gains component, which was a major concern for many investors and advisers.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
SMSF Management: What Trustees Can and Can’t Charge Fees For
Self-managed super funds (SMSFs) provide individuals with greater control and flexibility over their retirement savings, allowing them to make investment decisions and manage certain aspects of their fund operations. However, this autonomy comes with complexities, especially when it comes to determining which activities trustees can charge fees for, particularly when it involves related-party transactions or “mates rates.” Understanding the boundaries between trustee duties and professional services is essential to avoid compliance issues, particularly those surrounding non-arm’s length expenditure (NALE) and income (NALI) rules.
What Are SMSF Trustee Duties?
As a trustee of an SMSF, your primary responsibility is to ensure that the fund is managed in accordance with the Superannuation Industry (Supervision) Act 1993 (SIS Act) and other relevant regulations. Trustee duties include:
- Managing Investments: Trustees are responsible for overseeing the SMSF’s investment strategy, including decisions on asset allocation. This is a core trustee duty and cannot be charged as a fee.
- Record-Keeping: Proper documentation, including financial records, meeting minutes, and tax returns, must be maintained. Managing these tasks yourself is part of your obligations and cannot be billed to the SMSF.
- Fund Administration: Tasks such as ensuring regulatory compliance, organising meetings, and lodging annual returns are part of the trustee role and cannot attract a fee.
- Lodging Reports and Returns: Trustees must file an annual return for the fund, which includes income tax reporting and compliance details. While you can handle this on your own, many trustees choose to hire an accountant or professional SMSF administrator.
What SMSF Trustees Can Charge a Fee For
While trustees cannot charge for performing basic duties, there are specific situations in which fees may be charged for services beyond standard trustee obligations:
- Professional Services: If you are a qualified professional (e.g., accountant, financial planner, or lawyer), you may charge fees for providing professional services to the SMSF. This includes preparing financial statements, providing legal advice, or managing complex investment transactions. However, these services must be provided at commercial rates and in line with industry standards to avoid triggering non-arm’s length income (NALI) rules.
- Specialist Tasks: Trustees may outsource specialist services, such as investment management or legal work, and the providers of these services can charge for their services. These transactions must be conducted at arm’s length, with proper documentation in place to ensure compliance.
What SMSF Trustees Cannot Charge For
Trustees are prohibited from charging for tasks that fall under their core duties, including:
- General Fund Administration: Tasks like paying bills, organising meetings, and maintaining records cannot be billed to the SMSF.
- Management of Fund Investments: While trustees make investment decisions, they cannot charge for their time or expertise in managing the fund’s investments.
- Compliance Monitoring: Ensuring the fund remains compliant with regulations is a fundamental trustee responsibility and cannot be monetized.
- Day-to-Day Operations: Regular administrative tasks associated with managing the SMSF must be performed without remuneration.
The Risks of Non-Arm’s Length Expenditure (NALE)
Non-arm’s length expenditure (NALE) and income (NALI) rules are in place to prevent trustees from gaining an unfair tax advantage through discounted or subsidized transactions. If trustees provide services to the SMSF at below-market rates or offer “mates rates,” they risk triggering these rules.
If an SMSF is found to have incurred NALE, the income generated from that expenditure will be taxed at the highest marginal rate (45%) rather than the concessional tax rates that apply to superannuation funds. This can result in significant financial penalties and undermine the value of the fund.
How to Avoid NALE Breaches
- Market Rate for Services: If providing professional services, ensure that the fees are consistent with what you would charge any other client.
- Documentation: Always keep thorough records, including service agreements and invoices, that demonstrate the terms of your services are in line with industry standards.
- Seek Professional Advice: When in doubt, consult SMSF specialists or financial advisors to ensure your fund remains compliant with the relevant rules.
Conclusion
Managing an SMSF offers significant control over your retirement savings, but it also comes with important responsibilities. Trustees must carefully distinguish between their duties as trustees and the provision of professional services. Charging fees for tasks that are part of trustee obligations or offering discounted services can result in non-arm’s length penalties, which could have a significant financial impact on the fund. By following the arm’s-length principles and seeking professional advice when necessary, trustees can effectively manage their SMSF while ensuring compliance with all regulations. This approach will help protect your retirement savings and avoid costly mistakes.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How to Increase Your Superannuation: Top Tips for Growing Your Retirement Savings
Superannuation (super) is one of the most crucial aspects of your financial planning for retirement in Australia. However, many people find that their superannuation savings fall short of what they need for a comfortable retirement. The good news is that there are several ways you can boost your superannuation and make the most of this vital long-term savings tool. Whether you’re just starting out in your career or nearing retirement, it’s never too early (or too late) to take action to increase your super.
Why Increasing Your Superannuation Matters
The Australian government requires employers to pay a percentage of your income into a superannuation fund, known as the Superannuation Guarantee (SG). As of 2025, the SG rate will rise to 12%. However, this contribution may not be enough to fund your desired lifestyle in retirement. The more you can contribute to your super and the earlier you start, the better your chances of achieving financial security once you stop working.
Here are some strategies to increase your superannuation and grow your retirement savings:
- Make Voluntary Contributions
There are two primary ways to make additional contributions to your superannuation:
- Concessional Contributions (Before-tax Contributions):
These contributions are made before tax is applied, reducing your taxable income and providing potential tax benefits. Concessional contributions include your employer’s SG payments, salary sacrifice arrangements, and personal contributions for which you claim a tax deduction. In the 2024-25 financial year, the concessional contribution cap is $30,000 per year (including employer SG payments). - Non-Concessional Contributions (After-tax Contributions):
These are voluntary contributions made after tax has been paid on your income. You won’t get a tax deduction for these contributions, but the upside is that they aren’t taxed when they’re added to your super. The non-concessional contribution cap is $120,000 per year (or up to $360,000 over three years if you’re under 67).
- Salary Sacrifice
Salary sacrificing is one of the most popular ways to increase your superannuation. With salary sacrificing, you agree to have part of your pre-tax salary paid directly into your superannuation fund. This reduces your taxable income, potentially lowering your overall tax liability while boosting your retirement savings. The contributions are taxed at 15%, which is often lower than your marginal tax rate, making it a tax-effective way to save for the future.
- Consolidate Your Superannuation Funds
Many Australians have multiple superannuation accounts, which can lead to paying multiple sets of fees and underperforming investments. Consolidating your super accounts into one fund can reduce fees and simplify your financial management. Before consolidating, ensure that you check for any exit fees and that your super fund offers the best possible investment options for your retirement goals.
- Review Your Investment Strategy
The way your super is invested plays a key role in growing your retirement savings. Superannuation funds typically offer a range of investment options, from conservative to high-growth portfolios. If you’re young and have a long time before retirement, you may want to take a more aggressive approach with a higher allocation to growth assets like shares. If you’re closer to retirement, you may want to adopt a more conservative strategy to protect your savings.
It’s essential to regularly review your investment strategy to ensure that it aligns with your risk tolerance, investment time horizon, and retirement goals. Super funds typically provide annual reports on how their investment options are performing, so take the time to review this information and adjust your investments accordingly.
- Take Advantage of Government Co-Contributions
If you are a low or middle-income earner, the government may help boost your super contributions through a co-contribution scheme. If you make a personal after-tax contribution to your super fund, the government will match a portion of that contribution, up to a certain limit, based on your income.
For example, if you earn less than $45,400 per year, the government may contribute up to $500 in matching co-contributions for every $1,000 you contribute to your super. The co-contribution amount gradually decreases as your income increases and phases out completely for individuals earning over $60,400 per year.
- Make Spouse Contributions
If your spouse earns a low income (under $40,000), you can contribute to their superannuation on their behalf. This can help boost their retirement savings while potentially earning you a tax offset. For the 2024-25 financial year, you could receive a tax offset of up to $540 for making spouse contributions, provided your spouse meets the eligibility criteria.
- Consider a One-Off Lump Sum Contribution
If you receive a financial windfall, such as a tax refund, a bonus, or an inheritance, consider making a lump sum contribution to your super. This can give your super balance a significant boost in a single transaction. Keep in mind the annual contribution caps when making a lump sum contribution to avoid excess contributions tax.
- Delay Your Retirement
If you are approaching retirement but are still a few years away, delaying your retirement can have a major impact on your superannuation balance. By continuing to work for a few more years, you will keep contributing to your super and allow your savings to grow further. Additionally, delaying retirement means you can potentially benefit from compound growth on your super over a longer period.
Top Tips for Increasing Your Superannuation
- Start Early: The earlier you start contributing to your super, the more time your money has to grow thanks to compound interest. Even small additional contributions can make a big difference over time.
- Make Contributions Regularly: Set up automated contributions to ensure you consistently add to your super, rather than waiting for a large lump sum or an occasional windfall.
- Review Your Super Fund: Compare fees and performance across different super funds to ensure your savings are working hard for you. Choosing a fund with low fees and good investment performance can significantly impact your super balance.
- Take Advantage of Tax Benefits: Use salary sacrifice, government co-contributions, and other tax-effective strategies to maximize your super while minimizing tax.
- Consider Professional Advice: A financial advisor can help you choose the best strategy for your superannuation based on your individual circumstances and retirement goals.
Conclusion
Boosting your superannuation is one of the most effective ways to secure a comfortable retirement. Whether you’re in the early stages of your career or approaching retirement, there are many strategies you can use to grow your superannuation balance. By making additional contributions, consolidating funds, reviewing your investment strategy, and taking advantage of government incentives, you can ensure that you’re on track to achieve your retirement goals. Remember, the earlier you take action, the more time your super has to grow—so start planning today for a brighter financial future tomorrow.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Salary Sacrificing into Super: How It Works
Salary sacrificing into superannuation involves directing a portion of your pre-tax income into your super fund. This can help you boost your retirement savings while potentially reducing your tax liability. If you’re considering this strategy, here’s a guide to understand how it works and what you need to know.
What is Salary Sacrificing into Super?
Salary sacrificing into super means you agree to have part of your before-tax income paid directly into your superannuation account by your employer. This contribution is in addition to the compulsory Super Guarantee contributions your employer must make, which are currently at least 11.5% of your earnings (assuming you’re eligible).
While salary sacrificing reduces your take-home pay, it can be a valuable tool for building your retirement savings. Additionally, salary sacrifice contributions are taxed at a lower rate, which may help reduce your overall tax bill.
How Much Super Do You Need?
According to the Association of Superannuation Funds of Australia (ASFA), to fund a comfortable retirement, individuals aged around 65 would need an annual budget of approximately $51,630, while couples would need $72,663 (assuming they own their own home). For a modest lifestyle, which is considered better than living solely on the Age Pension, individuals would need around $32,915, and couples would need $47,387 annually.
Contribution Limits
You can choose how much you want to contribute to your super via salary sacrifice, provided you don’t exceed the concessional contribution caps. The concessional contributions cap is set at $30,000 per year for individuals under 50, or $35,000 if you’re 50 or older.
Remember, the cap includes all concessional contributions, not just those made through salary sacrifice. This means the following contributions count toward the cap:
- Employer-paid Super Guarantee contributions.
- Any personal contributions you make and claim a tax deduction for (e.g., after-tax contributions you choose to deduct in your tax return).
Exceeding the cap can result in extra tax penalties, so it’s important to monitor your contributions closely.
Tax Benefits of Salary Sacrifice
One of the main advantages of salary sacrificing into super is the potential for tax savings. Contributions made via salary sacrifice are taxed at just 15%, significantly lower than most people’s marginal income tax rate. However, if you earn over $250,000, you will pay a higher tax rate of 30% on salary sacrifice contributions.
Additionally, the investment earnings inside your super fund are taxed at a concessional rate of 15%, which can help boost your retirement savings over time. These tax savings can accumulate, potentially benefiting you when you eventually access your super in retirement.
Is Salary Sacrificing Right for You?
To set up a salary sacrifice arrangement, you need to confirm with your employer that they offer this option. If salary sacrifice is not available at your workplace, you may still be able to claim a tax deduction for after-tax contributions you make to your super.
When deciding how much to salary sacrifice, consider:
- How much extra you can afford to contribute without affecting your essential living expenses.
- Whether salary sacrificing on an ongoing basis or making lump-sum contributions is more suitable for your financial situation.
- You can’t salary sacrifice on income that has already been paid, such as bonuses or leave entitlements, so plan ahead if you want to sacrifice those amounts.
Set Up the Arrangement with Your Employer
Once you decide how much to contribute, inform your payroll department to set up the arrangement. Be sure to get confirmation in writing when your salary sacrifice contributions will start being paid into your super account.
Monitor Your Contributions
It’s essential to ensure you don’t exceed the concessional contributions cap, as doing so can trigger additional taxes and penalties. The cap applies across all super accounts you may have, so if you hold multiple accounts, keep track of total contributions to avoid breaching the limit.
You may also be eligible to carry forward any unused portion of the concessional contributions cap from previous years (since July 1, 2018) if your total super balance is under $500,000. You can check your available cap space on the myGov website.
Other Things to Keep in Mind
- Investment Risks: The value of your super can fluctuate depending on the performance of your investments. Before making extra contributions, make sure you understand the risks associated with your super fund’s investment options.
- Accessing Your Super: Generally, you can access your super when you reach your preservation age (between 55 and 60, depending on your birth year) and retire.
Other Ways to Boost Your Super
- Tax-Deductible Contributions. You can make voluntary contributions to your super using after-tax dollars and claim a tax deduction for them when you file your tax return. This can be useful if you earn extra income or sell an asset that triggers capital gains tax, as contributing the proceeds to super could reduce your taxable income and help offset the capital gains tax.
- Government Co-Contributions. If you’re a low or middle-income earner and make an after-tax contribution to your super, the government may match your contribution with a co-contribution of up to $500. For the 2024-25 financial year, if you earn under $60,400 and make a voluntary contribution, you’ll be eligible for the maximum co-contribution of $500.
- Spouse Contributions. If your partner earns less than you, you may consider making spouse contributions. You can claim an 18% tax offset on contributions of up to $3,000, which can help boost your partner’s super balance while reducing your taxable income.
- Downsizer Contributions. If you’re 55 or older and sell your home, you may be able to make a voluntary contribution of up to $300,000 (or $600,000 for couples) to your super from the sale proceeds, regardless of your work status, super balance, or contribution history.
Review Your Super Regularly
It’s important to review your super at least once a year to ensure it’s working effectively for your retirement goals. Key things to review include:
- Fund performance (past performance is not a guarantee of future returns).
- Any fees you’re paying.
- Insurance coverage inside your super and whether it meets your needs.
- Your investment choices, which should align with your risk tolerance and time horizon.
By staying on top of your super, you can make sure it’s growing in the right direction and set yourself up for a comfortable retirement.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Changes to Payday Super Are Coming: What You Need to Know
The Australian government has introduced significant reforms to how superannuation is paid to employees, with a key change being the shift towards payday superannuation. Under the new rules, employers will be required to pay superannuation contributions to employees’ super funds on the same day that wages are paid, rather than on a quarterly basis. This change will affect businesses of all sizes, and it’s essential that employers understand the new obligations to remain compliant and avoid penalties.
What is Payday Super?
The concept of payday super means that employers will need to pay super contributions each time an employee is paid, whether that’s weekly, fortnightly, or monthly. Previously, employers were only required to make super contributions on a quarterly basis, typically by the 28th of each month following the end of a quarter (e.g., by 28th October for the July–September quarter).
From 1 July 2026, all employers will be required to pay super contributions in line with each payroll cycle. This means that employees will see their super paid into their fund more regularly, which can improve their retirement savings due to more frequent compounding of contributions.
Why is This Change Happening?
The shift to payday super is part of a broader initiative by the Australian government to ensure that superannuation is paid in a more timely and transparent manner. The goal is to address a longstanding issue of unpaid superannuation, which is estimated to cost employees billions of dollars in lost retirement savings each year. By aligning super payments with each payday, employees will be better able to track their super contributions and ensure they are receiving the correct amount.
Key Dates and Timeline
The full rollout of payday super will occur in stages:
- 1 July 2026: All employers must comply with the new payday super rules, meaning they will need to pay superannuation on the same day as employee wages.
However, the government is encouraging employers to begin implementing this change sooner, particularly large employers, who may need more time to update their payroll systems and processes.
What Employers Need to Do
To comply with the new payday super rules, employers will need to:
- Update Payroll Systems
Employers will need to ensure their payroll systems can handle superannuation payments on a more frequent basis. This may involve updating software or working with third-party payroll providers to automate the process. Many payroll systems will need to be modified to accommodate the new requirement, so it’s essential to consult with your software provider ahead of time. - Ensure Timely Superannuation Contributions
Employers must make sure that super contributions are paid on the same day as employee wages. For businesses with a weekly or fortnightly payroll cycle, this could mean more frequent payment of super, which will require careful cash flow management to ensure funds are available when needed. - Review Superannuation Obligations
Ensure that your superannuation contributions are meeting the required minimum percentage. As of 1 July 2023, the Superannuation Guarantee (SG) rate is 11% of an employee’s ordinary time earnings. Keep an eye on changes to the SG rate, as the government has announced gradual increases in the future. Failure to meet the minimum SG requirement could lead to penalties, including the Superannuation Guarantee Charge (SGC). - Communicate with Employees
Employers should communicate the changes to employees and provide information on how their superannuation will be paid under the new system. Employees may have questions about when they can expect to see their super contributions in their accounts and how the changes will impact their overall super balances. - Monitor for Compliance
Regularly check that all super contributions are being made correctly and on time. Late payments could result in additional fines and penalties. Under the new system, employees will have better visibility of their super contributions, making it easier for them to spot any discrepancies and hold employers accountable.
Benefits of Payday Super for Employees
The move to payday super has several key advantages for employees:
- More Frequent Contributions: With superannuation paid on each payday, employees will see their super balance grow more quickly due to the power of compound interest. Even small amounts can have a significant impact over time, especially when interest is calculated more regularly.
- Improved Transparency: Employees will have clearer visibility of their superannuation contributions, allowing them to track payments more easily. This can reduce the risk of unpaid super and help ensure that employees receive the correct amount.
- Better Cash Flow: For employees, payday super can provide a more accurate representation of their overall income and savings, as the super contributions will be more in sync with the money they are receiving.
Potential Challenges for Employers
While payday super has benefits for employees, it may pose some challenges for employers:
- Cash Flow Management: More frequent superannuation payments may put a strain on cash flow for some businesses, especially small businesses or those that operate on tight margins. Employers will need to plan ahead to ensure they can cover the superannuation contributions at the same time as wages.
- Administrative Burden: Payroll departments or payroll service providers will need to update their systems to accommodate the new rules, which could require time, effort, and resources. Employers may need to invest in new technology or training to ensure compliance.
- Increased Complexity: Employers who manage multiple payroll cycles (e.g., weekly, fortnightly, or monthly) will need to stay on top of the various payment dates to ensure compliance with the new payday super rules. This may increase administrative work and the potential for errors.
What Employers Should Do Now
While the full implementation of payday super is still a couple of years away, there are some key steps employers can take now to prepare:
- Assess Your Payroll System: Review your current payroll system to see if it can accommodate the new payday super requirements. If not, start researching updates or alternative systems that can handle more frequent super contributions.
- Plan for Cash Flow Adjustments: Start considering how more frequent superannuation payments might affect your cash flow. It may be necessary to adjust how you allocate funds for super payments to ensure there’s enough liquidity to meet obligations on time.
- Stay Informed About Legislation: Keep up to date with any changes to superannuation legislation, including any amendments or updates to the minimum contribution rate, timelines, or reporting requirements. Regularly check with the Australian Taxation Office (ATO) for the latest updates.
- Communicate with Your Employees: Keep your employees informed about the upcoming changes, and make sure they understand how the changes will affect their super contributions and balances.
Conclusion
The transition to payday super is a significant reform designed to ensure that superannuation is paid in a timely manner, helping employees save more for their retirement. While the change is still a few years away, it’s essential that employers start preparing now by reviewing their payroll systems, planning for potential cash flow challenges, and staying informed about the evolving regulations.
By proactively adjusting to these changes, businesses can ensure they remain compliant and avoid penalties, while also helping their employees build a stronger financial future.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.