




Setting Up an SMSF: What You Need to Know Before You Start
Thinking about setting up a Self-Managed Super Fund (SMSF)? An SMSF can give you greater control over how your retirement savings are invested, but it also comes with significant responsibilities.
Unlike an APRA-regulated super fund, where a professional trustee is responsible for managing the fund, an SMSF puts those responsibilities largely in the hands of its trustees. That means choosing an SMSF is not simply about investment choice. You need to consider the costs, administration, investment strategy, compliance requirements and whether managing your own super is appropriate for your circumstances.
What Is an SMSF?
A Self-Managed Super Fund is a private superannuation fund established for a small number of members. The members are generally also trustees, or directors of a corporate trustee.
- The key difference is control. SMSF trustees are responsible for making investment decisions and ensuring the fund complies with superannuation and tax laws.
- The ATO requires an SMSF to have an investment strategy before it starts investing. The strategy must reflect the purpose and circumstances of the fund and its members and must be reviewed regularly.
- This makes an SMSF quite different from simply selecting an investment option within an existing super fund.
Is an SMSF Right for You?
Before establishing an SMSF, consider why you want one. An SMSF may appeal to people who want greater control over their investments, have more complex investment needs or want to manage a broader range of assets within the superannuation rules. However, control also means responsibility.
As an SMSF trustee, you are responsible for ensuring investments comply with the law, maintaining records, preparing reports, arranging an annual audit and ensuring the fund’s investment strategy remains appropriate. The ATO makes it clear that trustees remain responsible for the fund’s investments even when professional advisers are used.
1. Look at the Investment Options
One of the main reasons people consider an SMSF is investment flexibility. Depending on the fund’s investment strategy and the superannuation rules, an SMSF can invest in assets such as shares, managed investments, term deposits and property. But greater choice does not mean every investment is permitted.
The ATO states that SMSF investments must be permitted under the fund’s trust deed and superannuation law, have clear legal ownership, be made on a commercial arm’s-length basis and satisfy the sole purpose test. There are also restrictions around transactions involving members and related parties. For example, the ATO states that, subject to limited exceptions, an SMSF generally cannot acquire assets from members or related parties, provide financial assistance to members or related parties, or use fund assets to provide a present-day benefit. Before investing, make sure you understand both the opportunity and the restrictions.
2. Have a Clear SMSF Investment Strategy
The ATO says an SMSF investment strategy should consider matters including:
- Diversification
- Investment risk and likely returns
- Liquidity
- The fund’s ability to meet expenses and retirement benefits
- The circumstances and needs of members
- Members’ retirement timeframes and risk appetite
Your investment strategy should be in writing and reviewed regularly. This is important because an SMSF should not be established simply to buy a particular asset. The investment strategy needs to explain how the fund’s investments relate to the retirement objectives of its members. This is important because where an SMSF is established with a particular investment in mind, trustees still need to consider whether that investment is appropriate having regard to the fund’s overall investment strategy and the circumstances of its members.
3. Compare SMSF Costs
Running an SMSF involves ongoing costs.
These can include:
- Establishment costs
- Accounting and tax return preparation
- Annual audit fees
- ATO supervisory levy
- Administration costs
- Investment advice
- Legal costs
- Brokerage and investment expenses
- Insurance where appropriate
The important question is not simply how much an SMSF costs each year. It is whether the benefits, flexibility and control justify those costs for your circumstances. For some people, the costs and administration of an SMSF may outweigh the benefits. For others, particularly those with more complex investment requirements, the additional control may be an important consideration.
4. Consider Your Investment Performance
Investment performance should be considered carefully, but it should not be the only reason for choosing an SMSF. Past performance does not guarantee future returns. If you are comparing an existing APRA-regulated super product with the potential benefits of an SMSF, make sure you are comparing like with like. Consider:
- Investment returns
- Investment risk
- Fees and expenses
- Diversification
- Liquidity
- Asset allocation
- Your investment timeframe
APRA conducts an annual performance test for certain APRA-regulated superannuation products. The test is designed to improve transparency and hold trustees accountable for underperformance. APRA also publishes broader product performance information covering investment returns, fees and performance-test outcomes. These resources can provide useful information when comparing an existing super fund with other APRA-regulated options.
5. Don’t Forget Insurance
Insurance is another issue to consider when deciding whether to establish an SMSF. Some super funds provide members with insurance options such as:
- Life insurance
- Total and permanent disability cover
- Income protection
If you move from an existing fund to an SMSF, you should check what insurance arrangements you currently have and whether transferring or replacing that cover could affect you. Insurance should be considered separately from the investment decision because losing existing cover can have important consequences.
6. Understand the SMSF Trustee Responsibilities
Perhaps the biggest difference between an SMSF and an APRA-regulated super fund is the level of responsibility placed on the trustee. SMSF trustees need to ensure the fund:
- Complies with superannuation legislation
- Maintains appropriate records
- Has and follows an investment strategy
- Meets tax and reporting obligations
- Arranges an annual independent audit
- Makes investments on an arm’s-length basis
- Complies with contribution and payment rules
The ATO also warns SMSF trustees about investment schemes that promise unusually high returns.Trustees need to understand what they are investing in and ensure every investment decision is consistent with the fund’s purpose and legal requirements.
7. Think About Property and Other Complex Investments
The Australian Taxation Office (ATO) has strict rules governing when a self-managed super fund (SMSF) can invest in property. Generally, the property must be acquired for the sole purpose of providing retirement benefits to fund members, rather than for personal use or benefit. An SMSF generally cannot acquire residential property from a member or related party, and residential property owned by the SMSF cannot be used by members or their relatives.
Different rules can apply to eligible business real property, including commercial property used in a business. Any property investment must also be consistent with the fund’s investment strategy and comply with the relevant superannuation rules. Recent changes have also affected the ability of SMSFs to borrow to purchase residential property.
From 10 August 2026, SMSFs are generally no longer able to enter into new limited recourse borrowing arrangements (LRBAs) to acquire residential property. Existing arrangements entered into before the change may be protected under transitional rules.
Importantly, the restriction does not extend to eligible commercial property, so SMSFs may still be able to use an LRBA to acquire business or commercial property where the relevant superannuation and borrowing rules are satisfied.
For anyone considering establishing an SMSF specifically to purchase property, it is important to understand these rules before setting up the fund or entering into a purchase contract. Professional advice should be obtained to ensure the proposed investment and funding arrangement comply with the relevant superannuation and tax requirements.
8. SMSF or APRA-Regulated Super Fund?
The decision does not have to be based simply on investment choice. An APRA-regulated super fund generally provides professional trustee oversight, investment options and administration without requiring the member to manage the fund’s compliance themselves. An SMSF provides greater direct control but places considerably more responsibility on the trustees. The right structure depends on your objectives, investment preferences, circumstances, costs and willingness to take on the responsibilities of being an SMSF trustee.
Final Thoughts
Choosing an SMSF is a significant financial decision. The attraction is usually greater control and flexibility, but those benefits come with additional administration, costs and legal responsibilities. Before establishing an SMSF, consider your investment objectives, the types of assets you want to invest in, the likely costs, insurance arrangements and the time and expertise required to manage the fund. The ATO provides detailed guidance on establishing and running an SMSF, including investment strategies and investment restrictions.
APRA also publishes performance information that can help consumers understand how APRA-regulated superannuation products are performing.An SMSF should be established because it is appropriate for your overall retirement strategy, rather than simply because it offers more investment choices.
FAQs About Choosing an SMSF
What is an SMSF?
A Self-Managed Super Fund is a private superannuation fund where the members generally act as trustees and are responsible for managing the fund and complying with superannuation laws.
How many members can an SMSF have?
An SMSF can have up to six members, subject to the relevant superannuation rules.
Do SMSFs need an investment strategy?
Yes.The ATO requires an SMSF to have an investment strategy and to review it regularly.
Can an SMSF invest in property?
Yes, an SMSF can invest in certain types of property, but strict superannuation rules apply.
The investment must be consistent with the fund’s investment strategy and satisfy the relevant legal requirements.
Are SMSFs regulated by APRA?
No. SMSFs are regulated by the Australian Taxation Office (ATO). APRA regulates most large superannuation entities, including APRA-regulated super funds.
What should I consider before setting up an SMSF?
Consider investment choice, costs, administration, insurance, compliance responsibilities, your investment strategy and whether you are comfortable taking responsibility for managing your own superannuation.
How Can We Help?
If you have any questions or would like further information, please contact Camden Professionals on:
Phone: 08 9221 5522
Email: info@camdenprofessionals.com.au
You can also arrange a meeting so we can discuss your requirements in more detail.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Downsizer Contributions: How Selling Your Home Could Boost Your Superannuation
For many Australians approaching retirement, selling the family home can be about more than finding a smaller or more manageable property. It can also create an opportunity to strengthen retirement savings through a downsizer contribution to superannuation.
The Australian Government’s downsizer rules allow eligible homeowners to contribute some of the proceeds from selling their home directly into superannuation. For eligible individuals, the contribution can be up to $300,000, while an eligible couple may potentially contribute up to $600,000 between them, subject to each person’s eligibility and the applicable rules.
- The eligible age for a downsizer contribution is currently 55 years or older.
- Since 1 January 2023, you must be at least 55 years old when making the contribution.
- There is no maximum age limit for a downsizer contribution, provided you meet the other eligibility requirements.
However, downsizing does not automatically mean there will be hundreds of thousands of dollars available to put into super. Property prices, selling costs and the cost of the replacement home all need to be considered.Understanding the rules before selling is important because there are specific eligibility requirements, contribution deadlines and conditions that need to be satisfied.
Why Downsizing Doesn’t Always Mean Having More Cash
The term “downsizing” can sometimes create the impression that selling a large family home will automatically release a substantial amount of money.
That is not necessarily the case.
Many Australians sell their existing home and purchase another property in a desirable location. They may choose a newer apartment, a low-maintenance townhouse or a property closer to family, the coast, healthcare services or a major city.
In some areas, the replacement property can cost almost as much as the home being sold. There are also selling costs, legal fees, moving expenses, stamp duty where applicable and other transaction costs to consider. This means the amount available for a downsizer contribution will depend on the individual’s circumstances and the actual proceeds available from the sale. For those who do have surplus funds, however, the downsizer rules can provide an opportunity to move a significant amount into the superannuation system.
Downsizer Contribution Eligibility: What Are the Rules?
The ATO sets out a few conditions that must be met before a contribution can qualify as a downsizer contribution.
Generally, you must:
- Be 55 years of age or older when making the contribution.
- Have owned the property for at least 10 years before the sale, generally measured from the date of acquisition to the date of disposal.
- Have owned the property as an individual or jointly with your spouse.
- You or your spouse must have held an ownership interest in the property, and the relevant 10-year ownership requirement must be satisfied.
- Make the contribution from the proceeds of selling an eligible Australian residential property.
- Satisfy the relevant main residence requirements.
- Make the contribution within the required timeframe.
- Have not previously made a downsizer contribution from the sale of another dwelling.
The ATO states that the contract for sale must generally have been entered into on or after 1 July 2018. The contribution must generally be made within 90 days of the change of ownership, unless the Commissioner grants an extension. It is therefore important not to treat the downsizer contribution as an informal arrangement that can be organised whenever convenient after settlement.
The 90-Day Downsizer Contribution Deadline
One of the most important practical considerations is timing. Eligible downsizer contributions generally need to be made within 90 days from the change of ownership of the property. The ATO can grant an extension in certain circumstances.
This means homeowners planning to use the downsizer rules should consider their superannuation arrangements before the property settles. Waiting until after settlement to investigate the rules could create unnecessary pressure, particularly if there are questions about eligibility or the amount that can be contributed. The timing should also be considered alongside the settlement of the replacement property, because selling the existing home and buying another property can involve significant cash-flow requirements.
How Much Can You Contribute?
An eligible individual can generally make a downsizer contribution of up to $300,000 from the proceeds of selling an eligible home. The ATO states that the maximum amount an individual can contribute from the sale of one home is the lesser of:
- $300,000, or
- the sale proceeds remaining after taking into account other downsizer contributions made by the individual or their spouse.
Importantly, multiple downsizer contributions can potentially be made from the sale of the same home, provided the total does not exceed the applicable maximum. For example, an eligible homeowner might contribute $150,000 shortly after settlement and another $150,000 later, provided the relevant conditions are met. A couple may also be able to contribute up to $300,000 each if both individuals meet the requirements.
Does a Downsizer Contribution Count Towards Your Normal Super Contribution Caps?
A qualifying downsizer contribution does not count towards your concessional or non-concessional contribution caps. This can make the downsizer rules particularly useful for people who may otherwise have limited opportunities to contribute a significant amount into super. However, once contributed, the money becomes part of your superannuation balance and the normal superannuation rules will apply. The contribution should therefore be considered as part of your broader retirement and superannuation strategy rather than in isolation.
Can Downsizer Contributions Help Build Retirement Wealth?
For homeowners who have substantial equity in their property, downsizer contributions can provide another way to structure retirement savings. Money held in the family home can provide security and reduce housing costs, but it does not generally produce investment income in the same way as assets held within superannuation.
Moving some surplus capital into super may allow the money to form part of a broader retirement investment strategy. However, contributing money to super also means the funds become subject to the superannuation rules.
The decision should therefore be considered as part of an overall retirement plan rather than simply as a tax strategy. The appropriate approach will depend on factors such as:
- Age
- Existing superannuation balances
- Pension arrangements
- Investment objectives
- Cash-flow requirements
- Estate planning
What Does This Have to Do with SMSFs?
Downsizer contributions can also be relevant to people who have a Self-Managed Super Fund (SMSF). An SMSF is a superannuation fund that members manage themselves. SMSFs are regulated by the Australian Taxation Office, rather than APRA. APRA’s own licensing guidance confirms that SMSFs are not RSEs and are instead regulated by the ATO.
This distinction is important. An SMSF trustee remains responsible for ensuring that contributions are correctly accepted and recorded and that the fund complies with superannuation legislation. The supplied material also highlights that SMSF trustees remain responsible for the fund’s investment strategy and compliance even where professional investment managers or other advisers are engaged.
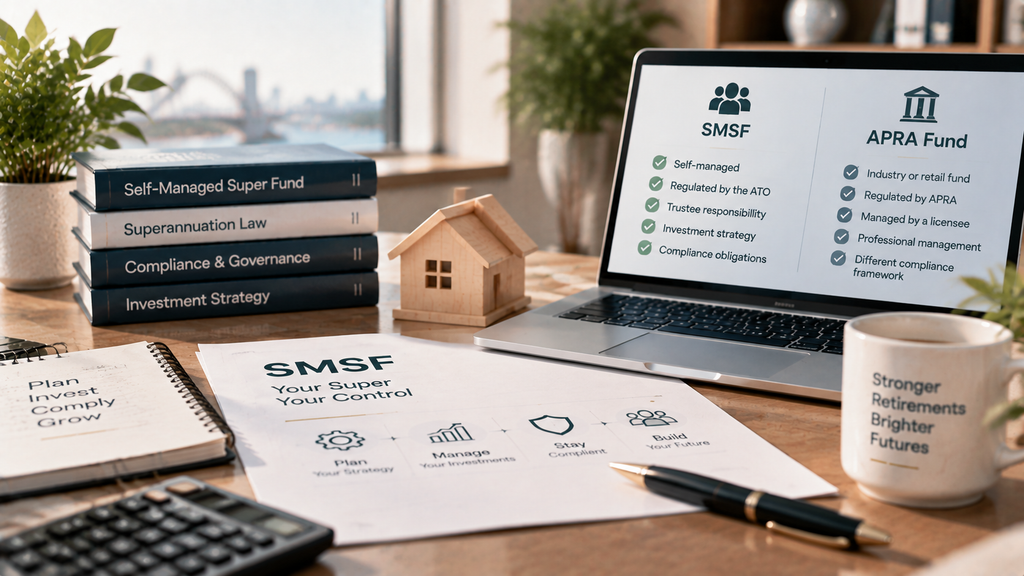
SMSFs vs APRA-Regulated Super Funds
Most Australians have their superannuation with an APRA-regulated fund, such as an industry or retail super fund. APRA oversees registrable superannuation entities and their licensed trustees. APRA’s prudential framework includes requirements covering areas such as:
- Governance
- Investment governance
- Risk management
- Insurance
- Member outcomes
For example, APRA’s SPS 530 Investment Governance requires RSE licensees to maintain an investment governance framework, establish investment objectives and strategies, conduct due diligence and undertake stress testing. APRA’s SPS 510 Governance also establishes minimum governance requirements for RSE licensees and places ultimate responsibility for sound and prudent management with the board. These APRA requirements apply to APRA-regulated superannuation entities and should not be confused with the regulatory framework governing SMSFs.
Most industry and retail super funds are regulated by APRA, while SMSFs are regulated by the ATO. The key practical difference is that SMSF trustees take direct responsibility for the fund’s compliance, investment strategy and administration. For SMSF members, the ATO is the key regulator.
What Are the Risks of an SMSF?
Having greater control over superannuation can also mean greater responsibility. SMSF trustees are responsible for making sure the fund’s investment strategy is appropriate, keeping records, meeting reporting obligations and complying with the superannuation laws. SMSFs do not have the same protections available to members of APRA-regulated funds.
There are also ongoing costs, including:
- Accounting
- Administration
- Auditing
- Regulatory levies
- Investment advice
- Potentially legal and insurance expenses
This means an SMSF should not be established simply because a downsizer contribution is available. The decision to use an SMSF should be considered separately from the decision about whether a downsizer contribution is appropriate.
Can You Use a Downsizer Contribution More Than Once?
Generally, no. The downsizer rules contain a once-only requirement. The ATO states that an individual must not have previously made a downsizer contribution from the sale of any dwelling. This can include multiple partial disposals of an ownership interest in the same dwelling.
This makes it particularly important to understand the rules before making the contribution. A decision to make a downsizer contribution can have long-term consequences because the opportunity generally cannot simply be repeated when another property is sold in the future.
What About the Capital Gains Tax Rules?
The property must generally satisfy the relevant main residence requirements for the downsizer rules. The ATO’s eligibility guidance refers to both an ownership test and a main residence test. This is an important area where professional advice can be useful, particularly where a property has been:
- Used partly as an investment property
- Rented out for periods
- Inherited
- Jointly owned
- Subject to other ownership arrangements
Not every residential property transaction will automatically qualify.
Downsizer Contributions and Capital Gains Tax (CGT)
Selling a property may also create Capital Gains Tax considerations.The tax outcome will depend on the individual’s circumstances, including:
- How the property was used
- Whether it was used to produce income
- Ownership history
- The period the property was held
- Whether any exemptions or concessions apply
The downsizer contribution rules and Capital Gains Tax rules are separate considerations.Meeting the downsizer contribution requirements does not automatically mean there are no CGT implications. Understanding both areas before selling can help avoid unexpected tax outcomes.
Is Downsizing the Right Strategy for You?
Downsizing can be an effective retirement planning strategy for some Australians, but it is not suitable for everyone.The decision involves more than just the opportunity to contribute money into superannuation.Factors to consider may include:
- Future housing needs
- Lifestyle preferences
- Access to funds
- Retirement income requirements
- Superannuation position
- Tax implications
- Estate planning objectives
For some people, remaining in their current home may continue to be the preferred option. For others, selling the family home and contributing surplus funds into superannuation may better align with their retirement goals.
What Should You Consider Before Making a Downsizer Contribution?
Before selling your home, consider:
Your Eligibility
Make sure all downsizer contribution requirements are satisfied before proceeding.
Your Financial Position
Review:
- The expected sale proceeds
- Replacement property costs
- Selling expenses
- Available cash reserves
Your Superannuation Strategy
Consider how the contribution fits with:
- Your existing super balance
- Retirement income plans
- Investment strategy
Your Estate Planning
A significant contribution into superannuation may affect how your assets are structured and passed on in the future.
How Professional Advice Can Help
Downsizer contributions involve several rules and requirements that need careful consideration. Professional advice can help you understand:
- Whether you qualify
- How much you may be able to contribute
- How the contribution fits into your retirement strategy
- Potential tax considerations
- The impact on your broader financial position
Planning before selling your home can help ensure the decision supports your long-term retirement objectives.
Final Thoughts
Downsizer contributions provide eligible Australians with an opportunity to move some proceeds from the sale of their home into superannuation. For some homeowners, this can help strengthen retirement savings and provide greater flexibility. However, selling a home is a significant financial decision and should be considered carefully. The downsizer rules should be reviewed alongside:
- Retirement plans
- Superannuation strategy
- Tax considerations
- Investment objectives
- Estate planning arrangements
Understanding the requirements before selling can help ensure decisions are made with a clear understanding of the potential outcomes.
Frequently Asked Questions
What is a downsizer contribution?
A downsizer contribution allows eligible Australians to contribute some proceeds from selling their home into their superannuation fund.
How much can I contribute through downsizer rules?
Eligible individuals may be able to contribute up to $300,000 from the sale of an eligible home.
Can couples both make downsizer contributions?
Yes. If both individuals meet the eligibility requirements, each person may be able to contribute up to $300,000.
What age do I need to be to make a downsizer contribution?
You must generally be at least 55 years old when making the contribution and meet the other eligibility requirements.
Does a downsizer contribution count towards normal contribution caps?
No. A qualifying downsizer contribution does not count towards concessional or non-concessional contribution caps.
Can I make a downsizer contribution more than once?
Generally, no. The downsizer rules include a once-only requirement.
Can I make a downsizer contribution into an SMSF?
Yes, provided the SMSF accepts the contribution and all eligibility requirements are satisfied.
How Can We Help?
If you are considering selling your home and want to understand how downsizer contributions may apply to your retirement strategy, Camden Professionals can help review your options.
Our team can assist with:
- Retirement planning considerations
- Superannuation strategies
- Tax implications
- Wealth planning
- Financial structuring considerations
Contact Camden Professionals to discuss your circumstances.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Division 296 Tax Explained: What Australia’s New Super Tax Means for Balances Over $3 Million
For many Australians, superannuation has been one of the most effective long-term wealth-building structures due to its concessional tax treatment. However, from 1 July 2026, changes under Division 296 tax will reduce some of the tax advantages available to individuals with larger superannuation balances.
The introduction of Division 296 tax means individuals with superannuation balances above certain thresholds need to carefully consider how they structure their retirement savings, investments and future contributions. For the 2026–27 financial year, the first threshold is set at $3 million, with a second threshold applying at $10 million.
These thresholds will be indexed in future years.
What Is Division 296 Tax?
Division 296 is a new tax measure that applies an additional tax on earnings associated with superannuation balances above specified thresholds. The purpose of the measure is to reduce the tax concessions available to individuals with very large superannuation balances.
For the 2026–27 financial year:
- The first threshold is $3 million
- A second threshold applies at $10 million
- Thresholds will be indexed over time
The additional tax does not mean your entire superannuation balance is taxed at a higher rate once it exceeds the threshold.Instead, the tax applies only to the relevant proportion of earnings connected to the amount above the applicable threshold.
How Does Division 296 Tax Work?
Division 296 tax is calculated based on the proportion of your superannuation balance that exceeds the relevant threshold.It does not apply to your entire superannuation balance.For example, if your superannuation balance is slightly above $3 million, the additional tax applies only to the portion relating to the amount above the threshold.
The calculation considers:
- Your total superannuation balance
- The applicable threshold
- The earnings attributable to the excess amount
This means the impact can vary significantly between individuals depending on their balance, investment performance and circumstances.
Does Division 296 Tax Mean Super Is Taxed at 30%?
No. A common misunderstanding is that once your super balance exceeds $3 million, your entire superannuation balance will automatically be taxed at 30%.
This is not how Division 296 works. The additional tax applies only to the relevant proportion of earnings associated with the balance above the threshold. Your existing superannuation tax treatment continues to apply to the portion within the normal limits.
What Happens Above the $10 Million Threshold?
A higher threshold applies for individuals with very large superannuation balances.
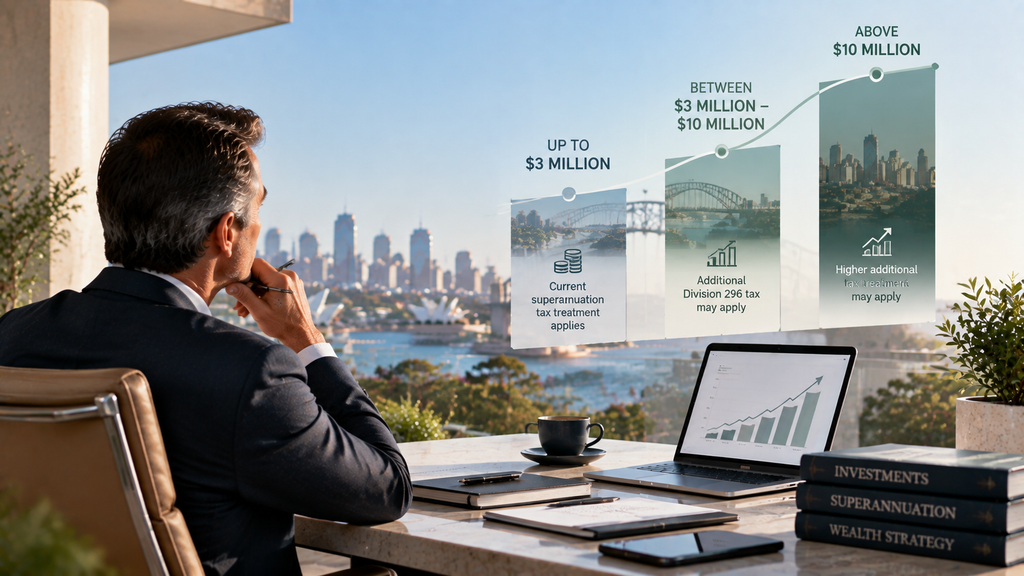
For the 2026–27 financial year:
| Superannuation Balance | Additional Division 296 Treatment |
|---|---|
| Up to $3 million | Existing superannuation tax treatment applies |
| Between $3 million and $10 million | Additional Division 296 tax may apply |
| Above $10 million | Higher additional tax treatment may apply |
The purpose of the second threshold is to apply a higher level of taxation to extremely large superannuation balances.
How Are Earnings Calculated Under Division 296?
An important aspect of Division 296 is that the calculation is based on earnings determined under the legislation. The calculation considers changes in the value of superannuation interests and other relevant factors. For individuals with complex superannuation arrangements, including self-managed super funds (SMSFs), the calculation can become more complicated. Factors that may affect the outcome include:
- Investment income
- Capital gains
- Pension interests
- Changes in account balances
- Timing of contributions and withdrawals
Are Unrealised Gains Taxed Under Division 296?
The final Division 296 rules changed from earlier proposals. The calculation does not simply tax every unrealised increase in investment value. An increase in the value of an investment is not automatically taxed just because the market value has increased and the asset has not been sold. However, the calculation remains complex and depends on the specific circumstances of the individual.
Does Division 296 Mean Super Is No Longer Tax Effective?
No. Superannuation can still remain one of the most tax-effective investment structures available. Super continues to provide significant tax benefits, including:
- Concessional tax treatment in accumulation phase
- Potential tax-free earnings in eligible retirement-phase pensions
The introduction of Division 296 does not remove the benefits of superannuation. Instead, it changes the way individuals with very large balances need to think about future wealth accumulation.
Should You Stop Contributing to Super After Reaching $3 Million?
Not necessarily. Reaching the $3 million threshold does not automatically mean that superannuation is no longer suitable. The right strategy depends on factors such as:
- Your retirement goals
- Your investment strategy
- Your personal tax position
- Your access requirements
- Your estate planning objectives
For some individuals, continuing to use super may still provide significant advantages. For others, building wealth outside super may become an important consideration.
Superannuation vs Building Wealth Outside Super
As super balances grow, some individuals may consider whether future investments should remain inside super or be held through alternative structures.
Key considerations include:
| Consideration | Superannuation | Outside Super |
|---|---|---|
| Tax treatment | Generally concessional | Depends on structure |
| Access | Restricted until conditions of release are met | Generally greater flexibility |
| Investment options | Subject to super rules | Wider range of structures available |
| Estate planning | Specific superannuation rules apply | Depends on ownership structure |
The decision is not only about tax. Other factors, including access, flexibility and estate planning, should also be considered.
Could an Investment Company Be an Alternative?
For some individuals with significant wealth, an investment company may form part of a broader wealth strategy. An investment company may allow profits to remain within the company and be reinvested. This can be useful for individuals who:
- Are still accumulating wealth
- Do not require investment income personally each year
- Want greater control over investment capital
However, an investment company is not automatically better than super.
The structure has its own considerations, including:
- Corporate tax rates
- Administration costs
- Loss of some capital gains tax concessions
- Tax implications when extracting funds

Estate Planning Considerations
Division 296 discussions should not focus only on tax during your lifetime. Estate planning is also an important consideration for individuals with large superannuation balances. Superannuation does not automatically form part of your estate.
The outcome depends on:
- Beneficiary nominations
- Super fund rules
- Estate planning arrangements
Super Death Benefits Tax
The tax treatment of superannuation death benefits depends on who receives the benefit.
Generally:
- Payments to eligible dependants may receive concessional treatment.
- Payments to non-dependants, such as some adult children, may have different tax consequences.
For individuals with significant super balances, planning ahead can help manage potential tax outcomes for beneficiaries.
What Should High-Balance Super Members Do?
Individuals approaching or exceeding the $3 million threshold should review their overall wealth strategy. Important areas to consider include:
- Superannuation balance management
- Investment structure
- Contribution strategy
- Retirement planning
- Estate planning
The introduction of Division 296 does not mean immediate action is required for everyone. However, understanding the potential impact early can help create a more effective long-term strategy.
Final Thoughts
Division 296 tax represents a significant change for Australians with larger superannuation balances. However, it does not mean superannuation is no longer valuable. The key is understanding how the new rules interact with your personal circumstances and long-term goals. For some individuals, continuing to maximise superannuation benefits may remain the right approach. For others, combining super with investments held outside super may provide greater flexibility and control. A strategic review can help determine the most appropriate approach for your situation.
Frequently Asked Questions
Is super still tax effective after Division 296?
Yes. Superannuation can still provide significant tax advantages, even after Division 296 applies to larger balances.
Does Division 296 tax my entire super balance?
No. The additional tax applies only to the relevant proportion of earnings connected to amounts above the applicable threshold.
Does Division 296 apply from 1 July 2026?
Yes. The measure applies from the 2026–27 financial year.
Will everyone with more than $3 million in super pay Division 296 tax?
Not necessarily. The outcome depends on your balance, earnings and individual circumstances.
Should I move money out of super once I reach $3 million?
Not automatically. The decision depends on your retirement objectives, tax position, investment strategy and estate planning needs.
Is an investment company better than super?
Not always. An investment company may provide flexibility, but it also has different tax and administration considerations.
How Can We Help?
If your superannuation balance is approaching or exceeding $3 million, Camden Professionals can help review your current position and understand how the Division 296 changes may affect your broader wealth strategy. Professional advice can help you assess:
- Superannuation strategies
- Investment structures
- Retirement planning
- Estate planning considerations
Contact Camden Professionals to discuss your circumstances and explore your available options.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Retirement Planning Strategies for High-Net-Worth Australians
One of the most common questions high-net-worth individuals ask is how to structure superannuation and overall wealth effectively in retirement. With significant assets, the opportunities available in retirement are substantial but so are the complexities around tax, income sustainability, and long-term wealth preservation.
For most retirees, holding as much of their wealth as possible within superannuation remains a cornerstone strategy due to its concessional tax treatment. However, for individuals with large balances, additional investment structures such as family trusts and companies often play a critical role in optimising outcomes.
Effective retirement planning is not just about maximising wealth it’s about ensuring certainty, flexibility, and confidence throughout retirement.
Why Is a Retirement Plan Essential?
A comprehensive retirement plan provides clarity around your financial future and ensures your wealth is structured to support your desired lifestyle. It defines your income objectives and establishes a framework to achieve them in a tax-efficient manner.
A robust retirement strategy should address:
- How much of your superannuation can be transferred into a tax-free pension account
- How to manage funds remaining in accumulation phase to minimise tax while maintaining growth
- A sustainable income drawdown strategy aligned with your lifestyle goals
- The use of non-super investment structures, such as family trusts or companies, to manage tax and distribute income to beneficiaries
- Long-term financial security, including succession planning and wealth preservation
Beyond the numbers, retirement planning helps answer critical lifestyle questions when you’ll retire, whether you’ll transition into part-time work, and how you’ll spend your time and money. For many high-net-worth retirees, this includes international travel, premium lifestyle expenses, luxury assets, and supporting children or grandchildren financially.
How Much Super Can Be Transferred to a Tax-Free Pension?
Once you retire after age 60, you may commence an account-based pension from your superannuation. If you continue working, pensions can be commenced from age 65, or earlier via a Transition to Retirement (TTR) pension.
The Transfer Balance Cap limits how much superannuation can be moved into the tax-free pension phase. As at 1 July 2025, this cap is $2 million per individual.
Example: $4 Million Superannuation Balance
- $2 million can be transferred into a tax-free retirement pension
- The remaining $2 million stays in accumulation phase, where earnings are taxed at up to 15%
This structure allows you to maximise tax-free income while keeping excess funds invested in a concessionally taxed environment.
How Much Income Must You Draw from Your Pension?
Once in pension phase, minimum annual withdrawals apply:
- 4% of the account balance from age 60
- 5% from age 65
For a $2 million pension account, a 60-year-old retiree must withdraw at least $80,000 per year, completely tax-free.
While higher withdrawals are permitted, it is often more tax-effective to:
- First draw income from assets outside super
- Then from accumulation phase
- Finally, draw additional funds from the pension account
In some cases, delaying the commencement of a pension may be advantageous—particularly if you are already paying the highest marginal tax rate and do not require immediate income. Keeping funds in superannuation without mandatory withdrawals can preserve long-term tax efficiency.
Can You Still Contribute to Superannuation?
Depending on your circumstances, additional super contributions may still be available:
Concessional Contributions
- Up to $30,000 per year
- Tax deductible if income supports it
- From ages 67–74, a work test applies
Non-Concessional Contributions
- Up to $120,000 per year
- Available up to age 74
- Only permitted if your total super balance is below $2 million
Downsizer Contributions
Even if you’re over 74 or exceed the $2 million cap, you may still qualify for a downsizer contribution:
- Up to $300,000 per person
- Must be over 55
- Property must have been owned for at least 10 years
- Must have been your principal residence at some point
- Contribution must be made within 90 days of settlement
What If You Can’t Contribute Any More to Super?
When further super contributions are no longer possible, a family trust can be an effective alternative for managing and growing wealth.
A family trust allows income to be distributed among beneficiaries often family members—based on tax efficiency and the trust deed. This flexibility can significantly reduce overall tax payable.
In some cases, appointing a company as a beneficiary can further enhance outcomes, with company tax rates capped at 30%, compared to the top marginal rate of 47%. However, when funds are later withdrawn from the company, additional tax may apply.
Trust structures can also play a vital role in wealth succession planning, offering flexibility and control across generations.
How Do You Manage Wealth Succession and Estate Planning?
High-net-worth retirees often have complex estates, making succession planning essential.
Key considerations include:
- Up-to-date wills and estate planning documents
- Appropriate superannuation beneficiary nominations
- Future trustee and executor arrangements
- Tax-effective strategies for transferring wealth
Legal and tax advice is critical to ensure your wealth is passed on according to your wishes and in the most efficient manner.
Equally important is preparing the next generation. Open conversations about wealth, responsibility, and long-term planning can help ensure your legacy is preserved and managed wisely. These discussions take time, making early engagement invaluable.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Super tax update – Proposed changes to Division 296
The Federal Government has responded to industry feedback on its proposed new tax for superannuation balances exceeding $3 million, announcing several significant adjustments aimed at making the measure fairer and more practical.*
*Note: However, the proposal is not yet legislated, and further consultation with industry stakeholders is expected before it is introduced to parliament. If passed by parliament, the measure will begin from July 2026.On 13 October 2025, Treasurer Jim Chalmers provided a long-awaited announcement regarding the status of the proposed Division 296 tax on superannuation balances exceeding $3 million, confirming it would proceed effective 1 July 2026 but with some significant changes to the methodology and thresholds – such as the exclusion of unrealised capital gains from the tax.
While the revised proposal is arguably more positive for most individuals than the previously announced versions, this change in approach means many people with large or growing superannuation balances will need to take yet another turn on the road to planning the most suitable structures in which to hold their wealth
Under the revised proposal:
- Indexation of the cap – the $3 million threshold will be indexed to CPI, increasing in $150,000 increments to reflect inflation
- Tiered tax rates – earnings on super balances between $3 million and $10 million will attract a 30 per cent tax, while balances above $10 million will face a 40 per cent rate on the proportion above that amount. The $10 million cap will be indexed in $500,000 increments
- Removal of tax on unrealised gains – importantly, the government has dropped the contentious plan to tax unrealised earnings, opting instead to tax actual income, aligning the proposal with established Australian tax principles
- Deferred commencement – the measure will now start from 1 July 2026, with the first notices of assessment expected in the 2027–28 financial year.
Treasury example
To illustrate how the changes will work in practice, Treasury provided the following example:
Megan, aged 58, has a total superannuation balance of $4.5 million, with $2.3 million in an APRA-regulated fund and $2.2 million in an SMSF.
In the 2026–27 financial year, she earns $300,000 in realised income ($100,000 from her APRA fund and $200,000 from her SMSF).
The proportion of her balance above the $3 million threshold is 33.33 per cent, with no portion above $10 million. Her additional tax under the proposed Better Targeted Superannuation Concessions (BTSC) measure would therefore be: $15,000 = 0.15 × 0.3333 × $300,000
What does this mean for super fund members?
The proposed tax increase was announced more than two years ago and was meant to be in effect from July 2025. However, it was met with criticism, and the bill was never introduced to parliament.
The revised proposal represents a positive shift, particularly the removal of the unrealised gains component, which was a major concern for many investors and advisers.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Changes to Deeming Rates: How Will This Affect Your Pension?
Five years after being cut to historic lows during the COVID-19 pandemic, deeming rates have now increased — impacting how the government calculates your income from financial assets.
This change could affect how much age pension or other Centrelink income support you receive. If you’re a part-pensioner or have financial assets like savings, shares, or superannuation, here’s what you need to know.
What Is Deeming?
Deeming is a set of rules used by Centrelink to estimate how much income you earn from financial assets such as:
- Bank accounts
- Shares and managed funds
- Superannuation (for people over age pension age)
- Term deposits and other investments
Rather than assessing your actual investment income (which can vary), Centrelink assumes your assets earn a “deemed” rate of return. This simplifies the income test for payments like the age pension.
Key point:
If your actual returns are higher than the deeming rate, that extra income isn’t counted — which can benefit savvy investors.
When Did the Deeming Rate Changes Happen?
The changes came into effect on Saturday, September 20, 2025, coinciding with the regular indexation of government payments such as:
- Age Pension
- Disability Support Pension
- Carer Payment
- JobSeeker and Youth Allowance
These deeming rate increases were announced in August 2025 and are the first in five years, following pandemic-era cuts designed to help older Australians cope with low interest rates and cost-of-living pressures.
What Are the New Deeming Rates?
As of September 2025:
| Rate Tier | Old Rate (2020–2025) | New Rate (from Sept 2025) |
| Lower deeming rate | 0.25% | 0.75% |
| Upper deeming rate | 2.25% | 2.75% |
How the deeming thresholds work:
- Single pensioners:
- First $64,200 of financial assets = deemed at 0.75%
- Any amount above $64,200 = deemed at 2.75%
- Pensioner couples (combined assets):
- First $106,200 = deemed at 0.75%
- Anything over that = 2.75%
Who Is Affected by the Changes?
These changes apply to any Centrelink income support recipient who has financial assets, but the most affected are:
- Age pensioners (the largest group impacted)
- Part-pensioners with significant investments or superannuation
- People nearing retirement with assessable financial assets
According to the Department of Social Services, age pensioners make up around 60% of those affected because they typically hold larger asset balances.
Will Payments Go Down?
Yes, but only for a small portion of pensioners.
- About 69,500 age pensioners are expected to see a reduction in their fortnightly payments.
- The median decrease is $6.70 per fortnight.
- For some, the drop could be more or less depending on individual financial circumstances.
Note: These reductions may be partly offset by the indexation increases to the age pension and other Centrelink payments.
Example – How Deeming Works Now:
Scenario: Single age pensioner with $100,000 in assets
- First $64,200 at 0.75% = $481.50
- Remaining $35,800 at 2.75% = $984.50
- Deemed annual income = $1,466
- Fortnightly income counted = ~$56.38
This income is used in the income test, which could reduce your pension depending on your other sources of income.
Why Do Deeming Rates Matter?
- The higher the deeming rate, the more income Centrelink assumes you’re earning.
- This can reduce your age pension if you’re near or over the income threshold.
- If you’re under the full-pension income cut-off, it may not impact you at all.
- If you earn less than the deemed rate, Centrelink still uses the deeming rate, not your actual income.
Conclusion
After five years of historic lows, deeming rates have now increased, affecting how Centrelink calculates income from financial assets. For tens of thousands of part-pensioners, this could result in a small reduction to their age pension. However, with these changes occurring alongside increases to the pension itself, the overall impact for most will be modest.
Looking ahead, deeming rates are likely to continue reflecting economic conditions and investment returns. Pensioners and retirees should consider reviewing their financial assets — including savings and super — and seek advice if needed to understand how future deeming changes may affect their entitlements.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How Much Money Do You Need to Retire Comfortably
Planning for retirement can feel overwhelming, especially when the definition of a “comfortable retirement” varies so widely from one person to the next. Some Australians dream of travelling the world, while others simply want a peaceful lifestyle close to family and friends.
So how do you turn your vision of retirement into a real, measurable savings goal?
Let’s break down the key factors that influence how much you’ll need to retire — using trusted Australian sources like MoneySmart and the Association of Superannuation Funds of Australia (ASFA) — and provide real-world examples to help you start planning with confidence.
What Will Retirement Look Like for You?
- Lifestyle Goals
Your desired lifestyle has the biggest impact on your retirement savings target. Consider the following questions:
- Do you plan to travel regularly (domestically or overseas)?
- Will you maintain private health cover?
- Do you want to dine out or enjoy hobbies that come with regular costs?
- Will you own your home outright?
Your answers will shape how much income you’ll need each year.
Life Expectancy
Australians are living longer than ever. If you retire at 65, you may need your savings to last 20–25 years or more.
| Gender | Expected Age at Death (from age 65) |
| Men | 84.6 years |
| Women | 87.3 years |
(Source: Australian Bureau of Statistics)
Planning for longevity is essential — and so is factoring in that retirement spending typically changes over time. Younger retirees (65–75) often spend more on travel and entertainment, while older retirees spend more on healthcare and support.
What’s Considered a “Comfortable” Retirement?
According to ASFA, a “comfortable” lifestyle in retirement includes:
- Private health insurance
- One or two short domestic holidays annually
- Eating out occasionally
- Good clothes
- A car replacement every 7–10 years
ASFA’s Comfortable Retirement Budget (2024 figures)
| Household Type | Annual Income Needed | Lump Sum Required at Retirement (Age 67) |
| Single | $51,630 | $595,000 |
| Couple | $72,663 | $690,000 |
Assumes home ownership and relatively good health.
What If Your Version of Comfortable Is Different?
Let’s say you currently earn a household income of $150,000 and want to maintain a similar standard of living in retirement.
According to MoneySmart, a general rule of thumb is to aim for 67% of your pre-retirement income. That means you’d need around $100,000 per year in retirement income.
Using Money Smart’s Retirement Planner, we estimated lump sums needed to achieve different levels of retirement income, assuming:
- Retirement age: 67
- Life expectancy: 87
- Investment return: 6.5% p.a.
- Aged Pension included where eligible
- Rounded to nearest $5,000
| Annual Retirement Income Target | Lump Sum Required (Couple) |
| $72,663 (ASFA “comfortable”) | $690,000 |
| $85,000 | $1,000,000 |
| $100,000 | $1,250,000 |
Superannuation
Your superannuation is the foundation of your retirement income. To maximise it:
- Consider increasing contributions through salary sacrifice or after-tax payments.
- Regularly review your investment options.
- Monitor fees and performance.
Don’t forget that nearly 50% of your final super balance is accumulated in the last 5–10 years before retirement due to compound interest — so it’s never too late to take action.
Investments & Assets
Beyond super, your other assets can support your lifestyle:
- Shares, ETFs, and managed funds
- Investment properties
- Term deposits and bonds
- Downsizing your home (accessing home equity)
These can provide income streams or be liquidated to fund big expenses.
The Age Pension
According to the Department of Social Services, 62% of Australians over age 67 receive some form of Age Pension.
The Age Pension can reduce the pressure on your savings but generally won’t fund a comfortable lifestyle alone.
Planning Ahead: What Can You Do Today?
No matter your current age or income, there are steps you can take now to secure a better retirement:
| Action | Why It Matters |
| Use the MoneySmart Retirement Planner | Estimate how much super you’ll need and if you’re on track |
| Increase voluntary super contributions | Even small amounts grow significantly over time |
| Seek advice from a financial adviser | Tailored strategies can improve outcomes and reduce tax |
| Consolidate super accounts | Avoid paying multiple sets of fees |
| Track your lifestyle goals | Knowing your vision helps you save with purpose |
Conclusion
There’s no one-size-fits-all answer to the question “How much money do I need to retire comfortably?” Your unique vision of retirement — whether it includes world travel or quiet mornings in your garden — determines your goal.
The key is to start early, make informed decisions, and check in regularly with your plan.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Accrued Leave at Retirement: Take the Holiday or Take the Payment?
If retirement is just around the corner and you’ve built up a sizeable bank of accrued leave, you may be facing a tough question: Should you take a well-earned break now or cash it out as a lump sum when you retire?
While both options might seem attractive, the decision can have significant implications for your superannuation, tax, and even your Age Pension eligibility. Understanding the pros and cons of each path can help you make a choice that maximises your long-term financial wellbeing.
- Superannuation: Boost Your Nest Egg
When you take leave as paid time off before you retire, your employer must pay superannuation guarantee (SG) contributions on those earnings. At the current SG rate of 11.5% (rising to 12% on 1 July 2025), this can provide a valuable boost to your retirement savings.
However, no SG is payable on lump sum leave payments made at the time of retirement — so choosing the payout option means you’ll miss out on that extra super.
Smart Tip:
Take your leave before retiring if you want to increase your super balance — especially in your final working year when every dollar counts.
- The Work Test & Super Contributions After Retirement
If you’re between 67 and 75 years old, you need to meet the “work test” to claim a tax deduction for personal super contributions:
Work at least 40 hours over a consecutive 30-day period in the financial year you contribute.
If you retire and no longer meet the work test, you could lose the opportunity to claim a tax deduction — unless you qualify for the “work test exemption.” This exemption allows one extra year of contributions for retirees with less than $300,000 in super, provided they met the work test in the previous financial year.
Smart Tip:
Plan ahead. Taking leave in July or August and clocking up 40 hours of work early in the new financial year may help you meet the test (or exemption) and keep your super strategies on track.
- Tax: Timing Matters
Lump sum leave payouts are taxed in the financial year they’re received, which could bump you into a higher tax bracket — especially if you also receive termination payments or a final salary.
Delaying your retirement into the next financial year by taking accrued leave as time off could provide:
- More favourable tax treatment if your post-retirement income is low
- Increased ETP (employment termination payment) caps in the new financial year
- A better chance of staying in a lower marginal tax bracket
Smart Tip:
Consult your adviser to explore whether deferring retirement could reduce your tax burden — particularly if your final year includes significant payments like unused leave or redundancy.
- Centrelink & the Age Pension
If you’re planning to apply for the Age Pension when you retire, it’s essential to understand how your leave payout might affect your eligibility:
- Lump sum leave payments aren’t counted as income under the Centrelink income test, but they do count as assets once invested or banked. This could push your total assets above the asset threshold and reduce or eliminate your pension entitlements.
- Wages paid during leave (if taken before retirement) are not counted as assets or income once you’re officially retired and applying for the pension.
Smart Tip:
If you’re close to the pension threshold, taking leave before retiring may help you qualify for the Age Pension sooner — and for longer.
Conclusion: There’s No One-Size-Fits-All
Choosing whether to take your accrued leave as paid time off or cash it out as a lump sum at retirement depends on your personal goals, finances, and timing.
Take the holiday if:
- You want more super contributions
- You need to meet the work test
- You prefer to spread your income for better tax outcomes
- You’re close to Age Pension eligibility limits
Take the lump sum if:
- You want to finish work earlier
- You qualify for tax concessions on ETPs
- You’re not planning to contribute further to super
- You won’t be impacted by the Age Pension assets test
Planning well in advance — with the help of a qualified tax or financial adviser — can help you take full advantage of tax benefits, boost your retirement savings, and avoid any Centrelink surprises.
Final Smart Tips Before You Decide:
- Check your super balance and contribution limits before finalising retirement.
- Use a super calculator to model different outcomes with leave taken as time off vs lump sum.
- Ask your employer for details about your leave balance and termination payout projections.
- Update your Centrelink and ATO records before any big financial change.
- Consult a tax professional to align your retirement and tax strategies.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Smart Ways to Boost Your Super Before EOFY
With the end of the financial year just around the corner, now’s the time to give your superannuation a healthy boost. Whether you’re looking to reduce your tax bill, take advantage of government incentives, or simply build your retirement savings, these five savvy strategies can help you make the most of your super before EOFY, 30 June 2025.
- Top Up with Concessional (Pre-Tax) Contributions
Concessional contributions—such as salary sacrifice or personal deductible contributions—are taxed at just 15%, which is usually lower than your marginal tax rate. You can contribute up to $30,000 per year (inclusive of your employer’s 11.5% Super Guarantee). This strategy can help reduce your taxable income and grow your retirement savings.
- Catch Up on Unused Contribution Caps
Haven’t used your full concessional cap in the last few years? Good news: if your total super balance is under $500,000 at 30 June 2024, you can carry forward unused cap amounts from the past five years and make a lump sum contribution this year. It’s a great way to catch up if you had lower contributions in previous years.
- Make the Most of Non-Concessional (After-Tax) Contributions
These contributions don’t attract tax on the way in, but they can significantly grow your retirement savings over time. You can contribute up to $120,000 annually, or even $360,000 over three years using the bring-forward rule (if eligible). If you’re a low- to middle-income earner, you may also be eligible for a government co-contribution of up to $500 when you make a personal after-tax contribution.
- Boost Your Partner’s Super and Get a Tax Offset
If your spouse earns under $37,000 (or less than $40,000 with a reduced offset), you could be eligible for a tax offset of up to $540 by making a spouse contribution. It’s a great way to support your partner’s retirement savings while reducing your own tax.
- Split Contributions with Your Spouse
Want to balance out super between you and your partner? You may be able to split up to 85% of your concessional contributions with your spouse. This can help manage future tax liabilities, especially if one partner earns significantly less or is planning to take a career break.
Taking action before 30 June can make a real difference—not just to your tax return, but to your future financial security. Whether you’re building your own super, supporting your partner’s, or leveraging contribution caps, these strategies can help you maximise your savings and minimise tax.
Need help choosing the right strategy? Speak with your financial adviser or tax professional to make sure your contributions align with your goals and the latest super rules.
Start now — your future self will thank you.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How to make smart super investment choices
Choosing smart investment options for your superannuation is crucial for building a comfortable retirement. With various investment choices available, understanding their distinct characteristics and associated risks is key to selecting the best option for your financial future.
Premixed, Choice, and Lifecycle Options
Super funds typically offer several premixed investment options with different asset allocations, such as:
- Growth: These options focus on shares and property with the goal of achieving high returns over the long term. However, they come with a higher potential for short-term losses, making them suitable for investors with a longer investment horizon.
- Balanced: With around 70% invested in shares and property, balanced options target moderate returns with less risk than growth options. These are ideal for investors seeking growth but preferring less volatility.
- Conservative: These options primarily invest in fixed interest and cash, focusing on preserving capital with lower returns. They’re typically for more risk-averse individuals.
- Cash: Investing 100% in cash or similar instruments, cash options offer stability and capital preservation. These are best for those nearing retirement or highly risk-averse.
- Ethical: These investments exclude companies that don’t meet specific ethical standards, and their market risk varies. They offer an opportunity to align investments with personal values.
In addition to premixed options, some super funds allow investors to choose individual asset classes, such as Australian or international shares, or even direct investments in shares, exchange-traded funds (ETFs), or term deposits. These options offer more control but require a higher level of engagement with the investment strategy. Lifecycle investment options, on the other hand, automatically reduce exposure to higher-risk assets as you age, providing a hands-off approach for those who prefer a more passive strategy.
Understanding Your Risk Profile
When selecting an investment option, it’s essential to understand your risk profile—your comfort level with potential losses in pursuit of returns. Consider these factors:
- Risk tolerance: Assess how much market risk you’re willing to accept. Are you comfortable with short-term losses for potential long-term gains, or do you prefer stability?
- Investment horizon: The time remaining before you access your super influences your risk tolerance. Longer time horizons can often accommodate riskier investments, while shorter ones may call for more conservative approaches.
- Standard market risk measure: Super funds provide a standardized risk rating that predicts the likelihood of a negative return over 20 years. This rating can help you compare the risk levels of various investment options.
For example, a 30-year-old with a long-term investment horizon may be comfortable with the volatility of a growth option, while someone nearing retirement may prefer the stability of a more conservative approach. However, it’s important to balance stability with the risk of inflation, as overly conservative investments might not keep pace with inflation, potentially eroding purchasing power over time.
Conclusion
Choosing the right investment option for your superannuation requires careful consideration of your individual circumstances, risk tolerance, and long-term goals. It’s important to balance potential returns with your comfort level regarding market fluctuations. Utilizing online resources, such as ASIC’s Moneysmart website, can help guide your decision, and many super funds offer free guidance as well. Seeking professional advice, such as from a financial adviser, can also provide personalized insights to help you make an informed choice. Ultimately, a well-considered approach will put you on track for a more secure and prosperous retirement.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.