




Is Your Property Investment Strategy Still Working for You
Buying an investment property is rarely a spur-of-the-moment decision. Most Australian property investors spend considerable time researching suburbs, comparing loans, assessing rental yields and considering how the property fits their long-term wealth strategy.
But once the property is settled and tenants move in, it is easy to adopt a “set and forget” approach.
Your circumstances can change. Income, interest rates, rental returns, property values, lending policies, tax rules, family circumstances and retirement plans may all look different several years after purchase. As a result, a property that made sense five or ten years ago may no longer be the most appropriate strategy.
That is why a regular investment property review can be valuable. The objective is not necessarily to buy, refinance or sell, but to determine whether your property portfolio is still helping you achieve your broader financial and lifestyle goals.
What Is an Investment Property Review?
An investment property review is a structured assessment of your property, finance, taxation, cash flow, risk and long-term investment objectives.
Rather than focusing only on whether the property has increased in value, consider:
- Is the property generating an acceptable return?
- Has the rental yield changed?
- Is the property still suitable for your objectives?
- How much equity have you built?
- Is the loan structure still appropriate?
- Are you paying a competitive interest rate?
- How much does the property cost to hold?
- Are you claiming legitimate tax deductions?
- Is your ownership structure still appropriate?
- How exposed are you to interest rate increases?
- Is your portfolio too concentrated in property?
- Does the investment still fit your retirement strategy?
- Would selling, refinancing, reducing debt or buying another property improve your overall position?
The answers may be very different from when you originally purchased the property.
1. Start Your Property Investment Review with Your Financial Goals
Before reviewing property values or rental income, return to the fundamentals.
Why did you buy the property?
Your original objectives may have included building wealth, achieving capital growth, generating rental income, creating a retirement asset, diversifying investments, using borrowing to accelerate wealth creation or reducing taxable income through negative gearing.
Your circumstances may now be different. You may be earning more, approaching retirement, carrying additional debt, supporting a family or prioritising cash flow over capital growth.
The key question is not simply:
“Is my investment property performing?”
It is:
“Is my investment property still helping me achieve my financial goals?”
2. Calculate the True Cash Flow of Your Investment Property
Rental income alone does not tell you whether a property is financially successful. You need to consider net cash flow after relevant costs.
These can include:
- mortgage interest and principal repayments
- property management fees
- council rates and water charges
- insurance
- land tax
- strata or body corporate fees
- repairs and maintenance
- accounting costs
- vacancy periods.
A property experiencing strong capital growth may still require substantial cash contributions each year. This does not necessarily make it a poor investment, but you need to understand the cost of holding it and whether that cost remains appropriate.
3. Review Your Rental Yield and Investment Return
Capital growth is important, but it is only one part of the investment equation.
Review your:
Gross rental yield – annual rental income compared with the property’s current market value.
Net rental yield – rental income after relevant ongoing expenses.
Total return – which may include rental income, capital growth, tax effects, financing costs and property expenses.
Looking at the property’s current market value rather than simply what you originally paid can provide a different perspective on performance.
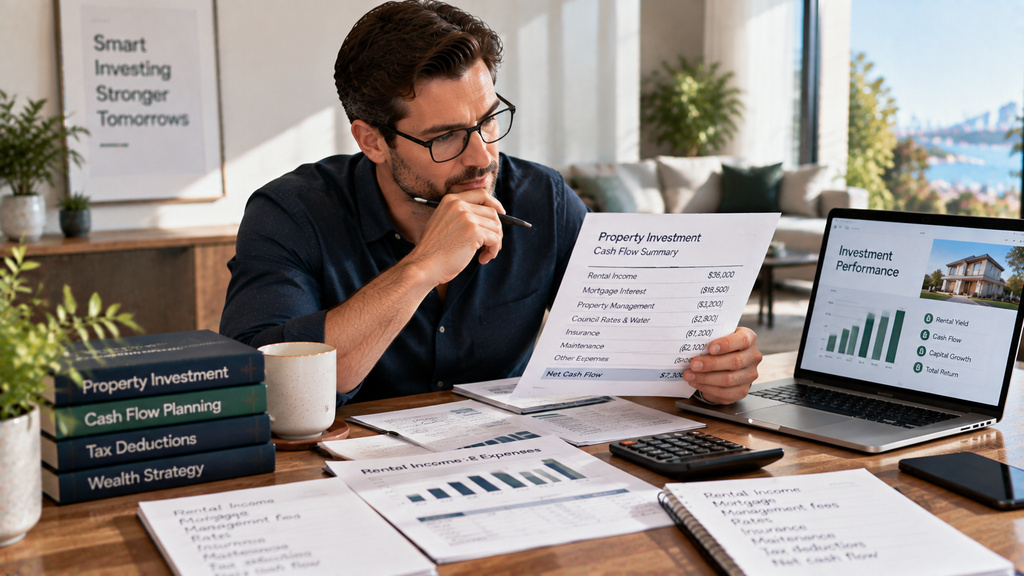
4. Review Your Investment Property Loan and Interest Rate
Your mortgage can have a significant impact on investment property cash flow.
If you have not reviewed your loan for several years, consider:
- current interest rate
- fixed versus variable structure
- principal and interest versus interest-only
- loan term
- offset facilities
- available equity
- loan fees
- refinancing costs
- borrowing capacity.
Refinancing should not be considered simply because another lender advertises a lower rate. Consider the overall cost and structure of the loan and how any change fits your broader strategy.
5. How Much Equity Do You Have in Your Investment Property?
Understanding your usable equity is important when reviewing your property portfolio.
For example:
| Item | Amount |
|---|---|
| Current property value | $900,000 |
| Outstanding mortgage | $500,000 |
| Gross equity | $400,000 |
However, gross equity is not necessarily the same as usable equity. Lenders may consider loan-to-value ratios, income, existing debts, living expenses, interest rates, rental income, lending policies and serviceability.
Having substantial equity does not automatically mean you can borrow a particular amount.
6. Review Your Investment Property Tax Position
Tax should form part of an investment property review, but it should not be the sole reason for holding an investment.
Depending on your circumstances, review:
- loan interest
- property management fees
- council rates
- land tax
- insurance
- repairs and maintenance
- depreciation
- capital works deductions
- borrowing expenses
- ownership structure
- negative gearing
- capital gains tax.
It is important to distinguish legitimate tax planning from making an investment decision simply to obtain a deduction. A tax deduction does not necessarily make an investment profitable.

7. Are You Claiming the Correct Property Tax Deductions?
Different property expenses can have different tax treatments. Some may be immediately deductible, while others may need to be claimed over several years or form part of the property’s cost base.
Check whether you have appropriate records for:
- property management fees
- loan interest
- insurance
- repairs
- land tax
- council rates
- eligible depreciating assets
- capital works.
Interest deductions can also depend on how borrowed funds are used. Maintaining clean loan structures and accurate records is therefore important.
8. Don’t Ignore Capital Gains Tax When Reviewing Your Strategy
A property can look very different financially once the potential tax consequences of selling are considered.
Before selling, consider:
- original purchase costs
- eligible capital improvements
- depreciation and capital works deductions
- selling costs
- current market value
- ownership structure
- potential capital gain
- applicable CGT concessions or discounts
- tax consequences in the year of sale.
Certain capital works deductions can also affect the CGT cost base. A potential sale should therefore generally be assessed with appropriate tax advice rather than simply comparing the purchase and expected sale prices.
9. Is Your Investment Property Ownership Structure Still Appropriate?
The ownership structure can have significant tax, asset protection, estate planning and administrative implications.
Property may be held:
- individually
- jointly
- through a company
- through a discretionary or unit trust
- through an SMSF, subject to applicable rules.
The appropriate structure depends on your circumstances and objectives.
Changing ownership after purchase can potentially trigger tax and transaction costs. If you are considering restructuring an existing investment, obtain professional advice before making changes.
10. Review Your Property’s Risk Exposure
A successful property strategy is not simply about maximising returns. It is also about understanding risk.
Consider your exposure to:
Interest rate risk – Could you manage higher rates?
Vacancy risk – What happens if the property is vacant for several weeks or months?
Property market risk – What happens if values fall?
Concentration risk – Is most of your wealth tied up in property?
Cash flow risk – Can you continue funding the property if rental income falls?
Insurance risk – Does your insurance provide appropriate protection?
Understanding these risks can help you determine whether your current portfolio remains appropriate.
11. Don’t Assume That Buying More Property Is Always the Answer
A property review may lead to a conclusion other than buying another investment.
The best strategy might be to:
- keep the existing property
- pay down debt
- refinance
- improve cash flow
- sell an underperforming asset
- diversify into other investments
- increase superannuation contributions
- build a larger cash reserve
- purchase another property.
There is no universal “right” answer. The appropriate strategy depends on your financial position, risk tolerance, investment timeframe and objectives.
12. Review Your Property Portfolio Before Buying Another Investment Property
If you are considering another property, review your existing portfolio first.
Ask:
- How much can I comfortably borrow?
- What will another property do to my cash flow?
- How will another loan affect my borrowing capacity?
- What happens if interest rates increase?
- What happens if one property becomes vacant?
- Will another property improve diversification or increase concentration risk?
- Does buying another property fit my retirement strategy?
The objective should be sustainable portfolio growth, rather than simply owning more properties.
13. Review Your Property Investment Strategy Before Retirement
As retirement approaches, the strategy that made sense during your accumulation years may need to change.
An investor in their 30s may be comfortable with higher debt, negative cash flow, a long investment timeframe and capital growth strategies.
Someone approaching retirement may instead prioritise:
- reliable income
- debt reduction
- liquidity
- lower financial risk
- diversification
- predictable cash flow.
This does not necessarily mean selling property. It means assessing whether your existing portfolio remains appropriate for the next stage of your financial life.
14. Consider Whether the Property Is Still the Right Asset
Sometimes the most useful question is not:
“How can I improve this investment property?”
It is:
“Would I buy this property again today?”
Consider its current market value, rental yield, interest rates, expected growth, ongoing expenses, location, vacancy risk and alternative investment opportunities.
If you would not purchase it today, that does not automatically mean you should sell. However, it does mean the property deserves closer examination.
15. When Should You Review Your Investment Property?
There is no single review frequency that suits every investor, but an annual strategic review can be useful, particularly when circumstances change.
Consider a review if:
- you have owned the property for several years
- your income or family circumstances have changed
- interest rates have changed significantly
- your mortgage has not been reviewed recently
- rental income or property value has changed
- you are considering another purchase
- you are approaching retirement
- your tax circumstances have changed
- you are considering selling
- you have accumulated significant equity
- you have not reviewed your strategy for several years.
Investment Property Review Checklist
A useful property investment review should consider:
| Area | Questions to Ask |
| Property value | What is the property worth today? |
| Rental income | Is the rent competitive with the current market? |
| Rental yield | What is the current gross and net yield? |
| Cash flow | How much does the property cost or contribute each year? |
| Mortgage | Is the current loan structure still appropriate? |
| Interest rate | Could the loan be refinanced or renegotiated? |
| Equity | How much equity has been created? |
| Tax | Are deductions and records being managed correctly? |
| CGT | What would happen if the property were sold? |
| Ownership | Is the current ownership structure still appropriate? |
| Insurance | Is the property adequately insured? |
| Risk | How exposed are you to vacancy, rates and property values? |
| Diversification | Is too much wealth concentrated in property? |
| Retirement | Does the property support your long-term retirement plan? |
| Future strategy | Keep, refinance, sell, reduce debt or expand? |
The Bottom Line: Your Investment Property Should Have a Purpose
An investment property should not simply be something you own because you have always owned it. Its role should be clear.
It may help build capital growth, generate income, diversify assets or provide a long-term retirement asset. As your circumstances change, however, the role of the property may need to change too.
A regular investment property review allows you to assess cash flow, financing, taxation, risk, equity and long-term goals.
The review may confirm that everything is working well. Alternatively, it may identify an opportunity to refinance, reduce debt, address a tax issue, improve diversification or sell and reallocate capital.
The important point is that doing nothing should be a deliberate decision, rather than the result of never reviewing the strategy.
Conclusion: Don’t Let Your Investment Property Strategy Run on Autopilot
Property investment is a long-term strategy, but that does not mean it should be a set-and-forget investment.
Your income, family circumstances, borrowing capacity, tax position, property value, rental income, interest rates and financial objectives can all change over time.
A regular investment property review can help determine whether your portfolio remains aligned with where you want to be in five, ten or twenty years.
For Australian property investors, the review should bring together property performance, cash flow, lending, taxation, capital gains tax, risk, diversification and retirement planning.
The goal is not necessarily to own more property.
The goal is to make sure the property you own continues to work for you.
If you have not reviewed your investment property strategy recently, speaking with your accountant, financial adviser and lending specialist may help determine whether your current approach remains appropriate and whether there are opportunities to improve your overall wealth strategy.
Frequently Asked Questions About Investment Property Reviews
How often should I review my investment property?
An annual review can be useful, with additional reviews when your income, family circumstances, borrowing position, tax situation or investment objectives change.
What should I review on an investment property?
Review the property’s current value, rental income, yield, cash flow, mortgage, interest rate, equity, expenses, tax position, insurance and risks. You should also consider whether the property still supports your long-term financial goals.
Should I sell an investment property that is underperforming?
Not necessarily. An underperforming property should be assessed in the context of your overall portfolio, tax position, potential capital growth, selling costs and alternative investment opportunities.
Is negative gearing still a good investment strategy?
Negative gearing can provide tax benefits in some circumstances, but a tax deduction does not automatically make an investment profitable. The investment should be assessed based on its overall cash flow, risk, expected return and suitability for your financial goals.
Should I refinance my investment property?
Refinancing may potentially reduce borrowing costs or provide greater flexibility, but the decision should consider the complete loan structure, fees, tax implications, serviceability and your broader investment strategy.
Should I buy another investment property?
Not automatically. Before purchasing another property, review your existing portfolio, borrowing capacity, cash flow, risk exposure and long-term goals. Increasing the number of properties is not necessarily the same as improving your investment strategy.
Can I change the ownership structure of my investment property?
Potentially, but changing ownership can have tax and transaction consequences. Professional tax and legal advice should generally be obtained before transferring an existing property between individuals or structures.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
APRA’s New 2026 Debt-to-Income Rules – What Property Buyers and Investors Need to Know
The Australian Prudential Regulation Authority (APRA) has announced a significant shift in the way banks assess mortgage risk, introducing debt-to-income (DTI) lending limits for the first time in Australia’s history. These new rules, effective 1 February 2026, place Australia in line with countries such as New Zealand, the UK, Canada and Ireland, where DTI limits have long been a tool used to cool overheated property markets and reduce systemic financial risk.
This change is expected to reshape how both property investors and home buyers approach borrowing, particularly those who rely on higher leverage to enter the market.
What APRA Is Changing in 2026
From early 2026, banks and lenders must ensure that no more than 20% of their new quarterly mortgage lending goes to borrowers whose debt-to-income ratio is six times or higher. A DTI ratio measures the size of a loan against the borrower’s gross annual income. A ratio of six, for instance, means a borrower earning $75,000 before tax could theoretically take out a mortgage up to $450,000.
The 20% cap will apply separately to owner-occupier and investment lending. Banks will not be permitted to combine these lending categories, meaning investors will be assessed against their own lending pool. APRA has included exemptions for bridging loans and construction loans, recognising that these types of lending behave differently from standard mortgage products.
Internationally, the new Australian limit is relatively generous. New Zealand’s DTI limit sits between six and seven times income, while Ireland and Canada restrict lending far more tightly. Australia’s approach suggests a desire to curb the most aggressive forms of high-debt borrowing without dramatically restricting access to credit.
How Banks Will Apply the New Rules
The new framework requires lenders to track and manage their quarterly lending volumes, ensuring that the share of high-DTI loans remains under the 20% threshold. While banks will still be permitted to issue loans above a DTI of six, they will need to be far more selective in doing so. If a bank is nearing its cap, it may become increasingly conservative, tightening assessment criteria or prioritising applicants with stronger financial profiles.
This is not the first time APRA has stepped in to control mortgage lending risk. In 2017, it imposed temporary limits on interest-only loans, which significantly changed investor borrowing patterns. Although those limits were later lifted, they demonstrated the powerful role APRA can play in shaping mortgage behaviour. The new DTI rules represent the next phase of its prudential management strategy.
What Borrowers Can Expect Under the New DTI Cap
Borrowers with a DTI below six are unlikely to notice any change to their borrowing experience. The rules are aimed at the upper end of the risk spectrum, where households are most vulnerable to interest rate rises, income shocks or market downturns.
However, borrowers with a DTI of six or higher may find that accessing credit becomes more challenging, especially if they apply during a quarter when their bank has already used most of its high-DTI allocation. In such cases, banks may approve fewer high-DTI loans, increase interest rates for this segment, or restrict access entirely until the next quarter.
Existing mortgage holders will remain unaffected unless they wish to refinance. Even then, refinancing at a DTI above six may be more difficult depending on the chosen lender’s capacity at the time.
The Impact on Property Investors
Property investors are one of the groups most likely to feel the effect of APRA’s new lending rules. Investment loans are often larger, and many investors carry multiple mortgages, pushing their DTI ratios higher than those of owner-occupiers.
The new rules may prompt banks to be more selective with investor lending, particularly for borrowers with multiple properties or high gearing. Some investors may shift their strategies, focusing on lower-priced properties, diversifying into regional markets, or reducing leverage in order to remain eligible for finance.
While APRA’s changes are designed to reduce systemic risk, they may also unintentionally reshape investing patterns, slowing the pace of aggressive portfolio expansion and reducing the number of investors who rely heavily on high leverage.
First-Home Buyers and Market Inequality
First-home buyers often borrow at higher income multiples due to smaller deposits and less equity. For some, the DTI cap may constrain borrowing capacity, particularly in capital cities where even entry-level homes require substantial loans.
This may push certain buyers toward more affordable suburbs or regional locations. International research shows that such limits can exacerbate socio-economic divides, particularly in markets like Norway and Israel, where households have been forced into longer commutes or areas with fewer opportunities.
Although APRA’s limit is comparatively flexible, this dynamic could still emerge in Australia’s more expensive property markets.
APRA’s Broader Objective
APRA’s introduction of DTI limits signals its growing concern with household debt levels and broader financial vulnerabilities. While the regulator says it does not expect the new rules to severely restrict overall mortgage lending, the move is designed to send a clear message: high-risk borrowing must be controlled before it becomes a systemic problem.
In global markets, DTI caps have proven effective at reducing household stress and preventing sharp rises in risky debt. Australia’s adoption of this policy reflects a proactive approach to maintaining financial stability, particularly after a period of rising rates and heightened cost-of-living pressure.
What This Means for the Australian Housing Market
The new rules may gradually reduce the number of highly leveraged buyers in the market, which could slow price growth in certain segments. At the same time, competition among borrowers with lower DTI ratios may intensify. Although immediate effects on the property market may be limited, the long-term implications could include more moderate price growth, greater scrutiny from lenders, and a shift in buyer behaviour toward more affordable locations.
Source: APRA
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How to Ensure Your SMSF Property Valuations Are ATO Compliant
Managing a Self-Managed Super Fund (SMSF) gives trustees greater control over retirement savings, but it also brings a heightened level of responsibility—particularly when it comes to compliance. One of the most critical compliance obligations is the accurate and timely valuation of property assets.
Whether your SMSF holds residential or commercial property, understanding valuation requirements and ensuring adherence to Australian Taxation Office (ATO) standards is essential to protect your investment and avoid regulatory breaches.
Why Property Valuation Matters for SMSF Compliance
Accurate property valuations are fundamental to complying with ATO guidelines and the Superannuation Industry (Supervision) Act 1993 (SIS Act). Each year, SMSF assets must be reported at their current market value using objective and supportable data. This ensures accurate reporting of member balances, contribution limits, and financial statements.
Failing to provide correct valuations can lead to serious consequences, such as compliance breaches, ATO scrutiny, or audit issues.
Undervaluing assets can distort fund performance, while overvaluing may inflate member entitlements and trigger tax penalties. A reliable market valuation also assists in tracking capital gains, rental returns, and the overall performance of your property portfolio.
When conducting valuations, it’s essential to consider key factors such as location, condition, size, age, renovations, and recent comparable sales. The valuation must be backed by documented evidence, whether it’s from a qualified valuer or a reputable source like a real estate agent or online service.
ATO Rules and Guidelines for SMSF Property Valuation
The ATO mandates that SMSF property valuations meet the following criteria:
- Use reliable evidence: Valuations should be based on recent comparable sales, a comparative market analysis (CMA), or a formal valuation by a registered valuer.
- Ensure independence: Valuers must be independent, not related to the fund or its members.
- Reflect year-end market value: The valuation must reflect the property’s market value as of 30 June each year.
- Revalue when appropriate: New valuations are required after significant events such as renovations, substantial market changes, or prior to selling the property.
- Seek expert guidance: While a formal valuation isn’t always mandatory, it is strongly recommended for complex or high-value properties.
Adhering to these rules ensures your SMSF remains compliant and audit-ready.
Who Can Conduct an Independent SMSF Property Valuation?
The ATO permits several independent professionals to carry out valuations, provided they are suitably qualified and impartial.
Approved valuers include:
- Registered property valuers – Preferred for high-value or complex properties, as they provide detailed, ATO-compliant reports.
- Real estate agents or appraisers – Acceptable for more straightforward properties if supported by written evidence and recent comparable sales data.
The key is independence: the valuer must not have any financial interest in the SMSF or any relationship with its members. Documentation must also be retained for at least 10 years to meet audit and record-keeping requirements.
Common Valuation Mistakes to Avoid
Even experienced trustees can make errors that jeopardize compliance. Common mistakes include:
- Using outdated or old valuations.
- Relying on related parties for property assessments.
- Failing to provide supporting evidence such as comparable sales data.
- Overlooking major changes like renovations or lease changes.
- Misreporting asset values, leading to distorted member balances.
- Avoiding these errors helps maintain audit readiness and ensures accurate fund reporting.
How to Prepare for an Audit-Ready SMSF Valuation
Preparation is key to a compliant SMSF valuation. Follow these best practices:
- Keep records up to date: Maintain all contracts, lease agreements, and past valuations.
- Collect market evidence: Secure recent sales data and independent appraisals.
- Schedule valuations in advance: Arrange updated valuations before 30 June each year.
- Engage qualified professionals: Choose valuers familiar with SMSF requirements.
- Ensure consistency: Align asset registers and financial statements with valuation figures.
An audit-ready valuation, backed by strong documentation, simplifies compliance and confirms the fund’s reporting integrity.
Trustee Responsibilities and Documentation
As an SMSF trustee, it is your legal responsibility to ensure that all property valuations are compliant with ATO guidelines. This includes:
- Retaining documentation: Keep valuation reports, supporting evidence, and related documents for at least 10 years.
- Reviewing valuations annually: Ensure market values are updated to reflect current conditions.
- Verifying independence: Confirm that valuers have no ties to the SMSF or its members.
- Collaborating with professionals: Work with qualified valuers and SMSF auditors who understand regulatory standards.
Good governance, meticulous record-keeping, and independent valuations are vital for avoiding audit issues and building confidence in your SMSF’s financial position.
Conclusion
Ensuring your SMSF property valuations are ATO-compliant is more than just a regulatory requirement—it’s a fundamental aspect of responsible fund management. By following ATO guidelines, engaging independent and qualified valuers, maintaining clear documentation, and staying vigilant with annual reviews, trustees can avoid compliance risks, protect member interests, and support the long-term success of their SMSF.
Accurate valuations not only help meet legal obligations but also contribute to informed decision-making and sustainable retirement outcomes
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How to Protect Yourself When Buying Property Off the Plan
Buying property off the plan offers the promise of securing real estate at today’s prices and time to save before settlement. But it also comes with risks—some of which have become more prominent due to legislative changes and market volatility. Here’s what you need to know to protect yourself.
What Does Buying Off the Plan Mean?
Buying off the plan means purchasing a property before it’s built—usually based on architectural drawings, floor plans, or display suites. This approach is common for apartments, townhouses, and house-and-land packages.
You’re buying based on a promise—what the developer says will be built—not on something you can physically inspect. Because of this, the contract, construction timeline, and financial protections become even more critical.
How It Works
- Deposit: Typically 5–20% upfront. Remainder is paid upon completion.
- Loan Process: Lenders assess your loan application at the beginning, but may revalue the property at settlement.
- Timeline: Construction may take 12–24 months or more.
- Stamp Duty: You might qualify for concessions depending on the state and your buyer status.
Pros of Buying Off the Plan
- Lower Upfront Costs: Small deposit and more time to save.
- Potential Stamp Duty Savings: Especially for first-home buyers or new builds.
- Tax Benefits: Depreciation deductions for investors.
- Customisation: Option to choose finishes or layouts (in some cases).
- New Build Appeal: Lower maintenance costs and premium rental potential.
- Possible Capital Growth: If market rises during construction, your equity could grow before settlement.
Cons and Risks to Watch Out For
- Construction Risk: Developer might delay, change plans, or go broke.
- Final Product May Differ: Quality or layout may not match what was promised.
- Valuation Issues: Bank may value property lower at settlement, requiring you to cover the shortfall.
- Market Changes: Property value could fall before completion.
- Vacancy Risk: Over-supply in a new development could lower rental returns.
- Strata/Body Corporate Fees: May be higher than expected due to shared amenities.
- Contract Terms: Some contracts favour the developer and offer little protection for the buyer.
- Sunset Clause Abuse: Developers may cancel contracts to resell at higher prices if allowed.
Critical Contract Considerations
- Sunset Clauses
Ensure the clause has limits. Can the developer extend the date multiple times? If so, you could be stuck indefinitely.
- Developer Exit Rights
Does the contract allow the developer to cancel unilaterally or transfer the project to another entity? If yes, you may have limited recourse.
- Funding & Pre-Sales
Check if the project relies on a minimum number of sales to proceed. If financing falls through, the project might never get off the ground.
- Legal Advice Is Essential
Work with a property lawyer experienced in off-the-plan contracts. They can spot red flags and help you understand what you’re really signing up for.
How to Protect Yourself
- Get Independent Legal Advice before signing anything.
- Understand Your Cooling-Off Rights (varies by state).
- Review the Developer’s Track Record and financial stability.
- Request Specific Completion Dates and limits on extensions.
- Clarify What Happens if the Developer Defaults or changes the development.
- Check for Government Protections such as first home buyer grants or stamp duty concessions.
Conclusion
Buying off the plan can be a great opportunity—but only when approached with caution, legal guidance, and a full understanding of your rights. Contracts can be complex and often favour the developer. To protect your deposit and avoid future disputes, it’s essential to:
- Vet the developer,
- Understand contract terms,
- Plan for financial changes,
- And most importantly, seek professional legal advice.
Being informed now can save you thousands later.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How Your Current Property Could Fund Your Next Investment
Saving for a deposit can feel daunting—especially with surging property values and day-to-day expenses. But if you already own property, there’s another path: tapping into your home equity. In Western Australia, this strategy is particularly compelling in today’s booming market.
WA Property Market Highlights (2025)
- Perth leads the nation in growth: Metro house prices jumped by around 17.1% year-on-year, with many suburbs entering the million-dollar club
- Strong rental demand: Perth’s average runtime on the market dropped, while yields climbed to around 4.4%, with rents rising about 6.4% annually
- Regional WA is even hotter: Areas like Geraldton, Bunbury, and Broome are delivering over 20% annual capital growth in some cases
- Growth is expected to continue, with forecast gains of 5–10% in 2025, supported by limited supply, strong migration, and infrastructure investment
This performance makes WA—particularly Perth and its regional centres—an appealing landscape for investors using equity to expand.
What Is Equity—and How Can You Use It?
Equity is simply the difference between your property’s current market value and what you owe on it.
Example:
- Property valued at $800,000
- Loan balance is $480,000
- Total equity = $320,000
- Lenders typically let you borrow up to 80% of the value without paying LMI (that’s $640,000)
- Minus your loan, usable equity = $160,000
This usable equity can then be put toward a deposit on an investment property.
How Much Equity Do You Need for Another Property?
You’d typically need around 20% of the new property’s purchase price for a deposit, plus extra for stamp duty, legal fees, inspections, etc. For a $550,000 investment, that’s approximately $110,000, plus additional costs—which your usable equity might just cover.
Step-by-Step: Using Your Home Equity Wisely
Here’s how finance brokers typically walk clients through the process:
- Confirm usable equity
You’ll get a formal valuation through your lender to ensure accuracy. - Assess borrowing capacity
Your finances—and potential rate hikes or rental fluctuations—are stress-tested to ensure repayments stay manageable. - Structure loans ‘tax-smart’
Your home loan stays non-deductible while the investment loan remains potentially tax-deductible. Avoid cross-collateralisation where possible to keep flexibility. - Coordinate with your accountant
This ensures your borrowing plan aligns with tax strategies and overall financial position.
WA Market-Specific Investor Tips
- Act with confidence: Stock is tight and demand in Perth and regions is high. Using equity now puts you ahead of the curve.
- Focus on yield hotspots: Regions like Bunbury and Geraldton are outperforming; rental returns and capital growth are attractive
- Mitigate risk through diversification: If Perth values plateau, strong regional areas may continue delivering solid returns.
- Proactive valuation: With rapid growth, getting an updated valuation ensures your equity calculation reflects true market value.
- Watch for election and rate shifts: Forecasted WA growth depends on stability—market sentiment may shift around policy changes
Risks and How to Mitigate Them
Building your portfolio through equity can be powerful—but deliberate:
- Over-leveraging can stretch your finances too thin. Keep buffers for rates, maintenance, and rental vacuums.
- Market shifts may cool growth—especially post-peak in some hotspots
- Interest rate changes can reduce borrowing capacity. Always project for future rate rises.
- Cross-collateral entanglement can complicate refinancing or selling later.
What If Equity Isn’t Yet Enough?
Here’s what you can still do:
- Accelerate equity: Make extra repayments or renovate to increase your property’s value.
- Restructure loans: Refinancing might improve serviceability and free more equity.
- Plan ahead: Build your position over 6–12 months to prepare for a strategic investment.
Conclusion
With Western Australia’s property market among the strongest in 2025—especially in Perth and key regional centres—using equity from your home isn’t just practical; it’s strategic. If managed carefully, this leverage can unlock significant investment returns, while also preparing you for long-term portfolio growth. Stay informed, act decisively, and lean on expert support to navigate the path ahead.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Everything You Need to Know About Inheritance Tax
When a loved one passes away, the emotional toll can be overwhelming, and the last thing you may want to focus on is taxes. However, navigating the tax implications is a crucial part of administering an estate. While Australia does not impose a death tax, there are other important tax considerations that may arise, including capital gains tax and income tax.
For instance, if the deceased owned property, capital gains tax may be applicable on the sale of that property. Similarly, income-producing assets, such as investments that continue to generate income during the administration of the estate, may have associated income tax implications.
Given the complexity of these matters, it is essential to seek professional guidance from both a legal practitioner and a tax agent. Below is a basic overview of the key tax considerations related to deceased estates in Australia, to help you better understand the process and how it may apply to your specific situation.
What is a Deceased Estate?
A deceased estate refers to the property and assets left by an individual upon their death, including both tangible assets and any outstanding liabilities. The executor of the estate is responsible for managing the administration process and ensuring that the assets are distributed according to the deceased’s wishes, as outlined in their will.
A deceased estate may also include a superannuation death benefit, which is a payment made by a superannuation fund to a dependent beneficiary or to the estate’s trustee when the fund member passes away.
The executor has a fiduciary duty to ensure that all outstanding debts and taxes owed by the deceased are settled before distributing the remaining assets to the beneficiaries. Until distribution occurs, the executor holds the estate’s assets, including any income generated posthumously, in a trust.
Does a Deceased Estate Pay Tax in Australia?
In Australia, there is no death tax. However, that does not mean a deceased estate is exempt from tax obligations.
For example, if the estate includes income-generating assets, income tax may be applicable on the income produced during the administration of the estate. Additionally, if the executor is required to sell any capital gains tax (CGT) assets, the sale could trigger a CGT liability. Furthermore, consideration should be given to whether the deceased had already satisfied tax obligations on specific components, such as superannuation death benefits, which may impact the estate’s overall tax responsibilities.
How Does Income Tax Apply to Deceased Estates?
Settling a deceased estate can be a complex and time-consuming process, often taking 6 to 12 months—sometimes even longer. During this time, it’s not uncommon for income to still flow into the deceased person’s estate.
For example, the investment property might still generate rental income, or the estate may receive a dividend from shares the deceased held.
If this is the case, the estate is treated as a trust for tax purposes and the executor must report the deceased estate income to the Australian Tax Office (ATO).
What are the Deceased Estate Tax Rates?
Based on the deceased estate tax rules that the ATO proposes, if the estate generates income while the administration process is underway, the executor must lodge an income tax return for each financial year that it takes to finalise and distribute the estate.
The taxable component of superannuation death benefits can significantly impact the tax obligations for beneficiaries and the estate. Understanding the rules around the taxable component is crucial for managing potential tax liabilities.
Generally, an executor won’t have to lodge a tax return if the total income of the estate is less than the tax-free threshold, which is currently $18,200.
In most cases, the ATO taxes undistributed income in a trust at the top marginal tax rate, but when the executor or trustee lodges the first tax return for the deceased, they can apply for a concessional tax rate—the same as the individual income tax rates.
The concessional tax rate will only apply for the first three years. If the estate is finalised later, different tax rates will apply. It’s also worth noting that deceased estates can’t benefit from tax offsets such as the low-income tax offset, and the Medicare levy won’t be payable.
Example
Meagan passed away on 2 May 2022. Her estate’s first income year will run from 3 May 2022 to 30 June 2022.
The second income year for Meagan’s estate will run from 1 July 2022 to 30 June 2023, and the third income year will be from 1 July 2023 to 30 June 2024.
If Meagan’s deceased estate earns less than $18,200 taxable income during these years, the estate won’t have to pay any tax or file a tax return. If she doesn’t benefit from the full tax-free threshold, her individual income tax rates will apply.
When Does Capital Gains Tax Apply?
Capital Gains Tax (CGT) is levied on the profit made from the sale or disposal of an asset. The capital gain is the difference between the cost of acquiring the asset and the proceeds received upon its disposal. If the asset is sold for a profit, CGT is applied to that gain.
In addition to CGT, it is important to consider the tax implications related to superannuation death benefits. The tax obligations associated with inheriting superannuation assets depend on several factors, including the beneficiary’s dependency status, the nature of the benefit (whether a lump sum or income stream), and whether the superannuation is taxable or tax-free.
Typically, assets from a deceased estate will be transferred to a beneficiary in accordance with the deceased’s wishes. The Australian Taxation Office (ATO) allows the executor to disregard CGT on any capital gain (or loss) if the asset passes:
- To the executor;
- To a beneficiary; or
- From the executor to the beneficiary.
As a result, the beneficiary will not be required to pay CGT on their inheritance unless the asset is sold more than two years after acquisition. However, various rules apply to CGT on inherited property, so it is advisable to consult with a tax professional to understand the specific obligations.
If an asset within the deceased estate is sold by the executor, rather than transferred directly to a beneficiary, to distribute the proceeds, this will trigger a CGT event for tax purposes. In this case, the standard CGT rules will apply, and the estate may be liable for CGT.
Frequently Asked Questions (FAQs)
Do I need to pay tax on inherited money in Australia?
In Australia, there is no inheritance tax. The federal inheritance tax was abolished in 1979, meaning beneficiaries are not required to pay tax on the value of assets or money inherited from a deceased person’s estate.
However, while there is no inheritance tax, other tax implications may arise depending on the nature of the inherited assets. For instance, if you inherit property and later sell it, you may be subject to capital gains tax (CGT) on any profit made from the sale.
What happens to the deceased’s debts?
Debts do not disappear when a person passes away. The executor of the estate is responsible for settling any outstanding debts using the assets of the estate before distributing the remaining assets to the beneficiaries, in accordance with the deceased’s will.
The typical process for settling debts involves:
- Identifying all outstanding debts, including mortgages, loans, and credit card balances.
- Notifying creditors of the death and providing them with the required documentation.
- Paying off debts using the estate’s assets, starting with secured debts (e.g., mortgages) and moving to unsecured debts (e.g., credit card balances).
- If the estate does not have sufficient assets to cover all debts, the executor may need to sell assets or negotiate with creditors.
- Once all debts are settled, the remaining assets can be distributed to beneficiaries.
The executor must manage debts properly to ensure the estate is administered correctly and beneficiaries receive their entitlements.
How long does it take to settle a deceased estate in Australia?
The time it takes to settle a deceased estate in Australia can vary significantly based on factors such as:
- The size and complexity of the estate
- The clarity and validity of the deceased’s will
- The number and location of beneficiaries
- Any disputes or challenges to the will
- The efficiency of the executor in managing the estate
On average, it takes around 6 to 12 months to settle a deceased estate, but in more complex cases, such as when there are multiple properties, international assets, or many beneficiaries, the process may extend to several years.
The main stages of settling a deceased estate typically include:
- Obtaining a grant of probate or letters of administration
- Identifying and valuing the estate’s assets
- Paying any outstanding debts and taxes
- Distributing the remaining assets to beneficiaries
- Finalising the estate and providing a final accounting to beneficiaries
Executors should keep beneficiaries informed throughout the process and seek professional advice from legal practitioners and tax agents to ensure the estate is administered in compliance with Australian laws.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Inbound Financing for Property Development – ATO Crackdown
The Australian Taxation Office (ATO) has heightened its scrutiny of certain businesses, particularly in the property and construction sectors, over concerns that they are claiming excessive debt deductions and shifting profits offshore. The ATO has specifically issued warnings to privately owned and wealthy groups that use inbound related-party financing—where a business receives a loan from an overseas related entity or associate to acquire or develop property.
In such cases, the ATO has reminded these businesses to carefully consider the application of transfer pricing rules, which can significantly impact their tax obligations. The transfer pricing rules require businesses to ensure that cross-border transactions between related parties, such as loans, are conducted on “arm’s length” terms—terms that would apply if the parties involved were unrelated and operating independently.
The ATO’s View on the “Arm’s Length Principle”
The ATO expects businesses to assess whether the terms of their financing arrangements, particularly with related overseas entities, meet the arm’s length principle. This means the terms—such as interest rates, repayment schedules, and other conditions—should reflect what would be agreed upon by unrelated parties in a similar situation.
To demonstrate compliance with the arm’s length principle, businesses must:
- Clearly explain their funding arrangements, including how and why they chose specific financing options.
- Maintain documentation and evidence to show that the financing terms are commercially reasonable and consistent with market conditions.
- Ensure that the structure of their funding—whether debt, equity, or a mix of both—is properly documented and justified.
The ATO expects businesses to be able to explain their financing decisions not only at the time of the initial arrangement but also when refinancing takes place. Businesses should also demonstrate the commercial rationale behind the chosen funding options and be prepared to provide supporting evidence for ongoing compliance.
Factors that Attract the ATO’s Attention
The ATO has outlined several factors that could trigger closer examination of related-party financing arrangements, particularly when a business has significant cross-border loans or exhibits certain tax behaviours. Key warning signs include:
- Thinly capitalised operations: When a business has a high level of debt relative to equity, particularly if the funding appears to be debt but is structured like equity.
- Unrealistic tax outcomes: Low or minimal taxable income despite significant related-party financing, or tax outcomes that seem inconsistent with the business’s actual operations.
- Lack of evidence supporting arm’s length terms: If a business cannot demonstrate that the financing terms are in line with what would be agreed upon between independent parties, it may attract scrutiny.
Key Red Flags in Related-Party Financing Arrangements
The ATO will pay particular attention to the following aspects of related-party loans:
- Subordinated debt: Where the loan is priced as subordinated debt, but no senior debt is in place, or other more reasonable funding options—such as additional senior debt or equity—were available.
- Funding structure misalignment: If the funding structure does not align with the business’s financial needs or the project’s term. For example, if a loan term exceeds the duration of the property development or investment phase.
- Questionable interest deductions: Interest expenses that are claimed on related-party loans but seem excessive relative to the viability of the investment or development could be flagged. This could include situations where the loan’s interest payments are expected to be unreasonably high, casting doubt on the project’s profitability.
- Currency mismatches: Loans that are not denominated in the operating currency of the Australian borrower may draw attention, as this can lead to higher interest deductions and potentially inappropriate tax benefits.
- Deferred interest payments: Related-party loans where interest payments are deferred or credited, even when the borrower has the financial capacity to make the payments, could be flagged by the ATO as a red flag for tax avoidance.
- Unpaid principal and interest: The ATO will monitor cases where related-party loans have unpaid principal or accrued interest beyond the investment or development period, particularly if the debt isn’t repaid after the sale of the property or once the property begins generating sufficient cash flow.
Ensuring Compliance
To avoid scrutiny from the ATO, businesses engaged in inbound related-party financing for property development should be proactive in demonstrating that their financing arrangements comply with the arm’s length principle. This includes:
- Structuring loans in a commercially realistic way, with terms that would be agreed upon between independent entities.
- Keeping thorough documentation of all financing decisions and ensuring that the terms of the loan are backed by evidence of market comparability.
- Regularly reviewing financing arrangements to ensure ongoing compliance with transfer pricing rules.
The ATO is particularly focused on ensuring that property developers and investors are not using related-party financing to shift profits or gain excessive tax benefits. Adhering to the arm’s length principle and maintaining transparent, well-documented financing practices will help businesses avoid potential tax audits and penalties.
Conclusion
As the ATO intensifies its scrutiny of inbound related-party financing in the property sector, businesses need to ensure their funding arrangements comply with the transfer pricing rules. By adhering to the arm’s length principle, businesses can reduce the risk of attracting the ATO’s attention and avoid potential tax liabilities. Maintaining transparent, well-documented financing structures will not only protect businesses from scrutiny but also help them stay compliant with Australian tax laws in the long term.
Source: ATO
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
How a Potential Interest Rate Reduction Could Change Your Property Investment Strategy in Australia
Interest rates play a pivotal role in shaping the dynamics of property investment in Australia. As the Reserve Bank of Australia (RBA) evaluates economic indicators, a potential interest rate reduction can have significant implications for investors. Understanding these impacts can help property investors refine their strategies to maximize returns and mitigate risks.
Understanding Interest Rates and Their Impact
Interest rates affect the cost of borrowing, influencing how much investors can afford to pay for properties. A reduction in interest rates typically lowers mortgage repayments, increasing cash flow and making property purchases more accessible. For investors, this means enhanced purchasing power, as the same amount of money can now secure a larger or more valuable asset.
Enhanced Cash Flow
One of the most immediate effects of an interest rate reduction is improved cash flow. Lower interest payments mean that investors retain more income from rental properties. This surplus can be reinvested into additional properties, renovations, or saved for future opportunities. Improved cash flow is especially beneficial for investors relying on rental income to cover mortgage repayments and other expenses.
Greater Affordability and Increased Demand
With interest rates lower, more buyers may enter the market, leading to increased demand for properties. This heightened demand can drive property prices up, creating both opportunities and challenges for investors. Those looking to buy may find it beneficial to act quickly to secure properties before prices rise further. Investors should also be prepared for potential competition in the market, which may necessitate a reassessment of acquisition strategies.
Revising Investment Strategies
A shift in interest rates compels investors to re-evaluate their strategies. Here are several key areas where adjustments may be necessary:
- Property Selection: With lower borrowing costs, investors might consider upgrading their target property types. For example, they may move from entry-level apartments to more substantial family homes or multi-unit developments. A focus on properties in high-demand areas or those with development potential could yield significant returns.
- Diversification: An interest rate reduction may encourage diversification into different property markets or asset classes, such as commercial real estate or rural investments. By spreading investments across various sectors, investors can mitigate risks associated with market fluctuations and enhance overall portfolio performance.
- Increased Leverage: Lower interest rates create a conducive environment for leveraging existing equity. Investors can refinance properties to access additional capital for new purchases or renovations, enabling them to scale their portfolios faster. However, it’s essential to weigh the risks associated with increased debt against potential rewards.
- Focus on Long-term Investments: With the potential for sustained low-interest rates, investors may shift their focus towards long-term investment strategies. This could involve purchasing properties in growth corridors that are likely to appreciate over time or investing in developments that promise substantial future returns.
- Emphasis on Cash Reserves: While lower rates improve cash flow, it’s crucial for investors to maintain adequate cash reserves. Economic conditions can change rapidly, and having liquidity allows for flexibility in navigating unexpected expenses or market shifts. Investors should prioritize building a financial buffer to weather potential downturns.
Market Timing and Opportunity
Timing the market can be challenging, but a reduction in interest rates might present unique opportunities. Savvy investors can take advantage of softer market conditions, such as during economic slowdowns, to secure properties at lower prices. Understanding local market trends and conditions will be crucial in identifying the right moments to buy or sell.
Risk Management
While the prospects of a lower interest rate can be enticing, it’s essential to remain cautious. Increased borrowing can lead to over-leveraging, which poses risks if market conditions shift. Investors must ensure they have a comprehensive risk management plan, considering factors like property vacancy rates, maintenance costs, and changes in rental demand.
Conclusion
A potential interest rate reduction in Australia can profoundly impact property investment strategies. Enhanced cash flow, increased affordability, and the opportunity for diversification can provide significant advantages for investors. However, it’s vital to approach these changes with careful consideration and a strategic mindset. By adapting to shifting economic conditions and maintaining a long-term focus, property investors can position themselves to thrive in a dynamic market landscape. As always, thorough research, professional advice, and prudent financial management remain key components of successful property investment.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Home Loan Pre-Approval: A Guide to Getting Started
Pre-approval is often the first step for those embarking on the journey to homeownership. While it’s not strictly necessary, securing pre-approval can alleviate stress and provide a clear understanding of your borrowing power. This confidence can be invaluable when making offers on properties that fit your budget. Here’s what you need to know about obtaining pre-approval before diving into the property market.
What is Home Loan Pre-Approval?
Home loan pre-approval, also known as conditional approval, is a preliminary assessment from a lender indicating how much they are willing to lend you for your home purchase. This process involves a basic review of your financial situation, rather than a comprehensive investigation, allowing you to gauge your borrowing capacity without committing to a loan just yet.
While pre-approval gives you a ballpark figure for your borrowing potential, it’s important to remember that it does not guarantee final loan approval. Factors such as taking on new debt or discovering additional information during the application process could still lead to a decline.
Steps to Get Pre-Approved for a Home Loan
- Apply Online: Start your pre-approval process by applying online with your chosen lender.
- Initial Contact: Your lender will reach out to discuss the next steps in the process.
- Submit Documentation: Provide the necessary documents to verify your application. Promptly answer any questions to expedite the process and ensure accuracy.
- Receive Pre-Approval Letter: If approved, you’ll receive a letter outlining the conditions of the loan, including details like the interest rate and loan term.
Documentation Needed for Pre-Approval
Your lender will require specific documents to evaluate your borrowing capacity. Although requirements may vary by lender, you’ll generally need to provide:
- Proof of Identity: Certified copies of identification documents.
- Proof of Employment and Income: Payslips, payment summaries, or statements from the ATO or Centrelink.
- Evidence of Deposit and Savings: Bank statements showing your savings.
- Expense Information: Details on your regular expenses, such as bills and bank statements, to assess repayment ability.
- Current Debts: Documentation of existing debts, including personal loans, car loans, or credit card balances.
- Current Assets: Information about any property, investments, superannuation, or vehicles you own.
When to Seek Pre-Approval
Consider obtaining pre-approval when you are serious about purchasing property. Take time to research the market, current interest rates, and your potential deposit amount to create a budget.
Keep in mind that pre-approval is usually valid for 3 to 6 months. Changes in your financial situation or the property market may affect your approval status. Additionally, pre-approval applications may be recorded on your credit history, impacting future credit checks. Therefore, it’s wise to time your application for when you are genuinely ready to start house hunting. If you’re not prepared yet, use the time to consolidate any debts or save for a larger deposit.
The Benefits of Pre-Approval
Pre-approval can instill confidence as you begin your home buying journey without formal loan commitments. It may also help streamline the final approval process when you find the right property. By understanding your borrowing capacity upfront, you’ll be better positioned to make informed decisions and offers, setting you up for success in the competitive property market.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Understanding the Tax Implications of Renting Out Your Holiday Home
Renting out your holiday home can be a lucrative way to generate additional income, but it’s important to understand the tax implications that come with it. In Australia, the Australian Taxation Office (ATO) has specific guidelines for property owners, and being aware of these can help you manage your tax responsibilities effectively.
- Assessing Rental Income
When you rent out your holiday home, any income you earn from the rental is considered assessable income. This means it must be declared on your tax return. The ATO requires you to include all rental payments you receive, which can vary depending on whether you’re renting out the property full-time or for short stays.
- Claiming Deductions
One of the advantages of renting out your holiday home is the ability to claim certain deductions against your rental income. Common deductible expenses include:
- Mortgage Interest: If you have a loan on the property, the interest portion of your mortgage repayments can be claimed.
- Property Management Fees: Fees paid to real estate agents for managing your rental property are deductible.
- Maintenance and Repairs: Costs for repairs and maintenance that are necessary to keep the property in a rentable condition can also be claimed. However, improvements or renovations typically cannot be deducted.
- Utilities and Council Rates: Any expenses related to utilities and council rates during the period the property is rented out are deductible.
- Depreciation: You can claim depreciation on the building and any furniture or fittings in the property. Engaging a quantity surveyor to provide a depreciation schedule can be beneficial.
- Apportioning Expenses
If you use the property for both personal and rental purposes, you must apportion your expenses accordingly. For example, if you rent the property for 20 weeks a year and use it personally for 32 weeks, you can only claim a portion of your expenses related to the rental period. The ATO provides specific formulas and guidance on how to calculate these claims.
- Capital Gains Tax (CGT)
When you sell your holiday home, you may be subject to Capital Gains Tax (CGT) on any profit you make from the sale. However, if the property has been your main residence for part of the time you owned it, you may qualify for a partial exemption. The rules surrounding CGT can be complex, so it’s advisable to consult with a tax professional to understand your specific situation.
- Tax Time Considerations
When tax time arrives, it’s crucial to keep thorough records of all income and expenses related to your holiday home. This includes receipts, invoices, and any correspondence related to your rental activities. Good record-keeping not only ensures you can substantiate your claims but also makes the process smoother when filing your tax return.
- Short-Term Rentals and Special Considerations
If you are considering renting out your holiday home as a short-term rental through platforms like Airbnb, there are additional considerations:
- GST Registration: If your rental turnover exceeds the GST registration threshold, you may need to register for GST, which comes with its own set of compliance requirements.
- Local Council Regulations: Some local councils have specific regulations regarding short-term rentals, including zoning laws and the need for permits. It’s essential to check your local laws before proceeding.
- Conclusion
Renting out your holiday home can provide a valuable source of income, but it’s essential to understand the associated tax implications. By keeping accurate records, claiming eligible deductions, and being aware of your tax obligations, you can make the most of your investment while staying compliant with Australian tax laws. For personalized advice, consider consulting with a tax professional who can guide you through the nuances of your specific circumstances.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.