




Are Family Trusts Still Worth It in Australia? What the 2026 Tax Changes Mean for Families and Business Owner
For decades, discretionary family trusts have been popular with Australian families, investors and business owners. They can provide flexibility when distributing income, support asset protection and succession planning, and help families manage business and investment assets across generations.
However, the environment surrounding family trusts is changing.
The 2026–27 Federal Budget proposes a 30% minimum tax on discretionary trust taxable income from 1 July 2028, together with transitional rollover relief for eligible businesses and taxpayers considering restructuring. At the same time, the ATO continues to scrutinise trust distributions, section 100A arrangements, family trust elections, franking credits and Division 7A issues.
So, are family trusts still worth it?
The answer is: possibly, but the reasons for using one need to be carefully considered.
A family trust should no longer be established simply because it is considered a “tax-effective structure”. Tax, asset protection, succession, cash flow, compliance costs, investment strategy and long-term family objectives all need to be considered.
What Is a Discretionary Family Trust?
A discretionary trust is a structure where a trustee holds assets for a group of beneficiaries. Unlike a company, beneficiaries generally do not have fixed ownership percentages. Subject to the trust deed and tax law, the trustee can decide how income and capital are distributed among eligible beneficiaries.
This flexibility has historically made family trusts attractive for:
- family businesses
- investment portfolios
- property investments
- wealth accumulation
- intergenerational wealth planning
- asset protection strategies
- distributing income between family members.
However, flexibility also creates complexity. Trusts must be properly established and administered, resolutions need to be valid, distributions correctly documented and tax consequences understood.
Why Have Family Trusts Been Popular in Australia?
Income Distribution Flexibility
Subject to the trust deed and tax law, a discretionary trust can potentially distribute different types of income to different beneficiaries. This can provide flexibility where family members have different taxable incomes.
However, the proposed 30% minimum tax from 1 July 2028 may reduce the tax benefit of income splitting for trusts within the new rules.
Asset Protection
Trusts can potentially provide an additional layer of separation between business or investment assets and individuals.
However, a trust is not an absolute asset protection shield. Protection depends on the circumstances, trustee arrangements, guarantees, insolvency law and how the trust has been operated.
Succession Planning
A properly structured trust can provide flexibility when control and economic benefits need to be managed across generations. This can be particularly relevant for families with operating businesses, investment portfolios, property and significant accumulated wealth.
Long-Term Wealth Management
A family trust can provide a framework for holding and managing family assets over an extended period. However, the structure should be reviewed as family circumstances and wealth objectives change.
The 2026 Budget Changes the Family Trust Equation
The most significant recent development is the Federal Government’s proposed 30% minimum tax on discretionary trusts.
Under the proposal, from 1 July 2028, trustees of discretionary trusts within the rules will pay a minimum tax of 30% on taxable income. Beneficiaries will continue to declare their trust income, with non-corporate beneficiaries receiving non-refundable credits for tax paid by the trustee.
The Government says the reform is intended to reduce the tax advantage created by income splitting through discretionary trusts.
The proposal includes exclusions for certain categories, including:
- fixed and widely held trusts
- complying superannuation funds
- special disability trusts
- deceased estates
- charitable trusts
- certain primary production income
- certain income relating to vulnerable minors
- certain non-resident withholding tax amounts
- certain testamentary trust assets existing at the time of announcement.
Importantly, this is not a 30% minimum tax on every type of trust. It specifically targets discretionary trusts within the proposed rules.
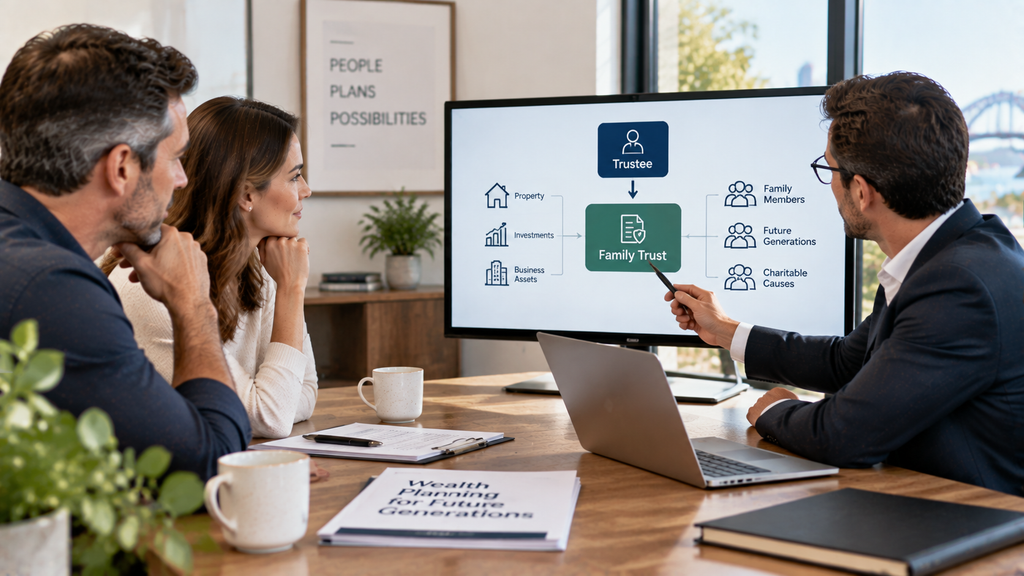
What Does the 30% Minimum Tax Mean for Family Trusts?
The proposed changes could significantly alter the tax outcomes for some discretionary trusts.
Historically, a family trust may have distributed taxable income among beneficiaries with lower marginal tax rates. From 1 July 2028, the proposed minimum tax could reduce the benefit of this strategy for trusts within scope.
However, the impact will depend on each trust’s circumstances. The Government estimates that many small businesses will not face an additional tax liability in every year.
There is therefore no reason for every family trust to be dismantled simply because of the Budget announcement. Trustees should instead model future tax outcomes based on their expected income, beneficiaries and distribution strategy.
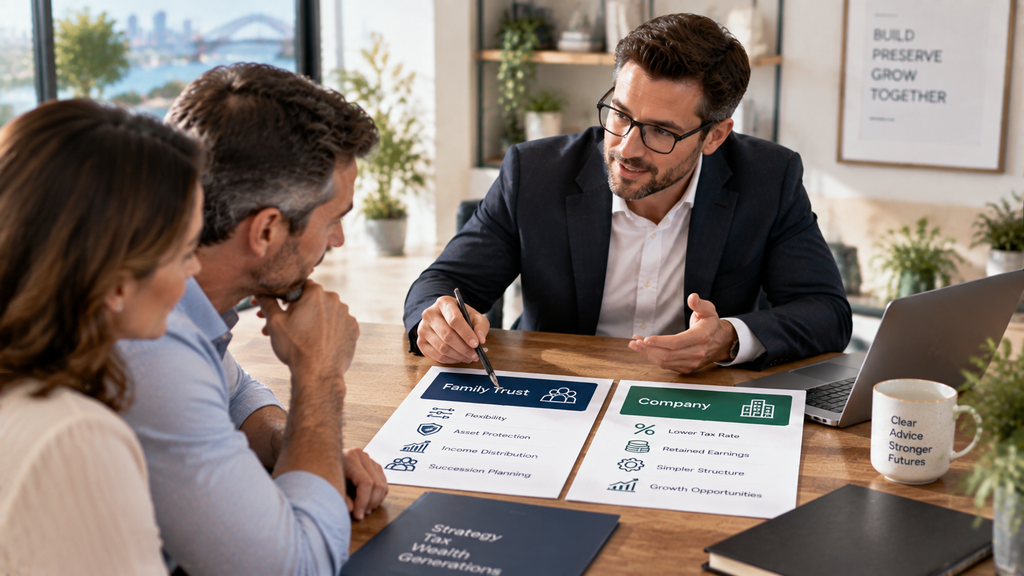
Should You Move Your Family Trust Into a Company?
The proposed changes may make companies more attractive for some families and businesses, particularly where profits are intended to be retained and reinvested.
However, a company is not automatically better than a trust. A company has shareholders with defined ownership interests, while a discretionary trust operates differently and can provide greater distribution flexibility.
Moving existing assets can also create tax, legal and transaction consequences. The decision should therefore be based on a detailed comparison rather than simply comparing the proposed trust minimum tax with the company tax rate.
New Rollover Relief Could Make Restructuring Easier
The 2026 Budget proposes a three-year period from 1 July 2027 to assist eligible small businesses and others who choose to restructure from discretionary trusts into structures such as companies or fixed trusts.
The proposed relief is intended to reduce income tax and CGT consequences that might otherwise arise.
However, restructuring may still involve:
- stamp duty
- financing and lender requirements
- asset protection
- legal ownership
- trust deeds
- shareholder arrangements
- estate planning
- Division 7A
- future distributions
- accounting and administration.
The rules should be assessed once legislation and detailed requirements are settled.
Family Trust Elections: Why They Matter
A Family Trust Election (FTE) can provide access to certain tax concessions, including benefits involving franking credits and tax losses in appropriate circumstances.
However, an FTE also restricts distributions outside the relevant family group.
The ATO confirms that Family Trust Distribution Tax (FTDT) is imposed at 47% where the relevant rules apply to distributions outside the specified individual’s family group.
This makes family trust elections particularly important during succession planning and restructuring.
What Happens If a Family Trust Distributes Outside the Family Group?
This can become expensive.
If a trust has made an FTE and distributes to an entity outside the relevant family group, FTDT may apply at 47%. A $100,000 distribution caught by the rules could therefore potentially result in $47,000 of tax.
Trustees should not assume that a distribution between related entities is automatically permitted. Family trust elections and family groups need to be reviewed before significant distributions or restructures.
Intergenerational Wealth Transfers Require Careful Planning
Succession planning can become complicated when a family has multiple trusts, companies and beneficiaries.
For example:
- a parent may be the specified individual of one trust
- an adult child may control another trust
- companies may sit beneath different trusts
- investment assets may be held across multiple entities.
A commercially sensible distribution can still have unexpected tax consequences if family trust elections and family groups are not properly considered.
What Is Section 100A and Why Does It Matter to Family Trusts?
Section 100A can apply where a beneficiary is made presently entitled to trust income, but another person receives the benefit as part of a reimbursement arrangement.
The ATO has published Taxation Ruling TR 2022/4 and Practical Compliance Guideline PCG 2022/2 outlining its approach.
Arrangements that may attract scrutiny include situations where:
- a beneficiary receives a distribution but does not receive the economic benefit
- income is redirected to another person
- arrangements are designed to achieve a lower tax outcome
- trust entitlements do not reflect the beneficiary’s economic position.
Trustees should maintain records explaining the transactions and why beneficiaries dealt with their entitlements as they did.
Why Section 100A Matters for Family Businesses
Section 100A can be particularly relevant where trusts distribute income among parents, children, companies and other related entities.
A distribution should not be treated simply as an accounting entry. There should be a clear understanding of:
- who was made presently entitled
- why the distribution was made
- what happened to the entitlement
- who ultimately benefited
- what agreements existed
- whether the arrangement has a genuine commercial or family purpose.
Good documentation is increasingly important.
The Bendel Case and Division 7A: What Trusts Need to Know
The Bendel litigation has attracted significant attention among family trust advisers and business owners. The Federal Court considered whether an unpaid present entitlement from a trust to a private company beneficiary could constitute a “loan” for Division 7A purposes.
The Court rejected the Commissioner’s construction of the relevant definition of “loan” in the provision considered.
However, the broader implications remain important. Trust distributions to corporate beneficiaries should not be treated casually. Where income is distributed to a company but cash is not physically paid across, trustees should carefully consider the trust deed, accounting treatment, Division 7A and applicable ATO guidance.
What About Franking Credits and the 45-Day Holding Rule?
Franking credits can be valuable to family trusts and beneficiaries, but eligibility rules apply.
Broadly, the holding period rule requires shares to be held “at risk” for at least 45 days during the relevant qualification period, subject to exceptions.
This can matter where a trust has a corporate beneficiary or investment portfolio containing dividend-paying shares. Failing the relevant requirements can affect access to franking credit benefits.
Are Family Trusts Still Worth It for Small Business Owners?
For many small business owners, the answer may still be yes, but the calculation is changing.
A family trust may remain useful where:
- income distribution flexibility is important
- the family has multiple beneficiaries
- succession planning is a priority
- asset protection is important
- investment assets are being accumulated
- the trust is expected to operate across generations
- compliance costs are justified by the benefits.
However, the proposed minimum tax means the tax advantages may be less significant for some families from 2028 onwards.
When Might a Company Be More Attractive Than a Family Trust?
A company may be worth considering where the main objective is to retain profits and reinvest them.
This may suit businesses that:
- are growing rapidly
- want to retain earnings
- are reinvesting profits
- may require external finance
- plan to introduce investors
- want clearly defined ownership interests.
A company does not provide the same distribution flexibility as a discretionary trust. The decision should therefore be based on long-term objectives rather than tax rates alone.
Should You Close Your Existing Family Trust?
Not necessarily.
The proposed 30% minimum tax does not mean every family trust should be closed.
Before making a decision, consider:
How much income does the trust generate?
A trust with modest income may be affected differently from one distributing substantial business or investment income.
Who receives the income?
If distributions are already made to beneficiaries with tax rates of 30% or higher, the impact may differ from a trust relying heavily on lower-tax-rate beneficiaries.
Is the trust retaining wealth?
The proposed changes may make the choice between a trust and company more important where income is being accumulated and reinvested.
What assets does the trust own?
Business, property and investment assets can each create different tax and structural considerations.
What is the family’s long-term succession plan?
A structure that works today may not be appropriate for the next generation.
Don’t Forget the Cost of Changing an Existing Structure
Moving from a family trust to a company is not necessarily straightforward.
Transferring assets can potentially create:
- capital gains tax
- stamp duty
- refinancing costs
- legal and accounting costs
- transaction costs
- changes to asset protection
- estate planning consequences.
Proposed rollover relief may reduce some tax consequences for eligible restructures, but it should not be assumed that every transfer will qualify.
Existing structures should therefore be reviewed before any transfer takes place.
What Should Family Trust Owners Do Now?
1. Review Your Trust Deed
Make sure the deed remains appropriate for current circumstances and intended distributions.
2. Review Your Family Trust Election
Confirm the specified individual, relevant family group, any interposed entity elections and whether planned distributions could trigger FTDT.
3. Review Your Distribution Strategy
Analyse who receives trust income and why, and consider how the proposed 30% minimum tax could affect future distributions.
4. Review Corporate Beneficiaries
If income is distributed to a company, review how those entitlements are dealt with and consider Division 7A implications.
5. Review Section 100A Risk
Make sure distributions reflect genuine arrangements and that appropriate records are maintained.
6. Model the 2028 Tax Position
Calculate what the proposed minimum tax could mean based on expected income and distributions.
7. Compare Trust and Company Structures
If the trust primarily retains income for investment, compare future tax and administration outcomes with a company or other suitable structure.
8. Review Succession Planning
Consider who should control the trust and assets in the future and how wealth is intended to pass between generations.
Family Trust vs Company: Which Structure Is Better?
There is no universal answer.
| Consideration | Family Trust | Company |
|---|---|---|
| Income distribution flexibility | Generally high | More limited |
| Fixed ownership | No | Yes |
| Retaining profits | Can be less straightforward | Often more straightforward |
| Succession planning | Potentially flexible | Share ownership can be transferred |
| Asset protection | Potentially useful | Potentially useful, but circumstances matter |
| Administration | Can be complex | Generally structured and formal |
| Tax planning | Flexible but increasingly regulated | More predictable in many circumstances |
| Future distributions | Flexible subject to trust rules | Dividends generally linked to share ownership |
| Intergenerational planning | Potentially strong | Can work well with appropriate share structures |
| 2028 proposed trust minimum tax | Potential impact for discretionary trusts | Not subject to the proposed discretionary trust minimum tax |
This table is a starting point, not a substitute for professional advice.
Family Trusts and Intergenerational Wealth Planning
One area where trusts may continue to have significant strategic value is intergenerational wealth planning.
The Budget proposes excluding certain income from assets of testamentary trusts existing at the time of announcement from the proposed discretionary trust minimum tax. Testamentary trusts, however, are fundamentally different from ordinary discretionary family trusts.
For families with substantial wealth, estate planning may involve:
- wills
- testamentary trusts
- superannuation
- companies
- family trusts
- investment structures
- control arrangements
- beneficiary planning.
The objective is to create a structure that works while the current generation is alive and when control and wealth pass to the next generation.
The Real Question Is Not “Trust or Company?”
The more useful question is:
What do you want the structure to achieve?
Consider:
- Will profits be distributed or retained?
- Who needs access to income?
- Who should control the assets?
- Who should ultimately benefit?
- Is asset protection important?
- Are significant investment assets involved?
- Is the business growing?
- Will external investors be required?
- Is succession planning important?
- What will the structure cost to maintain?
- What could it cost to change later?
These questions are more important than simply comparing tax rates.
Conclusion: Are Family Trusts Still Worth It?
Yes, family trusts can still be worth it — but they should no longer be viewed as an automatic tax-saving structure.
The proposed 30% minimum tax on discretionary trusts from 1 July 2028 represents a significant change to Australia’s trust tax environment. Proposed rollover relief may also give eligible businesses an opportunity to restructure during a three-year period beginning 1 July 2027.
At the same time, the ATO continues to scrutinise trust distributions, section 100A arrangements, family trust elections, franking credits and corporate beneficiary arrangements.
For some families, the flexibility, asset protection and succession planning benefits of a discretionary trust may continue to outweigh the additional tax and compliance complexity. For others, particularly businesses seeking to retain and reinvest profits, a company or another structure may become more attractive.
The important point is not to make a rushed decision based on the proposed 30% rate alone.
Changing an established structure can have significant tax, legal, financing and transaction consequences. Family trust owners should instead undertake a strategic review covering tax, distributions, asset protection, business structure, succession, investment strategy and future cash-flow requirements.
The question is no longer simply:
“How much tax does my family trust save?”
It is:
“Is this still the right structure for how my family wants to own, grow, control and ultimately pass on its wealth?”
That is the question worth answering before making any structural changes.
Frequently Asked Questions About Family Trusts in Australia
Are family trusts still worth it after the 2026 Budget?
They can be. The proposed 30% minimum tax affects discretionary trusts within scope from 1 July 2028, but it does not mean every family trust will be worse off or should be closed. The impact depends on the trust’s income, distributions, assets and long-term objectives.
Will all family trusts pay 30% tax from 2028?
No. The proposed minimum tax applies to discretionary trusts within the scope of the measure. Certain trusts and types of income are specifically excluded.
Should I close my family trust before 2028?
Not automatically. Closing or restructuring a trust can create CGT, stamp duty, financing and other consequences. A detailed review should be undertaken before deciding.
Is a company better than a family trust?
It depends on your circumstances. A company may be attractive where profits are retained and reinvested, while a discretionary trust can provide greater distribution and succession flexibility. The right choice depends on the purpose of the structure.
What is the Family Trust Distribution Tax rate?
Where the relevant family trust rules apply to a distribution outside the specified individual’s family group, Family Trust Distribution Tax can apply at 47%.
What is Section 100A?
Section 100A can apply to certain trust distribution arrangements where a beneficiary’s entitlement arises from a reimbursement agreement and another person receives the benefit. The ATO has published specific guidance on its compliance approach.
What is the Bendel case?
Bendel concerned whether certain unpaid trust entitlements to a private company beneficiary constituted a “loan” for Division 7A purposes. The Federal Court rejected the Commissioner’s construction of the relevant definition of “loan”.
Should I restructure my family trust into a company?
Possibly, but the decision should be based on your circumstances and long-term objectives. The Government has proposed expanded rollover relief for eligible restructures from 1 July 2027, but the detailed requirements need to be considered before acting.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Testamentary Trusts and the Proposed 30% Trust Tax
If you have a testamentary trust in your Will, or you’re thinking about including one, you may have heard about the Government’s proposal to introduce a 30% minimum tax on discretionary trust income.
The Government has announced that testamentary trusts are intended to be exempt from these proposed rules. However, the legislation has not yet been passed, and some important details are still being worked through by Treasury.
While there is no need to make rushed decisions, now is a good time to understand what has been proposed and what it could mean for your estate planning.
What Is a Testamentary Trust?
A testamentary trust is a trust created through your Will. It doesn’t exist while you’re alive, it only comes into effect after your death when your estate is administered.
Many Australians use testamentary trusts because they can:
- Protect family assets.
- Provide flexibility in how money is distributed.
- Help protect beneficiaries from financial risk.
- Assist with blended family arrangements.
- Offer tax benefits, particularly where young children are beneficiaries.
For families with investment properties, businesses or significant wealth, testamentary trusts are often an important part of an estate plan.
What Is the Government Proposing?
In July 2026, Treasury released a consultation paper outlining how a proposed 30% minimum tax on discretionary trust income could operate from 1 July 2028.
The proposal aims to reduce the tax advantages of distributing trust income to adults on lower tax rates. Importantly, Treasury has confirmed that income from genuine testamentary trusts is expected to be exempt from the new tax.
However, the detailed rules have not yet been finalised and may change before any legislation is passed.
Why Are Testamentary Trusts Being Exempt?
The Government recognises that testamentary trusts are primarily used for estate planning, not for tax minimisation.
These trusts help families:
- Look after children.
- Protect vulnerable beneficiaries.
- Manage inheritances over many years.
- Preserve family wealth.
Because of these legitimate purposes, Treasury has indicated that testamentary trusts should continue receiving favourable treatment.
Is the Exemption Automatic?
Not necessarily. Treasury has proposed that certain conditions may apply before a testamentary trust qualifies for the exemption. These may include:
Assets must come from the deceased person’s estate
The trust should mainly contain assets inherited from the deceased. If unrelated assets are later transferred into the trust, those assets may not qualify for the exemption.
The trust must be genuinely established through a Will
Treasury is also considering whether there should be limits on very broad beneficiary classes that extend well beyond normal family estate planning. These issues are still being consulted on and have not yet been finalised.
Do Existing Wills Need to Be Changed?
For most people, no. Having an older Will does not automatically mean you will lose the exemption. In fact, Treasury has not yet decided exactly when a testamentary trust will be regarded as being “established.”
Possible dates being considered include:
- The date the Will is signed.
- The date of death.
- The date probate is granted.
- The date assets are transferred into the trust.
Until these rules are settled, there is generally no reason to rewrite your Will solely because of these proposals.
What Should People with Existing Testamentary Trust Wills Do?
If you already have a testamentary trust in your Will, the best approach is simply to review your estate plan as you normally would. Consider whether:
- Your executor is still appropriate.
- Your trustee appointments remain suitable.
- Your beneficiaries are current.
- Your family circumstances have changed.
- Your assets have changed significantly.
If your Will already needs updating for personal reasons, your solicitor can also consider the proposed tax changes at the same time.
What Does This Mean for Executors?
If you are currently acting as an executor, your legal responsibilities do not change because of the consultation paper. However, if a testamentary trust will be created, you should seek professional advice before transferring estate assets into the trust, particularly if the new legislation is introduced before the estate is fully administered.
What Should Trustees Do?
Trustees of existing testamentary trusts do not need to make immediate changes.
Instead, they should continue to:
- Keep accurate financial records.
- Record where trust assets originated.
- Maintain proper trust accounts.
- Continue meeting annual tax and reporting obligations.
Good record keeping may become increasingly important if the proposed legislation is enacted.
Practical Tips
While nothing has changed yet, this is a good opportunity to:
- Review your Will every few years.
- Keep your estate planning documents up to date.
- Review trustee and executor appointments.
- Check your superannuation death benefit nominations.
- Speak with your solicitor or accountant if your circumstances have changed.
Good estate planning is about protecting your family, not simply reducing tax.
Conclusion
The Government’s proposal to exempt testamentary trusts from the new 30% minimum trust tax provides welcome certainty for many Australian families. However, the proposal is still under consultation, and several important design details remain unresolved.
For now, there is no need to make major changes simply because of the announcement. Instead, continue reviewing your estate plan regularly and obtain professional legal and tax advice whenever your personal or financial circumstances change.
A well-prepared estate plan remains one of the best ways to protect your family and ensure your wishes are carried out.
Frequently Asked Questions
Is the 30% trust tax already law?
No. The proposal is still being considered by Treasury and has not yet been passed by Parliament.
Will testamentary trusts pay the new 30% tax?
The Government has stated that genuine testamentary trusts are intended to be exempt, although the final legislation has not yet been released.
Should I change my Will now?
For most people, no. Unless your Will already needs updating for other reasons, it is generally sensible to wait until the final legislation is known.
What is a testamentary trust?
A testamentary trust is a trust created under your Will that begins after your death and allows assets to be managed for your beneficiaries.
Why are testamentary trusts popular?
They provide flexibility, asset protection, tax advantages for some beneficiaries and greater control over how inheritances are managed.
Will an older Will still qualify?
Possibly. Treasury has not yet decided whether the relevant date will be when the Will was signed, when the person dies or another event.
Do trustees need to do anything now?
No immediate changes are required, but trustees should continue maintaining accurate records and seek advice if the law changes.
Should I review my estate plan?
Yes. Regardless of tax law changes, reviewing your Will every few years or after major life events is considered good estate planning practice.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
High Court’s Bendel Decision Reshapes Trust Taxation
Landmark High Court Victory for Trusts and Private Groups
The High Court’s decision in Commissioner of Taxation v Bendel [2026] HCA 18 is one of the most significant tax cases affecting trusts and private groups in recent decades.
In a decisive 5-2 majority ruling, the High Court rejected the Australian Taxation Office’s long-standing position that an Unpaid Present Entitlement (UPE) owed by a trust to a corporate beneficiary could automatically be treated as a loan under Division 7A.
The decision overturns a position the ATO had maintained since 2009 and provides welcome certainty for many business owners, family groups and property investors who have used discretionary trusts and bucket companies as part of their tax and asset protection strategies.
However, while the decision represents a major taxpayer victory, it also raises new questions regarding trust distributions, Division 7A compliance, Section 100A, Subdivision EA and potential future legislative reform.
What Is an Unpaid Present Entitlement (UPE)?
A UPE arises when a discretionary trust distributes income to a beneficiary, such as a company, but the cash is not physically paid.
For example:
- A trust earns $200,000.
- The trustee resolves to distribute $100,000 to a corporate beneficiary.
- The company pays tax on the distribution.
- The cash remains within the trust rather than being transferred immediately.
Historically, this arrangement has been widely used by family groups and private businesses through so-called “bucket companies.”
The controversy centred on whether the unpaid amount should be treated as a loan from the company back to the trust.
The ATO’s Long-Standing Position on UPEs
Since 2009, the ATO has argued that where a company beneficiary does not demand payment of a UPE, it effectively provides “financial accommodation” to the trust.
Under this interpretation, the unpaid amount could become a deemed Division 7A loan requiring:
- Formal loan agreements
- Annual principal repayments
- Interest charges
- Compliance with Division 7A loan terms
Failure to comply could trigger deemed dividends and additional tax liabilities.
This approach was reflected in various ATO rulings and determinations and became accepted practice among many advisers despite ongoing criticism from tax professionals.
What Did the High Court Decide?
The High Court firmly rejected the Commissioner’s interpretation.
The majority held that a UPE is fundamentally different from a loan.
The Court concluded that:
- A corporate beneficiary does not make a loan simply by failing to demand payment.
- A UPE represents an equitable entitlement rather than a debtor-creditor relationship.
- There is no transfer of money or value from the company to the trust.
- The mere existence of a UPE does not constitute financial accommodation.
- A loan requires an active transaction, not passive inaction.
In simple terms, the Court found that the company had done nothing. Therefore, no loan existed.
This finding aligns with earlier decisions of both the Administrative Appeals Tribunal and the Full Federal Court.
Why Tax Professionals Are Calling Bendel a Landmark Decision
Many tax advisers have viewed the ATO’s interpretation as extending Division 7A beyond Parliament’s intended scope.
The Bendel decision reinforces an important legal principle:
The ATO administers tax law it does not create tax law.
The Court’s reasoning highlights the limits of administrative interpretation and serves as a reminder that taxation must be imposed through legislation rather than regulatory guidance alone.
This aspect of the judgment has attracted significant attention from the accounting profession, with many commentators suggesting the decision restores greater certainty to trust taxation.
Why the Decision Matters for Family Trusts and Bucket Companies
For thousands of Australian family groups, the use of corporate beneficiaries has been a central tax planning strategy.
The Bendel decision may remove a significant compliance burden for many trust structures.
Potential benefits include:
- Reduced Division 7A compliance obligations
- Greater certainty regarding historical UPE arrangements
- Reduced risk of deemed dividends
- Simplified trust administration
- Lower ongoing compliance costs
However, taxpayers should not assume that all UPE arrangements are now risk-free.
Existing Arrangements Still Require Careful Review
Many taxpayers have already implemented arrangements based on the ATO’s previous guidance.
These may include:
- Division 7A loan agreements
- Sub-trust arrangements
- Formal repayment schedules
- Interest charging arrangements
The High Court’s decision does not automatically unwind those arrangements.
Groups should carefully review:
- Existing loan documentation
- Historical trust resolutions
- Prior year tax returns
- Corporate beneficiary arrangements
- Trustee accounting records
Professional advice is strongly recommended before making changes.
Section 100A Remains a Significant Risk
One of the key messages emerging from both the ATO and tax commentators is that Section 100A remains firmly in the spotlight.
Section 100A targets reimbursement arrangements where:
- Income is distributed to one party; and
- Another party ultimately enjoys the economic benefit.
If Section 100A applies:
- The trustee may be taxed at the top marginal rate.
- Significant penalties and interest may arise.
The Bendel victory does not provide protection against Section 100A.
Subdivision EA Could Become More Important
The High Court specifically noted that Subdivision EA may have applied in Bendel.
Subdivision EA can trigger a deemed dividend where:
- A trust owes money to a corporate beneficiary; and
- The trust provides benefits to shareholders or their associates.
For many years, Subdivision EA became less relevant because the ATO treated UPEs as Division 7A loans.
Following Bendel, tax advisers expect Subdivision EA to regain prominence as a key anti-avoidance provision.
Part IVA Still Applies to Aggressive Tax Planning
The decision also does not diminish the operation of Part IVA, Australia’s general anti-avoidance regime.
The courts have previously supported the ATO where arrangements were primarily designed to obtain tax advantages.
Taxpayers using bucket companies or corporate beneficiaries should continue to ensure their structures have genuine commercial and asset protection purposes.
AFR and Industry Commentary: What Happens Next?
Commentary across the tax profession suggests Bendel may prompt a legislative response from Government.
AFR reporting and professional commentary have highlighted concerns that the decision could significantly reduce the effectiveness of existing Division 7A integrity measures.
At the same time, many tax practitioners argue that if Parliament wishes to tax UPEs differently, it should do so through legislative amendment rather than administrative interpretation.
This debate is likely to continue as policymakers consider broader trust taxation reforms.
Federal Budget Changes May Reduce the Long-Term Impact
While Bendel represents a major taxpayer win today, its long-term significance may be affected by recent Federal Budget announcements.
Proposed measures include:
- A minimum 30% tax on discretionary trust distributions from 1 July 2028.
- Changes affecting the use of corporate beneficiaries.
- Broader trust integrity reforms.
These measures may reduce the attractiveness of traditional bucket company strategies and reshape trust planning over the coming years.
What Should Trustees and Business Owners Do Now?
Following Bendel, trustees, business owners and advisers should:
Review Existing UPE Arrangements
Examine trust distributions, loan agreements and sub-trust arrangements implemented under the ATO’s previous guidance.
Assess Section 100A Risks
Ensure trust distributions are supported by genuine commercial arrangements.
Review Corporate Beneficiary Structures
Confirm bucket company arrangements continue to serve commercial, asset protection and succession planning objectives.
Monitor Legislative Developments
Future legislative amendments may alter the practical impact of the High Court’s decision.
Seek Professional Advice
Every trust structure is different and should be reviewed based on its specific facts and documentation.
Frequently Asked Questions
What is the Bendel case?
Commissioner of Taxation v Bendel [2026] HCA 18 is a High Court case that ruled unpaid present entitlements (UPEs) are not automatically loans under Division 7A.
What is a UPE?
A UPE arises when trust income is distributed to a beneficiary but remains unpaid.
Does the decision mean all UPEs are now safe?
No. While a UPE itself is not a Division 7A loan, other provisions such as Section 100A, Subdivision EA and Part IVA may still apply.
Do existing Division 7A loan agreements need to be unwound?
Not necessarily. Existing arrangements should be reviewed carefully before any action is taken.
What is a bucket company?
A bucket company is a corporate beneficiary used by discretionary trusts to receive trust distributions and cap tax at the corporate tax rate.
Could the Government change the law?
Yes. Many tax professionals expect legislative reform following the High Court’s decision.
Does Bendel affect trust distributions made before 2026?
Potentially. Taxpayers should seek professional advice regarding prior-year arrangements and existing compliance positions.
Conclusion
The High Court’s decision in Bendel represents one of the most important trust taxation rulings in recent Australian history.
By rejecting the ATO’s long-held position on unpaid present entitlements, the Court has provided greater certainty for trustees, private groups and corporate beneficiaries. However, the decision does not remove the importance of other integrity provisions such as Section 100A, Subdivision EA and Part IVA.
For business owners, property investors and family groups operating discretionary trusts, now is the ideal time to review trust structures, bucket company arrangements and historical UPE positions before further legislative reforms emerge.
The Bendel decision may have settled the UPE debate, but the broader conversation about trust taxation in Australia is far from over.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
EOFY Tax Planning Strategies 2026
As the end of the financial year approaches, Australians have a valuable opportunity to review their tax position and implement strategies that could legally reduce tax and strengthen long-term wealth.
Two of the most effective year-end tax planning areas in 2026 are maximising superannuation contributions and reviewing family trust distributions before 30 June. Both strategies can provide substantial tax benefits when handled correctly, but strict contribution caps and timing rules apply. Planning before year end allows individuals, business owners and families to take advantage of government incentives, reduce taxable income, and position themselves more effectively for the future.
Why Superannuation Remains One of Australia’s Best Tax Strategies
Superannuation continues to be one of the most tax-effective wealth creation tools available to Australians.
The government actively encourages retirement savings by offering concessional tax treatment on contributions and investment earnings inside super. However, many Australians still fail to fully utilise the available contribution limits and government incentives before 30 June. For many taxpayers, EOFY is the ideal time to review whether additional super contributions could reduce tax while boosting long-term retirement savings.
Super Contribution Caps for 2025–26
There are two main categories of super contributions:
Tax-Deductible Super Contributions
These include:
- Employer super guarantee contributions
- Salary sacrifice contributions
- Personal deductible contributions claimed at tax time
The concessional contribution cap for the 2025–26 financial year is:
- $30,000 per person
From 1 July 2026, this cap will increase to:
- $32,500 per person
Exceeding the cap may trigger additional tax, making careful planning essential before making extra contributions.
Non-Concessional Super Contributions
These are personal contributions made from after-tax savings where no tax deduction is claimed.
The current annual non-concessional contribution cap is:
- $120,000 per person
From 1 July 2026, the cap increases to:
- $130,000 per person
These contributions can be particularly useful for individuals looking to build retirement savings or contribute proceeds from investments or asset sales into the superannuation environment.
The Power of Starting Super Contributions Early
One of the greatest advantages of superannuation is the power of long-term compound growth. Money invested inside super benefits from a concessional tax environment, allowing earnings to compound more effectively over time.
Example: The Impact of Time on Super Growth
If $100,000 is contributed into super at age 25 and earns an average annual return of 7%, it could grow to approximately:
- $1.5 million by age 65
However, if the same $100,000 is contributed at age 40, it may only grow to:
- Around $542,000 by retirement
The difference of almost $1 million highlights how valuable early contributions can be for long-term retirement outcomes.
Super Contribution Splitting with Your Spouse
Many Australians are unaware they can split certain super contributions with their spouse.Under contribution splitting rules, a super fund may transfer up to 85% of eligible concessional contributions made in the previous financial year into a spouse’s super account.
This strategy can help:
- Balance super balances between spouses
- Improve future retirement planning flexibility
- Assist with transfer balance cap management later in life
Importantly, spouses can hold different super funds and still utilise this strategy. Applications generally need to be completed before 30 June each year.
The Government Super Co-Contribution: Free Money for Eligible Australians
The government continues to offer one of Australia’s most underutilised super incentives — the super co-contribution. If your income is below $62,488 in 2025–26, you may qualify for a government contribution by making a personal after-tax contribution into super.
How the Super Co-Contribution Works
- Contribute $1,000 into super from your own savings
- Do not claim a tax deduction
- The government may contribute up to $500 directly into your super account
The full $500 co-contribution applies for individuals earning under $37,000 and phases out gradually above this level. For younger Australians, even small contributions can produce significant long-term results through compound growth.
Spouse Super Contributions and Tax Offsets
If your spouse earns less than $40,000 annually, contributing to their super may also provide a personal tax offset.
How the Spouse Contribution Offset Works
You can contribute up to:
- $3,000 into your spouse’s super account
In return, you may receive:
- An 18% tax offset
- Worth up to $540
This strategy helps increase household retirement savings while also delivering an immediate tax benefit.
Why EOFY Super Planning Matters
Superannuation rules become increasingly complex when factors such as:
- Taxable income
- Existing super balances
- Age
- Contribution history
- Total super balance thresholds
are taken into account. Reviewing contribution opportunities before 30 June allows time to structure contributions correctly and avoid missing valuable tax-saving opportunities.
Family Trust Distributions 2026: What You Need to Know Before 30 June
For families operating discretionary or family trusts, April, May and June are critical planning months. Trust distribution decisions must generally be made before 30 June each year, and failing to do so correctly can result in significant tax consequences.
How Family Trusts Are Taxed in Australia
Under Australian tax law, trust income is generally taxed once only.
Either:
- The beneficiaries pay tax on distributed income, or
- The trust itself pays tax
However, if the trust is taxed directly, the tax rate can reach:
- 47% including Medicare levy
This is why distributing income to beneficiaries on lower marginal tax rates is often far more tax effective.
Choosing the Right Beneficiaries for Trust Distributions
Effective family trust tax planning often involves distributing income to family members with lower taxable incomes.
Potential beneficiaries may include:
- Adult children studying at university
- A lower-income spouse
- Retired parents
- Adult family members with lower taxable income
By distributing income strategically, families may significantly reduce their overall tax burden.
Trust Distribution Rules Are Strict
The ATO closely monitors trust distributions and anti-avoidance rules apply.Distributions must be genuine, and beneficiaries must actually receive or benefit from the income allocated to them. Simply allocating income on paper without genuine entitlement can trigger ATO scrutiny and potential penalties.
When Paying Higher Tax Through the Trust May Still Make Sense
Although distributing trust income is usually preferable, there are situations where retaining some income inside the trust and paying tax at the top marginal rate may be appropriate.
For example:
- Additional income may push a beneficiary into a higher tax bracket
- It could impact HELP debt repayments
- Family assistance payments or Medicare surcharges may be affected
- Division 293 tax thresholds may apply
Effective tax planning considers the broader financial picture rather than simply chasing the lowest immediate tax rate.
The 30 June Deadline for Family Trust Distributions
One of the most important rules for discretionary trusts is that distribution decisions must generally be documented before 30 June. There is no flexibility once the financial year ends. Waiting until after year end to decide who should receive trust income is often too late.
Proper planning requires:
- Reviewing estimated trust income before year end
- Determining the most tax-effective distribution strategy
- Preparing trustee resolutions before 30 June
Failing to act in time can expose trust income to the top marginal tax rate.
Conclusion: EOFY Tax Planning Can Deliver Significant Savings
EOFY tax planning is about far more than simply lodging a tax return. Proactive planning before 30 June can create substantial opportunities to legally minimise tax, increase retirement savings and improve long-term wealth outcomes.
Maximising superannuation contributions, utilising government incentives, reviewing spouse contribution strategies, and carefully planning family trust distributions are some of the most effective strategies available to Australian taxpayers in 2026.
Because contribution caps, trust rules and tax thresholds can become highly complex, seeking professional advice before year end can help ensure strategies are implemented correctly and deadlines are not missed.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
ATO Loses Landmark Case – Family Trusts
Since 16 December 2009, the Australian Taxation Office (ATO) has maintained the view that when a family trust appoints income to a corporate beneficiary (referred to as the beneficiary company) without making a payment, the unpaid present entitlement (UPE) constitutes a “loan” for Division 7A purposes. As per this view, the UPE must either be paid or placed on complying Division 7A loan terms, or a deemed fully assessable dividend would arise.
This view, however, had not been tested in court until 28 September 2023, when the Administrative Appeals Tribunal (AAT) ruled in favor of Steven Bendel and his beneficiary company, Gleewin Investments Pty Ltd (Gleewin). The AAT’s decision concluded that the UPEs to Gleewin were not loans. The full details of the ATO’s historical stance, as well as the AAT case analysis, are outlined below.
The Commissioner of Taxation appealed this decision to the Full Federal Court, which issued its judgment on 19 February 2025 in the Bendel case. The Court, in a unanimous decision, ruled that UPEs do not qualify as “loans” under Division 7A.
What Does This Mean for You?
Private groups and family trusts are likely to have numerous questions about how the Bendel case will affect them, both retrospectively and in the future.
Currently, the ATO has not announced whether it intends to appeal the decision to the High Court, but this is expected in the coming weeks. In the meantime, the ATO is expected to release a Decision Impact Statement, which will outline their view on the case and its potential impact on taxpayers.
Until there are immediate filing obligations or further guidance from the ATO, our recommendation is to wait and see what the ATO’s next steps are. We suggest reaching out to review your arrangements in light of the case and the potential changes it could bring.
Have You Been Subject to ATO Review in the Past?
If the ATO has previously imposed additional tax, penalties, or interest in relation to UPEs within your family trust group, it may be worthwhile to review the ATO’s decision and discuss the possibility of filing an objection. Feel free to contact us for assistance in navigating this process.
Key Takeaways from the Bendel Case
Here are the key takeaways from the Bendel case and its implications:
- UPEs Arising After 30 June 2024: Depending on your company’s lodgment schedule, consider keeping UPEs as is until we receive more clarity on the matter.
- UPEs Already Converted to Loans or Sub-Trusts: We are awaiting guidance from the ATO through their Decision Impact Statement or subsequent updates. Without administrative concessions, these UPEs could continue to be subject to Division 7A.
- Loans from Trusts to Associates of a Company with UPEs: A separate section of Division 7A governs these types of arrangements and should be considered accordingly.
- Future Tax Considerations: If the government decides to amend the law or the ATO provides further guidance, trust structures could become more attractive if UPEs can be retained as working capital or reinvested within the trust.
Conclusion
The Bendel case represents a significant turning point in tax structuring for private groups, particularly in relation to family trusts. The decision challenges the ATO’s long-standing interpretation of UPEs under Division 7A, and its implications will likely affect future tax planning, structuring, and compliance. Taxpayers and advisers should carefully monitor any further developments, especially from the ATO, to ensure they are equipped to make informed decisions in the future.
—————BOOK YOUR EXCLUSIVE 15 MINUTE ZOOM CONSULTATION————-
We offer a 15-minute no obligation consultation to existing property investors, first home buyers and small business owners who are looking at property investments, business and asset protection. To Book an Appointment simply click here and pick a time and date.
BOOK YOUR ZOOM APPOINTMENT HERE
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
What is a Trust
Although trusts are common, they are often poorly understood. Setting up a trust is often driven by a new business opportunity, a growing business, or a need to better structure your investments. When set up correctly, there are clear tax benefits when it comes to operating as a family trust.
The importance of the correct structure in which to hold your investment, (be it property or any other) and its correct use could mean the difference between losing or retaining your assets and the paying or not paying of hundreds of thousands of dollars in excess tax over the longer term. Trusts are a fundamental element in the planning of business, investment, and family financial affairs. There are many examples of how trusts figure in everyday transactions.
Why a Trust and which kind?
Apart from any tax benefits that might be associated with a trust, there are also benefits that can arise from the flexibility that a trust affords in responding to changed circumstances.
A trust can give some protection from creditors and can accommodate an employer/employee relationship. In family matters, the flexibility, control, and limited liability aspects combined with potential tax savings, make discretionary trusts very popular. There are strengths and weaknesses associated with trusts and it is important for clients to understand what they are and how the trust will evolve with changed circumstances.
You should always obtain advice from a specialist tax adviser and a solicitor when considering setting up a trust. Although a trust can be established without a written document, it is preferable to have a formal deed known as a declaration of trust or a deed of settlement.
All types of trusts (with the exception of Superannuation Trusts) established in either NSW, NT or Victoria need to be duty stamped upon execution.
How Family/Discretionary Trusts Operate
A discretionary trust or family trust is a common type of trust used to hold assets or run a family business. It is one of the most common trust structures. Essentially, it is a relationship where a trustee holds property or assets for the benefit of a beneficiary or beneficiaries.
The one who holds the assets is called a trustee. A trust is not a legal entity and it requires the establishment of a legal entity to enter into agreement for it on behalf of the trust. Trustees can either be an individual or a company.
The Trust is the relationship or structure between trustees and beneficiaries. You could think of a Trust as a container of sorts, that things are placed within. All assets placed into the container become property of the Trust, controlled by the trustee for the sake of the beneficiary. See the diagram below:

Who are parties to a Trust?
The Trustee
The trustee can be an individual, individuals or a company and they are the legal entity who owns the assets and makes decisions on the trust’s behalf. There can be more than one trustee and more than one beneficiary. In most cases, the trustees are usually parents or a company that they own, and the beneficiaries are their children or dependants.
The trustee owns and controls the business’ assets, distributes income, and must comply with the obligations of the trust deed and act with the best interests of the beneficiaries in mind. The trustee is also responsible for registering the tax purposes, lodging tax returns and meeting any other tax obligations on behalf of the trust.
Who will be Trustee?
Note as the decision maker, the trustee will be held responsible for actions by the trust, as is the case with any owner. We would normally recommend a company to be the trustee as the company would not own any assets and as such gives you an extra layer of protection, especially if you own assets in your name. If you as an individual are trustee, then your personal assets may be at risk in the event of legal action against the trust which insurance will or does not cover.
Beneficiaries
The beneficiaries are the people entitled to the income and assets of the trust. The beneficiaries of the trust are usually members of a family (family group), as well as companies and trusts that are controlled by that family. For example, the primary or default beneficiaries may be a parent or parents and the secondary beneficiaries maybe children, grandparents, companies etc.
The role of the default beneficiary is to receive and/or decide the direction of any funds that aren’t allocated by the trustee. It’s also important to note that you cannot change the default beneficiary without triggering capital gains tax and stamp duty. Beneficiaries will generally include their share of the trust’s net income as income in their own tax returns and if they receive income from other sources they will be taxed for these as well.
Primary Beneficiaries
You need to identify the primary beneficiaries by name. Depending on the deed the beneficiaries can be changed at any time and you can make distributions to anyone even if you do not identify them here. With certain deeds there may be tax consequences so get this checked before doing so.
Financial institutions, when looking at a loan application in the trust name or an individually named borrower, will also review this section of the trust and would normally require any named initial beneficiaries to be part of a loan application. Related parties to the initial beneficiaries are not normally party to the trust and as such are not normally part of the above review unless they have actually received distributions. The trust deed provides that the beneficiaries include such persons as are related to you as follows and as such there is no need to specifically identify them.
Note also that beneficiaries include companies and trusts associated with all the persons specifically identified
Appointor
The Appointor (sometimes called the Principal or Guardian) has, in fact, the most powerful role in a trust and should be carefully selected. While the trustee is the one who decides what happens to the assets, funds and profits of the trust, it is the Appointor who has the power to change the trustee and appoint a new one. It is important to consult with your solicitor and include in your will the transfer of this role upon your death and that this power is passed on to the person of your choosing.
Settlor
The Settlor should never be the beneficiary of the Trust to avoid income tax issues for the trustee. The Settlor is someone who puts down a sum of money to start the trust, commonly around $10. Once the trust is established, the Settlor has no other role, entitlements, rights or connection to the trust. This $10 is a gift to commence (settle) the trust. It takes on the literal meaning of a gift i.e. you cannot give it yourself and the giver must not get back anything in return. Therefore the settlor can never be a beneficiary of the trust. We would normally see a friend gift you the funds. The settlor will need to sign the trust deed when you get it, to confirm the gift, after which they have no involvement.
- Discretionary/Family Trusts: Advantages
Asset Protection
Many business owners face a degree of risk in owning a business, for example if the business fails, they may be sued personally or put at risk of bankruptcy. Similarly, those in partnerships, particularly those with bank debts, can face similar risks. Assets that are within a family trust are protected from creditors, so even if a claim is made against you, the assets are not in your name and therefore cannot be accessed in these circumstances.
Tax Advantages
Operating your business from a family trust and having the company act as trustee means you can retain the limited liability benefits of a company structure while taking advantage of the tax flexibility benefits of a family trust.
When set up correctly, there are clear family trust tax benefits for individuals and businesses. Because the trust itself does not pay tax, beneficiaries are taxed based on the amount of income placed in their name (as well as any other income they may have from other sources). A family trust allows you to distribute profit amongst family members to utilise their income tax “tax-free thresholds”. If the business’ profits grow too large to distribute effectively, a family trust can also distribute to a separate company to cap the tax rate at 30 percent.
Keeping it in the Family
Whether you’re looking to keep your family home in the family or want to stagger inheritance distribution to ensure it’s not all spent at once, a family trust prevents, will contests and secures assets. Assets held within the trust do not form part of a deceased estate preventing contests to a Will or your child’s spouse claiming their share of an inheritance.
A family trust can provide long-term financial support for your children or grandchildren, allowing you to invest in their long-term education and distribute family assets to future generations. A family trust can also be a great way to protect vulnerable beneficiaries who may make poor spending decisions if they were to control their own assets.
- Family/ Discretionary Trusts: Disadvantages
Any income earned by the trust that is not distributed is taxed at the highest marginal tax rate. If you do find you are making a lot of profit as a family trust, those profits must be pushed out to beneficiaries. You could run out of beneficiaries and those beneficiaries will be paying highest tax rate. With a family trust, you can add additional beneficiaries if the trust deed allows for it, but care must be taken as capital gains tax and stamp duty may be triggered if done incorrectly. The trust cannot allocate tax losses to beneficiaries either.
Family Matters
There can be challenges in running the trust when other family issues occur. There can also be some complexities regarding succession planning and asset allocation upon the death of the trustee. With a Will, you can dictate what goes to who, however, a family trust is separate to an individual’s will and you may be able to choose who controls the trust, you don’t dictate how they control it.
Negative Gearing
One of the disadvantages of a discretionary trust is the loss of some benefits associated with negative gearing investments through the trust. Namely, if a discretionary trust acquires a property and borrows to invest in that property, then any losses generated are accumulated in the trust and cannot be distributed to the beneficiaries.
This is not such a problem if the discretionary trust itself other sources of income has but can give rise to significant problems for, say, PAYG-type taxpayers who wish to acquire a property and negatively gear at the same time.
Obviously, the advantages of having the property owned by a discretionary trust may be outweighed in this case by the disadvantage of any negative gearing being generated in the trust itself. The development of a unit trust (one where the discretionary nature is preserved in the trust deed but allows the issue of units) is an attempt to overcome this negative gearing problem.
Family Trust vs Company
One of the key differences between a trustee company and a trading company, is that the trustee company doesn’t trade, it doesn’t have its own tax file number and it doesn’t lodge a tax return of its own. It simply makes decisions for and on behalf of the family trust.
Some other important distinctions are:
- Companies cannot access the 50% capital gains discount, whereas a family trust can. Small business capital gains tax discounts can be accessed by both
- A company is paying tax at 30% or 25% and pays tax from the first dollar. However, a family trust doesn’t pay tax and profits are pushed out each year
- A company can accumulate profits and reinvest those profits into the business as working capital
- Companies are great for doing business with unrelated parties and you will be protected by the Corporations Act. As for a trust, if a party is not within family group, you cannot bring them into the trust with you
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.