




Are Family Trusts Still Worth It in Australia? What the 2026 Tax Changes Mean for Families and Business Owner
For decades, discretionary family trusts have been popular with Australian families, investors and business owners. They can provide flexibility when distributing income, support asset protection and succession planning, and help families manage business and investment assets across generations.
However, the environment surrounding family trusts is changing.
The 2026–27 Federal Budget proposes a 30% minimum tax on discretionary trust taxable income from 1 July 2028, together with transitional rollover relief for eligible businesses and taxpayers considering restructuring. At the same time, the ATO continues to scrutinise trust distributions, section 100A arrangements, family trust elections, franking credits and Division 7A issues.
So, are family trusts still worth it?
The answer is: possibly, but the reasons for using one need to be carefully considered.
A family trust should no longer be established simply because it is considered a “tax-effective structure”. Tax, asset protection, succession, cash flow, compliance costs, investment strategy and long-term family objectives all need to be considered.
What Is a Discretionary Family Trust?
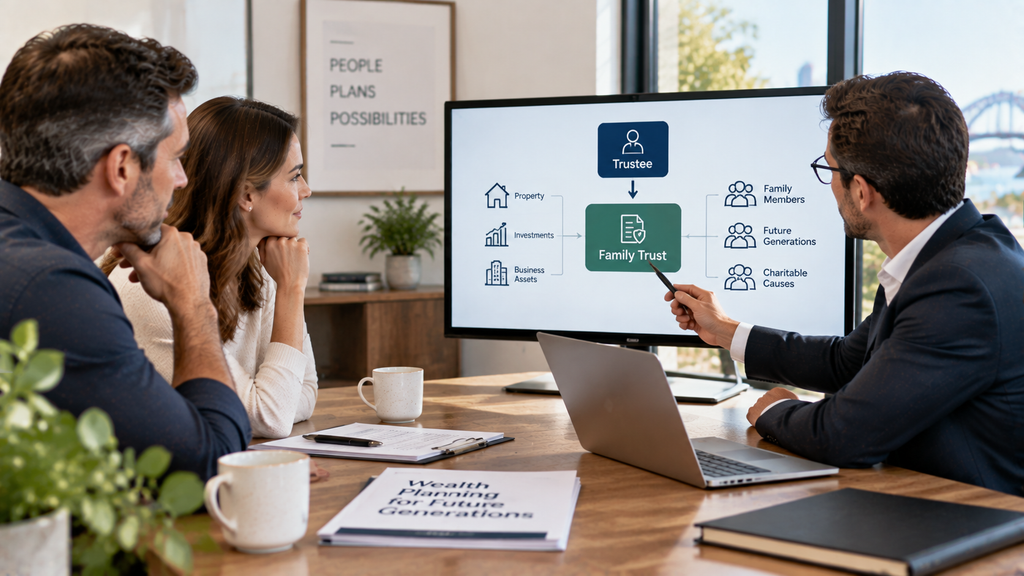
A discretionary trust is a structure where a trustee holds assets for a group of beneficiaries. Unlike a company, beneficiaries generally do not have fixed ownership percentages. Subject to the trust deed and tax law, the trustee can decide how income and capital are distributed among eligible beneficiaries.
This flexibility has historically made family trusts attractive for:
- family businesses
- investment portfolios
- property investments
- wealth accumulation
- intergenerational wealth planning
- asset protection strategies
- distributing income between family members.
However, flexibility also creates complexity. Trusts must be properly established and administered, resolutions need to be valid, distributions correctly documented and tax consequences understood.
Why Have Family Trusts Been Popular in Australia?
Income Distribution Flexibility
Subject to the trust deed and tax law, a discretionary trust can potentially distribute different types of income to different beneficiaries. This can provide flexibility where family members have different taxable incomes.
However, the proposed 30% minimum tax from 1 July 2028 may reduce the tax benefit of income splitting for trusts within the new rules.
Asset Protection
Trusts can potentially provide an additional layer of separation between business or investment assets and individuals.
However, a trust is not an absolute asset protection shield. Protection depends on the circumstances, trustee arrangements, guarantees, insolvency law and how the trust has been operated.
Succession Planning
A properly structured trust can provide flexibility when control and economic benefits need to be managed across generations. This can be particularly relevant for families with operating businesses, investment portfolios, property and significant accumulated wealth.
Long-Term Wealth Management
A family trust can provide a framework for holding and managing family assets over an extended period. However, the structure should be reviewed as family circumstances and wealth objectives change.
The 2026 Budget Changes the Family Trust Equation
The most significant recent development is the Federal Government’s proposed 30% minimum tax on discretionary trusts.
Under the proposal, from 1 July 2028, trustees of discretionary trusts within the rules will pay a minimum tax of 30% on taxable income. Beneficiaries will continue to declare their trust income, with non-corporate beneficiaries receiving non-refundable credits for tax paid by the trustee.
The Government says the reform is intended to reduce the tax advantage created by income splitting through discretionary trusts.
The proposal includes exclusions for certain categories, including:
- fixed and widely held trusts
- complying superannuation funds
- special disability trusts
- deceased estates
- charitable trusts
- certain primary production income
- certain income relating to vulnerable minors
- certain non-resident withholding tax amounts
- certain testamentary trust assets existing at the time of announcement.
Importantly, this is not a 30% minimum tax on every type of trust. It specifically targets discretionary trusts within the proposed rules.
What Does the 30% Minimum Tax Mean for Family Trusts?
The proposed changes could significantly alter the tax outcomes for some discretionary trusts.
Historically, a family trust may have distributed taxable income among beneficiaries with lower marginal tax rates. From 1 July 2028, the proposed minimum tax could reduce the benefit of this strategy for trusts within scope.
However, the impact will depend on each trust’s circumstances. The Government estimates that many small businesses will not face an additional tax liability in every year.
There is therefore no reason for every family trust to be dismantled simply because of the Budget announcement. Trustees should instead model future tax outcomes based on their expected income, beneficiaries and distribution strategy.
Should You Move Your Family Trust Into a Company?
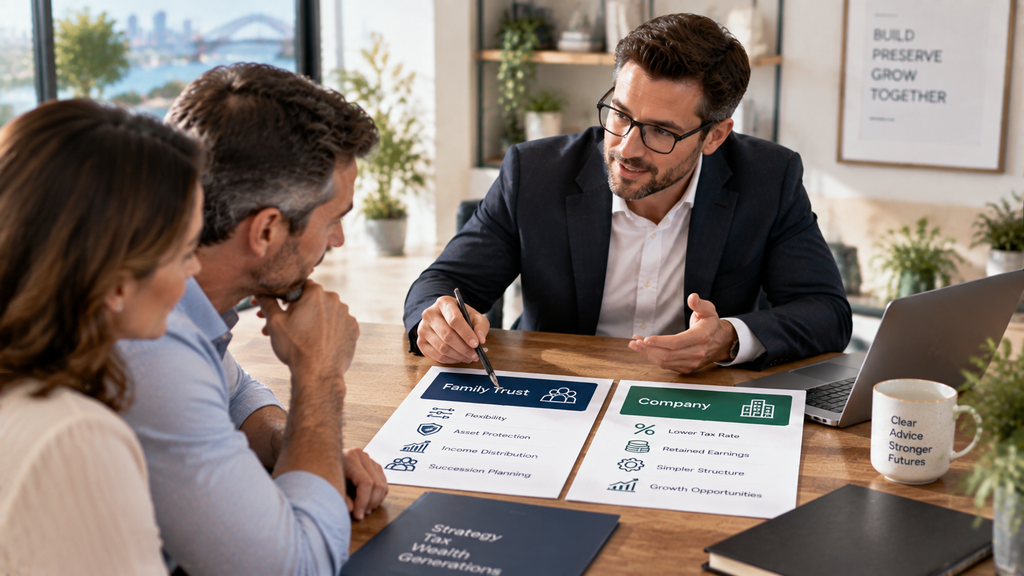
The proposed changes may make companies more attractive for some families and businesses, particularly where profits are intended to be retained and reinvested.
However, a company is not automatically better than a trust. A company has shareholders with defined ownership interests, while a discretionary trust operates differently and can provide greater distribution flexibility.
Moving existing assets can also create tax, legal and transaction consequences. The decision should therefore be based on a detailed comparison rather than simply comparing the proposed trust minimum tax with the company tax rate.
New Rollover Relief Could Make Restructuring Easier
The 2026 Budget proposes a three-year period from 1 July 2027 to assist eligible small businesses and others who choose to restructure from discretionary trusts into structures such as companies or fixed trusts.
The proposed relief is intended to reduce income tax and CGT consequences that might otherwise arise.
However, restructuring may still involve:
- stamp duty
- financing and lender requirements
- asset protection
- legal ownership
- trust deeds
- shareholder arrangements
- estate planning
- Division 7A
- future distributions
- accounting and administration.
The rules should be assessed once legislation and detailed requirements are settled.
Family Trust Elections: Why They Matter
A Family Trust Election (FTE) can provide access to certain tax concessions, including benefits involving franking credits and tax losses in appropriate circumstances.
However, an FTE also restricts distributions outside the relevant family group.
The ATO confirms that Family Trust Distribution Tax (FTDT) is imposed at 47% where the relevant rules apply to distributions outside the specified individual’s family group.
This makes family trust elections particularly important during succession planning and restructuring.
What Happens If a Family Trust Distributes Outside the Family Group?
This can become expensive.
If a trust has made an FTE and distributes to an entity outside the relevant family group, FTDT may apply at 47%. A $100,000 distribution caught by the rules could therefore potentially result in $47,000 of tax.
Trustees should not assume that a distribution between related entities is automatically permitted. Family trust elections and family groups need to be reviewed before significant distributions or restructures.
Intergenerational Wealth Transfers Require Careful Planning
Succession planning can become complicated when a family has multiple trusts, companies and beneficiaries.
For example:
- a parent may be the specified individual of one trust
- an adult child may control another trust
- companies may sit beneath different trusts
- investment assets may be held across multiple entities.
A commercially sensible distribution can still have unexpected tax consequences if family trust elections and family groups are not properly considered.
What Is Section 100A and Why Does It Matter to Family Trusts?
Section 100A can apply where a beneficiary is made presently entitled to trust income, but another person receives the benefit as part of a reimbursement arrangement.
The ATO has published Taxation Ruling TR 2022/4 and Practical Compliance Guideline PCG 2022/2 outlining its approach.
Arrangements that may attract scrutiny include situations where:
- a beneficiary receives a distribution but does not receive the economic benefit
- income is redirected to another person
- arrangements are designed to achieve a lower tax outcome
- trust entitlements do not reflect the beneficiary’s economic position.
Trustees should maintain records explaining the transactions and why beneficiaries dealt with their entitlements as they did.
Why Section 100A Matters for Family Businesses
Section 100A can be particularly relevant where trusts distribute income among parents, children, companies and other related entities.
A distribution should not be treated simply as an accounting entry. There should be a clear understanding of:
- who was made presently entitled
- why the distribution was made
- what happened to the entitlement
- who ultimately benefited
- what agreements existed
- whether the arrangement has a genuine commercial or family purpose.
Good documentation is increasingly important.
The Bendel Case and Division 7A: What Trusts Need to Know
The Bendel litigation has attracted significant attention among family trust advisers and business owners. The Federal Court considered whether an unpaid present entitlement from a trust to a private company beneficiary could constitute a “loan” for Division 7A purposes.
The Court rejected the Commissioner’s construction of the relevant definition of “loan” in the provision considered.
However, the broader implications remain important. Trust distributions to corporate beneficiaries should not be treated casually. Where income is distributed to a company but cash is not physically paid across, trustees should carefully consider the trust deed, accounting treatment, Division 7A and applicable ATO guidance.
What About Franking Credits and the 45-Day Holding Rule?
Franking credits can be valuable to family trusts and beneficiaries, but eligibility rules apply.
Broadly, the holding period rule requires shares to be held “at risk” for at least 45 days during the relevant qualification period, subject to exceptions.
This can matter where a trust has a corporate beneficiary or investment portfolio containing dividend-paying shares. Failing the relevant requirements can affect access to franking credit benefits.
Are Family Trusts Still Worth It for Small Business Owners?
For many small business owners, the answer may still be yes, but the calculation is changing.
A family trust may remain useful where:
- income distribution flexibility is important
- the family has multiple beneficiaries
- succession planning is a priority
- asset protection is important
- investment assets are being accumulated
- the trust is expected to operate across generations
- compliance costs are justified by the benefits.
However, the proposed minimum tax means the tax advantages may be less significant for some families from 2028 onwards.
When Might a Company Be More Attractive Than a Family Trust?
A company may be worth considering where the main objective is to retain profits and reinvest them.
This may suit businesses that:
- are growing rapidly
- want to retain earnings
- are reinvesting profits
- may require external finance
- plan to introduce investors
- want clearly defined ownership interests.
A company does not provide the same distribution flexibility as a discretionary trust. The decision should therefore be based on long-term objectives rather than tax rates alone.
Should You Close Your Existing Family Trust?
Not necessarily.
The proposed 30% minimum tax does not mean every family trust should be closed.
Before making a decision, consider:
How much income does the trust generate?
A trust with modest income may be affected differently from one distributing substantial business or investment income.
Who receives the income?
If distributions are already made to beneficiaries with tax rates of 30% or higher, the impact may differ from a trust relying heavily on lower-tax-rate beneficiaries.
Is the trust retaining wealth?
The proposed changes may make the choice between a trust and company more important where income is being accumulated and reinvested.
What assets does the trust own?
Business, property and investment assets can each create different tax and structural considerations.
What is the family’s long-term succession plan?
A structure that works today may not be appropriate for the next generation.
Don’t Forget the Cost of Changing an Existing Structure
Moving from a family trust to a company is not necessarily straightforward.
Transferring assets can potentially create:
- capital gains tax
- stamp duty
- refinancing costs
- legal and accounting costs
- transaction costs
- changes to asset protection
- estate planning consequences.
Proposed rollover relief may reduce some tax consequences for eligible restructures, but it should not be assumed that every transfer will qualify.
Existing structures should therefore be reviewed before any transfer takes place.
What Should Family Trust Owners Do Now?
1. Review Your Trust Deed
Make sure the deed remains appropriate for current circumstances and intended distributions.
2. Review Your Family Trust Election
Confirm the specified individual, relevant family group, any interposed entity elections and whether planned distributions could trigger FTDT.
3. Review Your Distribution Strategy
Analyse who receives trust income and why, and consider how the proposed 30% minimum tax could affect future distributions.
4. Review Corporate Beneficiaries
If income is distributed to a company, review how those entitlements are dealt with and consider Division 7A implications.
5. Review Section 100A Risk
Make sure distributions reflect genuine arrangements and that appropriate records are maintained.
6. Model the 2028 Tax Position
Calculate what the proposed minimum tax could mean based on expected income and distributions.
7. Compare Trust and Company Structures
If the trust primarily retains income for investment, compare future tax and administration outcomes with a company or other suitable structure.
8. Review Succession Planning
Consider who should control the trust and assets in the future and how wealth is intended to pass between generations.
Family Trust vs Company: Which Structure Is Better?
There is no universal answer.
| Consideration | Family Trust | Company |
|---|---|---|
| Income distribution flexibility | Generally high | More limited |
| Fixed ownership | No | Yes |
| Retaining profits | Can be less straightforward | Often more straightforward |
| Succession planning | Potentially flexible | Share ownership can be transferred |
| Asset protection | Potentially useful | Potentially useful, but circumstances matter |
| Administration | Can be complex | Generally structured and formal |
| Tax planning | Flexible but increasingly regulated | More predictable in many circumstances |
| Future distributions | Flexible subject to trust rules | Dividends generally linked to share ownership |
| Intergenerational planning | Potentially strong | Can work well with appropriate share structures |
| 2028 proposed trust minimum tax | Potential impact for discretionary trusts | Not subject to the proposed discretionary trust minimum tax |
This table is a starting point, not a substitute for professional advice.
Family Trusts and Intergenerational Wealth Planning
One area where trusts may continue to have significant strategic value is intergenerational wealth planning.
The Budget proposes excluding certain income from assets of testamentary trusts existing at the time of announcement from the proposed discretionary trust minimum tax. Testamentary trusts, however, are fundamentally different from ordinary discretionary family trusts.
For families with substantial wealth, estate planning may involve:
- wills
- testamentary trusts
- superannuation
- companies
- family trusts
- investment structures
- control arrangements
- beneficiary planning.
The objective is to create a structure that works while the current generation is alive and when control and wealth pass to the next generation.
The Real Question Is Not “Trust or Company?”
The more useful question is:
What do you want the structure to achieve?
Consider:
- Will profits be distributed or retained?
- Who needs access to income?
- Who should control the assets?
- Who should ultimately benefit?
- Is asset protection important?
- Are significant investment assets involved?
- Is the business growing?
- Will external investors be required?
- Is succession planning important?
- What will the structure cost to maintain?
- What could it cost to change later?
These questions are more important than simply comparing tax rates.
Conclusion: Are Family Trusts Still Worth It?
Yes, family trusts can still be worth it — but they should no longer be viewed as an automatic tax-saving structure.
The proposed 30% minimum tax on discretionary trusts from 1 July 2028 represents a significant change to Australia’s trust tax environment. Proposed rollover relief may also give eligible businesses an opportunity to restructure during a three-year period beginning 1 July 2027.
At the same time, the ATO continues to scrutinise trust distributions, section 100A arrangements, family trust elections, franking credits and corporate beneficiary arrangements.
For some families, the flexibility, asset protection and succession planning benefits of a discretionary trust may continue to outweigh the additional tax and compliance complexity. For others, particularly businesses seeking to retain and reinvest profits, a company or another structure may become more attractive.
The important point is not to make a rushed decision based on the proposed 30% rate alone.
Changing an established structure can have significant tax, legal, financing and transaction consequences. Family trust owners should instead undertake a strategic review covering tax, distributions, asset protection, business structure, succession, investment strategy and future cash-flow requirements.
The question is no longer simply:
“How much tax does my family trust save?”
It is:
“Is this still the right structure for how my family wants to own, grow, control and ultimately pass on its wealth?”
That is the question worth answering before making any structural changes.
Frequently Asked Questions About Family Trusts in Australia
Are family trusts still worth it after the 2026 Budget?
They can be. The proposed 30% minimum tax affects discretionary trusts within scope from 1 July 2028, but it does not mean every family trust will be worse off or should be closed. The impact depends on the trust’s income, distributions, assets and long-term objectives.
Will all family trusts pay 30% tax from 2028?
No. The proposed minimum tax applies to discretionary trusts within the scope of the measure. Certain trusts and types of income are specifically excluded.
Should I close my family trust before 2028?
Not automatically. Closing or restructuring a trust can create CGT, stamp duty, financing and other consequences. A detailed review should be undertaken before deciding.
Is a company better than a family trust?
It depends on your circumstances. A company may be attractive where profits are retained and reinvested, while a discretionary trust can provide greater distribution and succession flexibility. The right choice depends on the purpose of the structure.
What is the Family Trust Distribution Tax rate?
Where the relevant family trust rules apply to a distribution outside the specified individual’s family group, Family Trust Distribution Tax can apply at 47%.
What is Section 100A?
Section 100A can apply to certain trust distribution arrangements where a beneficiary’s entitlement arises from a reimbursement agreement and another person receives the benefit. The ATO has published specific guidance on its compliance approach.
What is the Bendel case?
Bendel concerned whether certain unpaid trust entitlements to a private company beneficiary constituted a “loan” for Division 7A purposes. The Federal Court rejected the Commissioner’s construction of the relevant definition of “loan”.
Should I restructure my family trust into a company?
Possibly, but the decision should be based on your circumstances and long-term objectives. The Government has proposed expanded rollover relief for eligible restructures from 1 July 2027, but the detailed requirements need to be considered before acting.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Avoid costly mistakes when preparing Trust Resolution Distributions
For many Australian business owners and investors, discretionary trusts remain one of the most effective structures for managing wealth, protecting assets and creating tax flexibility. However, that flexibility comes with strict timing requirements — particularly when it comes to trust distribution resolutions before 30 June.
Every year, business owners unintentionally expose themselves to unnecessary tax simply because trust distribution decisions are left too late or not properly documented before the end of the financial year.
The consequences can be significant. In some cases, trust income may be taxed at the top marginal tax rate of 47%, regardless of how the income was intended to be distributed.
Understanding how trust distributions work, why timing matters, and how proactive planning can improve control over tax outcomes is critical for anyone operating a family trust or discretionary trust structure in Australia.
What Happens If a Trust Distribution Resolution Is Not Completed Before 30 June?
Unlike companies, trusts do not automatically distribute income. A discretionary trust relies on the trustee making a valid distribution resolution before the end of the financial year. If no resolution is made in time, the trust deed and tax law determine how the income will be treated.
In many situations, failing to finalise a trust distribution resolution before 30 June can result in:
- Income being taxed at the highest marginal tax rate
- Loss of tax planning opportunities
- Reduced flexibility for beneficiaries
- Increased ATO scrutiny
- Administrative complications after year end
One of the biggest misconceptions surrounding trust distributions is the belief that the issue can simply be corrected after the financial year closes. Unfortunately, once 30 June passes, the position is generally locked in. This means a missed deadline can permanently alter the tax outcome for that financial year.
Why Timing Is Critical for Family Trust Distributions
Many EOFY tax decisions can be reviewed after year end once final numbers are available. Trust distributions are different. The allocation of trust income must generally occur before 30 June, meaning timing becomes a critical part of maintaining control over the tax outcome.
Leaving trust distribution decisions until the final days of June often creates unnecessary pressure and reduces the ability to consider alternative strategies properly.
By starting trust planning discussions earlier in May or early June, business owners may have more time to:
- Review estimated profit positions
- Assess beneficiary tax positions
- Consider multiple distribution scenarios
- Align trust outcomes with broader tax planning strategies
- Ensure trustee resolutions are completed correctly
The earlier the process begins, the more flexibility and control remain available.
The Risk of Losing Control Over How Trust Income Is Taxed
One of the primary advantages of discretionary trusts is flexibility. Trusts allow income to be distributed among beneficiaries in a way that may improve tax efficiency and align with broader family or business objectives.
However, this flexibility only exists when:
- The trust deed allows it
- Trustee resolutions are prepared correctly
- Distribution decisions are made before 30 June
If distributions are delayed, overlooked or improperly documented, the trust may not operate as intended.
Over time, poor administration can reduce the effectiveness of the structure altogether not because the trust itself is unsuitable, but because the process surrounding the trust is not being managed proactively. Reviewing the trust deed regularly and understanding how distributions operate under the deed can help ensure the structure continues to function effectively.
Missed EOFY Tax Planning Opportunities
Trust distributions are one of the most practical and effective tax planning tools available to business owners and investors.
They influence:
- Who receives trust income
- How that income is taxed
- Overall family tax outcomes
- Profit retention strategies
- Long-term wealth planning
When trust decisions are left until late June, the process often becomes reactive rather than strategic. Instead of carefully assessing different tax outcomes, business owners are forced into making quick decisions simply to meet the deadline.
Over time, these missed planning opportunities can result in:
- Higher overall family tax
- Inefficient use of beneficiaries
- Poor cash flow planning
- Reduced wealth accumulation
A more proactive approach allows trust distributions to align with both current financial performance and long-term objectives.
The Pressure of Leaving Trust Decisions Too Late
EOFY already places pressure on business owners. Financial reporting, compliance obligations, cash flow management and tax planning often all converge in the final weeks of June. Adding trust distribution resolutions at the last minute can create unnecessary stress and increase the risk of mistakes.
When decisions are rushed:
- Important details may be overlooked
- Documentation may be incomplete
- Tax consequences may not be fully understood
- Beneficiary outcomes may not align with expectations
The issue is not always making the wrong decision — it is often not having enough time to make the best decision. Allowing more lead time before 30 June creates greater clarity and improves decision-making quality.
Creating Clarity Before 30 June
The difference between reactive and proactive EOFY planning often comes down to timing.
Reviewing trust positions earlier allows business owners and advisers to:
- Estimate likely trust income
- Review beneficiary tax positions
- Assess broader business performance
- Consider alternative tax planning strategies
- Finalise documentation correctly before deadlines
Even relatively simple steps can create significantly better outcomes.
For example:
- Reviewing projected profits early
- Identifying intended beneficiaries in advance
- Updating trust deed records
- Preparing draft trustee resolutions ahead of time
These actions help transform EOFY from a deadline-driven exercise into a more controlled planning process.
Moving From Last-Minute Decisions to Strategic Trust Planning
Discretionary trusts are designed to provide flexibility and strategic tax planning opportunities. However, that flexibility depends entirely on how the trust is managed. Leaving trust distribution resolutions until the final days of June can significantly reduce the effectiveness of the structure and limit available options.
A more structured, year-round approach to trust management allows for stronger alignment between:
- Business performance
- Tax efficiency
- Asset protection
- Family wealth planning
- Long-term financial goals
Over time, this proactive approach can reduce EOFY pressure while improving overall financial outcomes.
How Professional Advice Can Help With Trust Distribution Planning
Working with experienced accounting and tax advisers throughout the year can help business owners better understand how their trust structure is operating and how distributions fit into the broader financial picture.
This process often begins with:
- Reviewing expected profit positions
- Understanding beneficiary tax outcomes
- Assessing the trust deed
- Planning distribution strategies before year end
- Preparing compliant trustee resolutions
By treating trust distributions as part of an ongoing strategy rather than a last-minute task, business owners can improve consistency, reduce uncertainty and maintain greater control over tax outcomes.
Conclusion: Why Trust Distribution Timing Matters
Trust distribution resolutions are far more than an administrative EOFY requirement. They are one of the most important tax planning tools available to Australian business owners and investors.
Failing to complete trust distribution resolutions before 30 June can result in:
- Higher tax rates
- Lost flexibility
- Reduced tax planning opportunities
- Increased stress and uncertainty
The most effective trust strategies are rarely built at the last minute.
Starting the process earlier allows more time to review financial positions, consider alternative scenarios and align trust outcomes with broader business and wealth objectives. Because when trust distributions are planned properly before 30 June, the result is not simply compliance, it is greater control over long-term financial outcomes.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
What is a Testamentary Trust
A testamentary trust is a trust created by a Will. It is generally a discretionary trust – one where the Trustee has full discretion about who benefits, and to what extent, under the trust.
Why would I use a Testamentary Trust?
Testamentary trusts can make sure the inheritance reaches the intended recipients. An independent trustee can guarantee that vulnerable beneficiaries, such as very young children or the ill, incapacitated, unstable or disabled, will be provided for. Properly drafted, trusts can also guard against the often-divisive aftermath of divorce, and ensure that in the event of remarriage, assets will be passed on to the children or grandchildren of the testator.
Testamentary trusts are also a wise precaution if the beneficiaries may face legal action or bankruptcy, such as those in professions frequently subject to litigation, or high-risk business. This form of protection is often referred to as Asset Protection.
Can a Will-Maker Restrict the Terms of a Testamentary Trust?
The terms of testamentary trusts are contained in the Will. They can include restrictions on any or all of the beneficiaries or conversely, grant them extensive control. In effect, these can enable you as the Will-maker, or testator, to rule from the grave. It is up to the testator whether they vest control in the beneficiaries or in the hands of an independent trustee. Giving control to the beneficiaries allows a greater degree of flexibility; but a managerial trustee may be better if the beneficiaries are not able to control their own finances.
How do Testamentary Trusts Work?
Testamentary trusts are drafted to mimic the operation of a discretionary trust such as a family trust: the testamentary trust will have a broad range of discretionary beneficiaries, usually the members of an extended family.
The trustee of the testamentary trust selects from the class of beneficiaries which person or people who will receive a gift of trust income or trust capital. Until the trustee elects to distribute to a beneficiary, no person has a vested interest in the assets of the trust.
Careful drafting of the testamentary trust will ensure that the beneficiary selected, who becomes a beneficiary, only has an interest in the trust to the extent that the trustee has determined. The trustee of the testamentary trust may be the executor of the deceased estate or may be some other person, who will be appointed by the Will or pursuant to a formula contained in the Will.
Often the trustee will be the person to whom the Willmaker, but for the testamentary trust, would bequeath their assets or a good part of them.
Difference of Standard Will and Testamentary Trust Will
A Standard Will, in its simplest form, is a testamentary document confirming choice of executors, beneficiaries and testamentary wishes regarding the distribution of their estate. It does not, however, offer any asset protection or tax minimisation benefits.
A Testamentary Trust Will is a type of Will that establishes a Trust or Trusts upon the death of the will maker. This kind of Will is designed to protect the will makers assets as they will belong to the beneficiaries’ Trust rather than the individual. This enables flexibility for how capital and income generated by those assets is distributed. The Trust only becomes active once the will maker is deceased. The Trustees who decide how the income is distributed can also be beneficiaries of the Trust. However, the Trustees must act in accordance with the provisions set out in the Will regarding how the Trust is to be managed.
There are two commonly utilised types of Testamentary Trusts:
Discretionary Testamentary Trusts
- where the Executor gives the beneficiary the option to take part or all of their inheritance via a Testamentary Trust. The primary beneficiary has the power to remove and appoint the trustee and they can appoint themselves to manage their inheritance inside the Trust.
Protective Testamentary Trusts
- where a Beneficiary must take their inheritance via the Trust and does not have the option to appoint or remove trustees. This is useful where the beneficiary is not in a position to responsibly manage their inheritance due to age, disability or spendthrift tendencies and is often used when parents are leaving assets to their underage children.
The potential advantages of Testamentary Trusts include:
- Asset Protection for the beneficiaries in the event of marriage or relationship breakdown (if the Trust is utilised effectively);
- Asset Protection for vulnerable beneficiaries including spendthrift beneficiaries, disabled beneficiaries or beneficiaries with a drug, alcohol or gambling problem;
- Asset Protection for “at risk” professionals or beneficiaries who may face claims from creditors or bankruptcy;
- Protection of pension entitlements;
- Income splitting advantages e.g. adult children, minors and/or other relatives on low incomes;
- Income tax advantages for children under 18 (who are taxed at adult rates instead of penalty rates outside the Testamentary Trusts environment); and
- Flexibility for the Trustee to exercise discretion about management and investment of capital and to take account of changing needs of beneficiaries.
- Tax Advantages
If a beneficiary takes their inheritance in their personal name (via a Standard Will), they will pay tax on the income generated from their inheritance at their personal marginal tax rate.
There may be significant tax advantages in taking an inheritance through a Testamentary Trust, particularly where the beneficiary has:
- a high personal marginal tax rate
- a partner on a lower income
- children and/or grandchildren who are minors or who have no, or a lower taxable income
- a tax free threshold of $18,200 (all Australian residents)
- a tax free threshold of $20,542 (Australian residents who qualify for low-income offsets).
The Trustee or Trustees can choose to distribute the income generated by the Trust in a way that minimises the tax burden of the beneficiaries. Depending upon the assets held in the Trust, a Testamentary Trust can potentially save thousands of dollars over its lifetime.
We also strongly recommends that you seek independent accounting, financial, taxation, and legal advice, tailored to your specific objectives, financial situation, or needs, prior to making any investment decision.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au , or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
The Benefits of Estate Planning
Time is everything when it comes to estate planning. Regardless of whether procrastination is your default mode, it’s essential to set aside any delaying tendencies and attend to your affairs promptly. By establishing a robust estate plan, you can lead a worry-free life, confident that your loved ones will be secure and comfortable in the face of unforeseen circumstances.
This article aims to highlight the advantages of estate planning. Our objective is to assist you in understanding the benefits of estate planning, providing a compelling reason to prioritise and initiate your plan without delay.
What is estate planning?
Estate planning is the process of arranging for the management and disposal of an individual’s assets, usually after their death, but it can also occur during their lifetime under certain circumstances, such as if the person is permanently incapacitated.
The process involves creating a comprehensive plan that outlines how assets will be distributed, who will be responsible for managing the estate, and how potential taxes and expenses will be addressed.
The key objectives of estate planning include asset protection, minimising tax liabilities, providing for loved ones, retaining any social security entitlements and preserving wealth for future generations of the family. However, although you can start accessing some of your super once you reach your preservation age, you won’t have full access to your super until you’ve also met a condition of release.
What are the key components of an estate plan
A well-structured estate plan typically comprises several key components. These include:
- Will: this outlines the distribution of estate assets after an individual’s death and appoints an executor who is responsible for administering the estate according to the terms laid out in the will
- Power of attorney: allows an individual to appoint someone they trust to manage their financial and legal affairs. An Enduring Power of Attorney is a special type of Power of Attorney that continues to operate when the person appointing them becomes incapacitated or unable to make decisions for themselves
- Enduring Guardianship: an Enduring Guardian is someone you appoint to make decisions about your health and lifestyle (as opposed to your legal and financial decisions, which are to be made by an Enduring Attorney). An Enduring Power of Guardianship will usually operate when the person appointing them is unable to make lifestyle and health decisions for themselves
- Advance care directive: also known as a living will, this allows individuals to express their wishes regarding medical treatment and end-of-life care in the event that they are unable to communicate those wishes in the future
- Trusts: a structure where a trustee (individual or company) administers assets for the benefit of designated beneficiaries, which are then given to the beneficiaries at a pre-determined later date. For example, a trust may be set up for a child but is only payable upon their 21st birthday. Trusts can be used to minimise taxes and protect assets
- Super: allocation of funds from your super is a vital component of estate planning in Australia, given the typically large sum of money involved. Addressing this as part of your estate planning ensures that the funds accumulated in your super account are distributed according to your wishes, and also in the most tax-efficient manner. You can nominate eligible beneficiaries to receive their superannuation death benefits. It is essential to review and update these nominations regularly to ensure they align with any change in your personal circumstances, such as marriage, divorce, or the birth of a child, and to ensure they remain valid and do not lapse
- Guardianship of minor children: for individuals with dependent children, naming a guardian can assist to ensure the children are cared for if both parents pass away This is usually done by a clause in each parent’s Will.
What are the legal considerations for estate planning
When creating an estate plan in Australia, it is essential to consider the following legal aspects:
- Validity: all estate planning documents must meet the legal requirements to be considered valid. It is advisable to seek legal advice to ensure compliance with relevant legislation, such as the Succession Act or Wills Act in each state or territory.
- Tax implications: estate planning involves considering the tax consequences of transferring assets to beneficiaries. It is crucial to understand the impact of capital gains tax, stamp duty, and income tax when making decisions regarding asset distribution
- Family law considerations: estate planning can be affected by family law matters, such as divorce or separation. You should consider how these factors may influence your estate plan and seek legal advice if necessary
- Capacity: to create a valid will, individuals must have capacity, meaning they must be of sound mind and understand the implications of their decisions. It’s important to ensure that the will is created when the person is in good mental health to avoid potential challenges in the future.
Always seek professional guidance on estate planning
Given the complexity and legal considerations involved, it is highly recommended to seek professional guidance when creating an estate plan in Australia.
Estate planning professionals, such as estate lawyers, financial advisers, and accountants, can provide expert advice tailored to individual circumstances. They can assist in:
- Structuring the estate plan
- Navigating tax implications
- Ensuring compliance with legal requirements
- Addressing any specific concerns or goals
- Explore various strategies to protect assets
- Minimise tax liabilities
- Maximise the benefits for beneficiaries. This may include setting up testamentary trusts, establishing charitable bequests, or utilising superannuation strategies.
Regularly review and update your estate plan
Estate planning is not a one-time set-and-forget task but rather an ongoing process. It is vital to review and update the estate plan regularly, especially in the event of significant life events such as marriage, divorce, birth of children, or changes in financial circumstances.
Regular reviews ensure that the estate plan remains relevant, aligns with current objectives, and reflects any changes in laws or regulations.
Estate planning checklist
First, gather essential documents. These should include:
- Will: your last will and testament will specify how you want your assets to be distributed after your death
- Super death benefits nomination: collect documents related to your super account, including any insurance policies and your previous death benefits nomination
- Trust documents: if you are a beneficiary, trustee, or appointor under a family trust, gather the trust agreement and any related documents.
- Enduring Power of attorney: an enduring power of attorney appoints one or more persons to make financial and legal decisions on your behalf if you become incapacitated
- Enduring Power of Guardianship: an enduring power of guardianship appoints one or more people to make lifestyle and health decisions on your behalf if you become unable to do so
- Healthcare directive: an advance care directive (also known as a living will) outlines your medical wishes. Your Enduring Guardian can express your wishes relating to your healthcare on your behalf in the event that you are incapable of expressing them yourself. If you have not appointed an Enduring Guardian, you can nominate responsible persons in your advanced care directive to give effect to your wishes
- Insurance policies: collect documents related to life insurance, disability insurance, and critical illness insurance.
Then, make a list of assets, such as:
- Bank accounts: list all your bank accounts, including checking, savings, and investment accounts
- Real estate: keep records of any properties you own, including homes, land, or rental properties
- Investments: list your stocks, bonds, mutual funds, and other investment holdings.
- Super accounts: note your super fund details and any other retirement accounts
- Personal property: include valuable possessions such as vehicles, jewellery, artwork, and collectibles.
Next, decide who you want to inherit your assets. Consider immediate family members, relatives, friends, and charitable organisations. Specify the percentage or specific assets you want each beneficiary to receive.
If you have young children, designate a guardian to care for them if you pass away.
Bottom line: estate planning in Australia is a multifaceted process that requires careful consideration of various legal, financial, and personal factors. A comprehensive estate plan is one way to see that your assets are distributed according to your wishes, whilst minimising tax implications and giving yourself peace of mind, knowing that your loved ones will be provided for long after you’re gone.
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au , or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
What is a Trust
Although trusts are common, they are often poorly understood. Setting up a trust is often driven by a new business opportunity, a growing business, or a need to better structure your investments. When set up correctly, there are clear tax benefits when it comes to operating as a family trust.
The importance of the correct structure in which to hold your investment, (be it property or any other) and its correct use could mean the difference between losing or retaining your assets and the paying or not paying of hundreds of thousands of dollars in excess tax over the longer term. Trusts are a fundamental element in the planning of business, investment, and family financial affairs. There are many examples of how trusts figure in everyday transactions.
Why a Trust and which kind?
Apart from any tax benefits that might be associated with a trust, there are also benefits that can arise from the flexibility that a trust affords in responding to changed circumstances.
A trust can give some protection from creditors and can accommodate an employer/employee relationship. In family matters, the flexibility, control, and limited liability aspects combined with potential tax savings, make discretionary trusts very popular. There are strengths and weaknesses associated with trusts and it is important for clients to understand what they are and how the trust will evolve with changed circumstances.
You should always obtain advice from a specialist tax adviser and a solicitor when considering setting up a trust. Although a trust can be established without a written document, it is preferable to have a formal deed known as a declaration of trust or a deed of settlement.
All types of trusts (with the exception of Superannuation Trusts) established in either NSW, NT or Victoria need to be duty stamped upon execution.
How Family/Discretionary Trusts Operate
A discretionary trust or family trust is a common type of trust used to hold assets or run a family business. It is one of the most common trust structures. Essentially, it is a relationship where a trustee holds property or assets for the benefit of a beneficiary or beneficiaries.
The one who holds the assets is called a trustee. A trust is not a legal entity and it requires the establishment of a legal entity to enter into agreement for it on behalf of the trust. Trustees can either be an individual or a company.
The Trust is the relationship or structure between trustees and beneficiaries. You could think of a Trust as a container of sorts, that things are placed within. All assets placed into the container become property of the Trust, controlled by the trustee for the sake of the beneficiary. See the diagram below:

Who are parties to a Trust?
The Trustee
The trustee can be an individual, individuals or a company and they are the legal entity who owns the assets and makes decisions on the trust’s behalf. There can be more than one trustee and more than one beneficiary. In most cases, the trustees are usually parents or a company that they own, and the beneficiaries are their children or dependants.
The trustee owns and controls the business’ assets, distributes income, and must comply with the obligations of the trust deed and act with the best interests of the beneficiaries in mind. The trustee is also responsible for registering the tax purposes, lodging tax returns and meeting any other tax obligations on behalf of the trust.
Who will be Trustee?
Note as the decision maker, the trustee will be held responsible for actions by the trust, as is the case with any owner. We would normally recommend a company to be the trustee as the company would not own any assets and as such gives you an extra layer of protection, especially if you own assets in your name. If you as an individual are trustee, then your personal assets may be at risk in the event of legal action against the trust which insurance will or does not cover.
Beneficiaries
The beneficiaries are the people entitled to the income and assets of the trust. The beneficiaries of the trust are usually members of a family (family group), as well as companies and trusts that are controlled by that family. For example, the primary or default beneficiaries may be a parent or parents and the secondary beneficiaries maybe children, grandparents, companies etc.
The role of the default beneficiary is to receive and/or decide the direction of any funds that aren’t allocated by the trustee. It’s also important to note that you cannot change the default beneficiary without triggering capital gains tax and stamp duty. Beneficiaries will generally include their share of the trust’s net income as income in their own tax returns and if they receive income from other sources they will be taxed for these as well.
Primary Beneficiaries
You need to identify the primary beneficiaries by name. Depending on the deed the beneficiaries can be changed at any time and you can make distributions to anyone even if you do not identify them here. With certain deeds there may be tax consequences so get this checked before doing so.
Financial institutions, when looking at a loan application in the trust name or an individually named borrower, will also review this section of the trust and would normally require any named initial beneficiaries to be part of a loan application. Related parties to the initial beneficiaries are not normally party to the trust and as such are not normally part of the above review unless they have actually received distributions. The trust deed provides that the beneficiaries include such persons as are related to you as follows and as such there is no need to specifically identify them.
Note also that beneficiaries include companies and trusts associated with all the persons specifically identified
Appointor
The Appointor (sometimes called the Principal or Guardian) has, in fact, the most powerful role in a trust and should be carefully selected. While the trustee is the one who decides what happens to the assets, funds and profits of the trust, it is the Appointor who has the power to change the trustee and appoint a new one. It is important to consult with your solicitor and include in your will the transfer of this role upon your death and that this power is passed on to the person of your choosing.
Settlor
The Settlor should never be the beneficiary of the Trust to avoid income tax issues for the trustee. The Settlor is someone who puts down a sum of money to start the trust, commonly around $10. Once the trust is established, the Settlor has no other role, entitlements, rights or connection to the trust. This $10 is a gift to commence (settle) the trust. It takes on the literal meaning of a gift i.e. you cannot give it yourself and the giver must not get back anything in return. Therefore the settlor can never be a beneficiary of the trust. We would normally see a friend gift you the funds. The settlor will need to sign the trust deed when you get it, to confirm the gift, after which they have no involvement.
- Discretionary/Family Trusts: Advantages
Asset Protection
Many business owners face a degree of risk in owning a business, for example if the business fails, they may be sued personally or put at risk of bankruptcy. Similarly, those in partnerships, particularly those with bank debts, can face similar risks. Assets that are within a family trust are protected from creditors, so even if a claim is made against you, the assets are not in your name and therefore cannot be accessed in these circumstances.
Tax Advantages
Operating your business from a family trust and having the company act as trustee means you can retain the limited liability benefits of a company structure while taking advantage of the tax flexibility benefits of a family trust.
When set up correctly, there are clear family trust tax benefits for individuals and businesses. Because the trust itself does not pay tax, beneficiaries are taxed based on the amount of income placed in their name (as well as any other income they may have from other sources). A family trust allows you to distribute profit amongst family members to utilise their income tax “tax-free thresholds”. If the business’ profits grow too large to distribute effectively, a family trust can also distribute to a separate company to cap the tax rate at 30 percent.
Keeping it in the Family
Whether you’re looking to keep your family home in the family or want to stagger inheritance distribution to ensure it’s not all spent at once, a family trust prevents, will contests and secures assets. Assets held within the trust do not form part of a deceased estate preventing contests to a Will or your child’s spouse claiming their share of an inheritance.
A family trust can provide long-term financial support for your children or grandchildren, allowing you to invest in their long-term education and distribute family assets to future generations. A family trust can also be a great way to protect vulnerable beneficiaries who may make poor spending decisions if they were to control their own assets.
- Family/ Discretionary Trusts: Disadvantages
Any income earned by the trust that is not distributed is taxed at the highest marginal tax rate. If you do find you are making a lot of profit as a family trust, those profits must be pushed out to beneficiaries. You could run out of beneficiaries and those beneficiaries will be paying highest tax rate. With a family trust, you can add additional beneficiaries if the trust deed allows for it, but care must be taken as capital gains tax and stamp duty may be triggered if done incorrectly. The trust cannot allocate tax losses to beneficiaries either.
Family Matters
There can be challenges in running the trust when other family issues occur. There can also be some complexities regarding succession planning and asset allocation upon the death of the trustee. With a Will, you can dictate what goes to who, however, a family trust is separate to an individual’s will and you may be able to choose who controls the trust, you don’t dictate how they control it.
Negative Gearing
One of the disadvantages of a discretionary trust is the loss of some benefits associated with negative gearing investments through the trust. Namely, if a discretionary trust acquires a property and borrows to invest in that property, then any losses generated are accumulated in the trust and cannot be distributed to the beneficiaries.
This is not such a problem if the discretionary trust itself other sources of income has but can give rise to significant problems for, say, PAYG-type taxpayers who wish to acquire a property and negatively gear at the same time.
Obviously, the advantages of having the property owned by a discretionary trust may be outweighed in this case by the disadvantage of any negative gearing being generated in the trust itself. The development of a unit trust (one where the discretionary nature is preserved in the trust deed but allows the issue of units) is an attempt to overcome this negative gearing problem.
Family Trust vs Company
One of the key differences between a trustee company and a trading company, is that the trustee company doesn’t trade, it doesn’t have its own tax file number and it doesn’t lodge a tax return of its own. It simply makes decisions for and on behalf of the family trust.
Some other important distinctions are:
- Companies cannot access the 50% capital gains discount, whereas a family trust can. Small business capital gains tax discounts can be accessed by both
- A company is paying tax at 30% or 25% and pays tax from the first dollar. However, a family trust doesn’t pay tax and profits are pushed out each year
- A company can accumulate profits and reinvest those profits into the business as working capital
- Companies are great for doing business with unrelated parties and you will be protected by the Corporations Act. As for a trust, if a party is not within family group, you cannot bring them into the trust with you
How can we help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any particular person. Any advice contained on this page and on this website is General Advice and does not take into account any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability [except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.