




Crypto and CGT – What Investors Need to Know
Bought, sold, swapped or spent cryptocurrency during the financial year?If you are an Australian crypto investor, it is important to understand how capital gains tax (CGT) applies to cryptocurrency and what you need to report to the Australian Taxation Office (ATO).
Crypto is not treated as tax-free digital money simply because it exists on a blockchain.For most investors, crypto assets are treated as CGT assets, meaning a taxable event can occur when you dispose of them.
And importantly, disposing of crypto does not just mean converting it back into Australian dollars.Selling, swapping one crypto asset for another, gifting crypto or using crypto to purchase goods or services can all have tax consequences.
Is Cryptocurrency Subject to CGT in Australia?
For most individual investors, the answer is yes.The ATO generally treats cryptocurrency and other crypto assets as CGT assets.If you acquire crypto as an investment and later dispose of it, you may make a capital gain or capital loss.
A disposal can occur when you:
- Sell crypto for Australian dollars
- Convert crypto into another fiat currency
- Swap Bitcoin for Ethereum or another crypto asset
- Use crypto to purchase goods or services
- Gift crypto to another person
- Dispose of crypto in another transaction that changes ownership
The important point is that you do not have to cash out into Australian dollars for CGT to apply.
A crypto-to-crypto swap can itself be a CGT event.For example, if you bought Bitcoin for $20,000 and later exchanged it for Ethereum when the Bitcoin was worth $35,000, the exchange can trigger a CGT event. The fact that you did not receive cash does not necessarily defer the tax obligation.
How Do You Calculate a Crypto Capital Gain?
The calculation is the same as for other CGT assets, such as shares.
Generally:
Capital gain = Capital proceeds – Cost base
What About the 50% CGT Discount and the Changes from 1 July 2027?
Your cost base generally includes what you paid for the crypto plus eligible transaction costs. Crypto transactions must be valued in Australian dollars, using reliable exchange-rate information where needed. As crypto prices can change quickly, keep accurate records of the date, time and value of each transaction.
Under the current rules, one of the important concessions available to individual crypto investors is the 50% CGT discount.Australian tax residents may qualify for the 50% CGT discount on eligible crypto assets held for at least 12 months. However, the CGT rules are changing from 1 July 2027.
Gains that accrue up to 30 June 2027 can continue to access the existing 50% discount, while gains accruing from 1 July 2027 will generally move to the new inflation-based indexation rules and a 30% minimum tax on real capital gains. These changes apply to CGT assets generally, including crypto assets, so investors holding crypto across the transition date should keep appropriate records.
The treatment will depend on the rules applying when the gain is realised and how the pre- and post-1 July 2027 gain is calculated.
Crypto Trading Can Be Different from Investing
Not everyone who trades cryptocurrency is necessarily treated as an investor.
The tax treatment can depend on factors such as:
- The purpose and intention behind your activities
- The frequency and volume of transactions
- How systematically you trade
- The level of organisation involved
- The amount of capital invested
- Whether your activities have the characteristics of a business
If your activities amount to carrying on a business of cryptocurrency trading, different income tax rules may apply rather than simply treating every transaction under the individual CGT investor rules.This distinction can become particularly important for people undertaking frequent or highly organised trading.
Crypto Losses Can Still Be Valuable
Crypto investments can result in both gains and losses. Capital losses generally cannot be deducted from your salary or other ordinary income, but they can be used to offset capital gains. Unused capital losses can usually be carried forward to future years.Capital losses are applied before any applicable CGT discount or other CGT concession is calculated.
What About Staking Rewards and Airdrops?
Crypto tax becomes more complicated when you move beyond straightforward buying and selling. For example, the ATO states that staking rewards can be ordinary income. The money value of the tokens received as staking rewards is generally included as assessable income when received.
A later disposal of those tokens can create a separate CGT event. Similarly, some airdropped crypto assets can have income tax consequences when received. The ATO’s current guidance states that the money value of an established token received by airdrop is ordinary income at the time it is received.
This can create two separate tax considerations:
- Income tax when the reward or relevant airdrop is received.
- CGT when the crypto is subsequently disposed of.
The same principle can make DeFi, liquidity pools, lending, wrapping and other crypto activities more difficult to report correctly.
What Happens with Crypto from a Chain Split?
A chain split can also create questions about your tax position. Under current ATO guidance, where an individual investor receives a new crypto asset because of a chain split, such as Bitcoin Cash being received following the Bitcoin split, there is generally no immediate ordinary income or capital gain merely because the new asset was received. However, when the new crypto asset is later disposed of, CGT may apply.
The ATO states that the cost base of the new asset received from a chain split is generally nil for these purposes. Because the treatment can depend on the circumstances, investors should keep records of when and how the new asset was received.
Don’t Assume Crypto Held for Personal Use Is Automatically Tax-Free
Crypto can qualify as a personal use asset where it is kept or used mainly to purchase items for personal use or consumption.A capital gain on a qualifying personal use crypto asset acquired for less than $10,000 may be disregarded.
However, the $10,000 threshold is not a general crypto tax exemption. Crypto held mainly as an investment, as part of a profit-making scheme or in carrying on a business will generally not qualify simply because it is later used to make a personal purchase. The way the crypto was actually kept and used over the ownership period is important.
The ATO Can Match Your Crypto Transactions
If you are wondering whether the ATO knows about your crypto activity, it is important to understand its crypto asset data-matching program. The ATO obtains account and transaction information through data-matching programs and matches information against taxpayer records to identify crypto activity and check whether transactions have been correctly reported.
These programs and data sources can change over time, so investors should not assume that transactions are outside the ATO’s visibility simply because they occurred through a particular platform or wallet. A common misconception is that moving cryptocurrency between wallets or using an offshore platform means the activity will automatically be invisible to the tax authorities.
That should not be relied upon. Australia also has a broader regulatory environment around digital assets. ASIC’s current guidance notes that Australian laws can apply to digital asset businesses and services, including certain crypto-related financial products and platforms.
Keep Detailed Crypto Tax Records
Good record keeping is one of the most important parts of managing your crypto tax obligations.The ATO says you need to keep records of your crypto assets and transactions.
Useful records can include:
- Date and time of each transaction
- Type and quantity of crypto bought or sold
- Australian dollar value at the time
- Purchase price
- Sale or disposal value
- Transaction and network fees
- Exchange or platform used
- Wallet addresses
- Details of transfers between wallets
- Records of staking rewards and airdrops
- Relevant transaction IDs
- Bank statements and exchange statements
If you have used several exchanges or wallets, consolidating your records before preparing your tax return can be particularly important.
How Do You Report Crypto on Your Tax Return?
For individuals lodging through myTax, crypto capital gains and losses are generally reported through the Capital gains or losses section. Companies, trusts and superannuation funds can have different tax treatment and reporting requirements, so their crypto transactions should be reviewed according to the entity’s circumstances.
If your crypto activity includes:
- Frequent trading
- Staking
- DeFi
- Mining
- Airdrops
- Chain splits
- Transactions across multiple platforms
Calculating the correct tax position can become considerably more complicated.
The Bottom Line for Crypto Investors
Crypto tax is no longer something Australian investors can afford to treat as an afterthought. Whether you hold Bitcoin, Ethereum, stablecoins or other digital assets, it is important to understand:
- When a CGT event occurs
- How income such as staking rewards may be taxed
- How the CGT changes from 1 July 2027 may affect future gains
- What records you need to support your tax position
How Camden Professionals Can Help
At Camden Professionals, we can help you understand the Australian tax treatment of your crypto activity, review tax reports and supporting records, identify potential CGT events, and assess capital gains, losses and other taxable crypto income.
If you have traded across multiple exchanges or wallets, used DeFi platforms, or have a large transaction history, the transaction data may first need to be consolidated and reconciled using appropriate crypto tax software or by a specialist provider. Any substantial reconstruction or transaction-by-transaction review would be separately scoped before we proceed.
Frequently Asked Questions
Is crypto subject to CGT in Australia?
Yes. Crypto acquired as an investment is generally treated as a CGT asset, and disposing of it can trigger a capital gain or loss.
Do I pay CGT when I swap one cryptocurrency for another?
Generally, yes. Swapping one crypto asset for another is a disposal and can trigger a CGT event.
Do I pay tax if I only sell crypto for AUD?
Selling crypto for Australian dollars can trigger a CGT event. However, other transactions, including crypto-to-crypto swaps and spending crypto, can also trigger CGT.
Can I claim crypto losses against my salary?
Generally, no. Capital losses are generally used against capital gains rather than deducted directly from salary or other ordinary income.
Are staking rewards taxable?
Generally, staking rewards can be assessable as ordinary income when received. A later disposal may also have CGT consequences.
Does the ATO know about my crypto transactions?
The ATO operates a crypto asset data-matching program that obtains information from designated service providers and matches transaction information against taxpayer records.
How long should I keep crypto tax records?
You should retain appropriate records supporting your tax position, including transaction details, values, dates and costs. Your tax adviser can help determine the record-keeping requirements relevant to your circumstances.
Sources
- Australian Taxation Office (ATO)
- Reserve Bank of Australia (RBA)
- Australian Securities and Investments Commission (ASIC)
- Moneysmart
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only.It does not take into account your individual circumstances and should not be relied upon as personal tax, accounting, legal, financial or investment advice.
Tax outcomes can depend on your individual circumstances and the law applying at the relevant time. You should obtain professional advice appropriate to your circumstances before acting on the information contained on this page.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Cyber Security: Practical Tips to Protect Your Business in 2026
Cyber security is no longer just an IT issue.For a small business, a cyber-attack can mean lost money, disrupted operations, stolen customer information and a lot of time spent trying to recover.The good news is that improving your small business cyber security does not have to be complicated or expensive.
Many of the most effective steps are simple measures such as using multi-factor authentication, keeping software updated, backing up important information and making sure your staff know how to spot scams.
The Australian Signals Directorate’s Australian Cyber Security Centre (ASD’s ACSC) reported more than 84,700 cybercrime reports in 2024–25.The average self-reported cost of cybercrime for a small business was approximately $56,600, up 14% from the previous year. (Cyber.gov.au) For a small business, that can be a significant financial and operational hit.
Why Small Businesses Need to Take Cyber Security Seriously
Cyber criminals do not only target large organisations.Small businesses can be attractive targets because they often hold valuable information while having fewer resources available for cyber security.
Common threats include:
- Phishing emails and text messages
- Business email compromise
- Fake invoices and payment requests
- Stolen passwords
- Ransomware
- Malware
- Website attacks
- Identity theft
- Unauthorised access to cloud accounts
Tip: Don’t assume an email is genuine
If an email asks you to change bank details, make an urgent payment or provide sensitive information, stop and check. Call the supplier or customer using a phone number you already have, rather than replying to the email or using contact details included in the message.
Start With Multi-Factor Authentication
One of the simplest ways to improve your cyber security is to turn on multi-factor authentication (MFA). MFA requires more than just a username and password to access an account. For example, you may need to enter a code from an authentication app after entering your password. The ASD recommends MFA as one of the most effective controls for protecting online services, systems and data.
Start with your most important accounts, including:
- Business email
- Accounting and bookkeeping software
- Online banking
- Cloud storage
- Microsoft 365 or Google Workspace
- Website administration
- Social media accounts
Small business tip:
If an account offers MFA, turn it on rather than waiting for a cyber incident to happen.
Use Strong, Unique Passwords
Using the same password across multiple accounts creates an unnecessary risk. If one account is compromised and you have reused that password elsewhere, criminals may try it against your email, accounting software, cloud storage or other business systems. The ASD recommends using strong passwords or passphrases and a password manager to create and store unique passwords.
A practical approach is to:
- Use a different password for every important account
- Use long passphrases
- Avoid sharing passwords between staff
- Use a reputable password manager
- Change passwords if you believe an account has been compromised
Keep Your Software and Devices Updated
Software updates are not just about adding new features. They often fix security weaknesses that criminals could use to access your systems.
Make sure you regularly update:
- Computers and laptops
- Phones and tablets
- Accounting software
- Operating systems
- Internet browsers
- Wi-Fi routers
- Website software and plugins
- Security software
Where possible, turn on automatic updates.
Small business tip:
If an old computer, server or software package is no longer supported with security updates, talk to your IT provider about replacing it.
Back Up Your Important Business Information
Imagine losing access to your accounting records, customer files, invoices and other important documents tomorrow. Could your business continue operating? Regular backups can make the difference between a serious disruption and a much faster recovery. The ASD recommends that businesses back up important information regularly and, importantly, test that the backups can be restored.
Your backup plan should consider:
- What information needs to be backed up
- How often backups occur
- Where backups are stored
- Who manages them
- How long they are retained
- How often restoration is tested
Small business tip:
Don’t assume that having files stored in the cloud automatically means you have a complete backup.Check what your provider actually backs up and how you would recover your information.
Train Your Staff to Spot Scams
Technology can only do so much. Your employees are also an important part of your cyber security. Make sure staff know how to identify suspicious emails, messages and payment requests.
Warning signs can include:
- An unexpected request for money
- A message creating a sense of urgency
- An unfamiliar sender
- A suspicious link
- A request for passwords or sensitive information
- A sudden change to supplier bank details
- An email that looks almost identical to a genuine one
Training does not have to be complicated. A short discussion every few months can help keep cyber security front of mind.
Review Who Has Access to Your Systems
Small businesses often grow quickly, and access to systems can be forgotten as people change roles or leave.
Regularly review who can access:
- Accounting software
- Payroll
- Banking
- Customer databases
- Cloud storage
- Website administration
- Social media
- Business management software
Remove access when someone leaves and ensure staff only have access to the systems and information they need. Use individual accounts rather than shared passwords to improve security and accountability.
Don’t Forget Your Suppliers and IT Provider
Many small businesses rely on external providers for IT, accounting, payroll, websites, cloud software and other services.Outsourcing these services does not mean you can ignore the associated cyber risks.
Ask your key providers:
- How is our information protected?
- Is MFA enabled?
- How is our data backed up?
- Who can access our information?
- What happens if there is a cyber incident?
- How quickly will we be notified?
Have a Simple Cyber Incident Plan
You do not need a complicated document. At a minimum, know what you will do if:
- Someone’s email account is hacked
- A fraudulent payment is made
- Customer information is stolen
- Your systems are infected with ransomware
- Your website is compromised
- You lose access to important files
Your plan should include who to contact, which accounts need to be secured and how important systems can be restored. The ASD also provides resources for small businesses, including an Exercise in a Box and a small business cyber security checklist.
Small business tip:
Don’t wait until an attack happens to work out who is responsible.
A Simple Cyber Security Checklist
If you are not sure where to start, work through these five steps:
1. Turn on MFA
Start with email, banking, accounting and cloud systems.
2. Update everything
Turn on automatic updates where possible.
3. Back up important information
Make sure backups are secure and test that you can restore them.
4. Train your team
Make sure everyone knows how to identify phishing and payment scams.
5. Review access
Remove old accounts and check who can access sensitive information. These actions align with the ASD’s current small business guidance, which identifies MFA, software updates and backups as key starting points.
Cyber Security Is a Business Issue
You do not need to become a cyber security expert to protect your business.The important thing is to take practical steps, regularly review your systems and make cyber security part of your normal business routine.
For many small businesses, improving security starts with a few straightforward actions:
- Protect your accounts
- Update your systems
- Back up your data
- Make sure your team knows what to look for
If you are unsure whether your current systems and processes are adequately protected, speak with your IT provider or a qualified cyber security professional.
Frequently Asked Questions
What is the most important cyber security measure for a small business?
Start with multi-factor authentication, particularly for email, banking, accounting and cloud accounts. The ASD identifies MFA as one of the most effective security controls.
How often should a small business back up its data?
Backups should be performed regularly based on how important the information is and how quickly your business would need to recover. You should also test that backups can be restored.
What is the Essential Eight?
The Essential Eight is an Australian cyber security framework developed by the ASD. It includes strategies such as patching applications and operating systems, MFA, restricting administrative privileges and regular backups.
Can a small business be targeted by cyber criminals?
Yes. Small businesses face phishing, email compromise, ransomware, identity fraud and other cyber threats. The ASD recorded an average self-reported cybercrime cost of about $56,600 for small businesses in 2024–25.
What should I do if I think my business has been hacked?
Secure affected accounts, contact your IT or cyber security provider and document what has happened. You can also contact the Australian Cyber Security Hotline on 1300 CYBER1 (1300 292 371).
How Can We Help?
We are accountants and tax advisers, not cyber security experts. Like any business that holds sensitive client information, however, cyber security is something we take seriously, and we work with specialist cyber security and IT providers to help protect our systems and data. We also believe that a good accountant should understand more than just your annual tax return.
When we work with a business, we look at the broader picture, including your business structure, tax position, asset protection, accounting systems and the risks or issues that may need attention as your business grows.
That means our conversations with clients can extend beyond tax. We may identify areas that should be discussed with another specialist, whether that is cyber security, legal matters, finance, insurance or another area outside our expertise, and point you in the right direction.
If you are looking for an accountant who takes the time to understand your business and works with you throughout the year, please contact Camden Professionals on 08 9221 5522 or email info@camdenprofessionals.com.au.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Renovating, Rebuilding or Developing Your Home? Property Tax and CGT Issues to Consider
Renovating, rebuilding, adding a granny flat or subdividing your property can be exciting, but it can also create unexpected tax consequences. For many homeowners, the starting point is simple: What will happen to the property when the project is finished?
Will it remain your family home, become an investment, be subdivided or will one of the new properties be sold? The answer can affect your capital gains tax (CGT) position, particularly with the proposed changes applying from 1 July 2027. The important thing is not to make a property decision based on tax alone. Instead, understand the potential tax consequences before you demolish, subdivide or start construction.
Why 1 July 2027 Could Matter
The proposed 2026 CGT reforms create an important transition point from 1 July 2027. For properties qualifying for the main residence exemption, their value around 30 June 2027 may be relevant to future CGT calculations.
If you plan to demolish, subdivide or redevelop, documenting the property’s condition and value before work begins may be important. However, starting a project after 1 July 2027 does not automatically mean a better tax outcome, as this depends on the property’s circumstances and future use.
Start by Defining Your Property Project
Before worrying about CGT, consider what you are trying to achieve. The proposed 2026 CGT reforms create an important transition point from 1 July 2027. The way gains arising before and after that date are treated may become relevant where a property is only partly exempt from CGT or is later subdivided, developed or used to produce income.
If you plan to demolish, subdivide or redevelop, keeping good records of the property’s condition, use and relevant values around key dates may be important. Whether a formal valuation is required will depend on the circumstances and the final form of the legislation. Starting a project after 1 July 2027 does not automatically mean a better tax outcome.
Common Property Projects
- Extending your existing home?
- Building a granny flat for family members?
- Subdividing your backyard?
- Building a duplex?
- Keeping one property and selling another?
- Developing the property with the intention of selling?
These projects can have very different tax outcomes. The purpose of the project, your intentions and what happens to the property afterwards can all affect whether the main residence exemption, CGT rules, income tax or GST apply.
Knock-Down Rebuild: Replacing Your Family Home
A knock-down rebuild can be straightforward from a tax perspective if you replace your existing family home with a new home that you move into as your main residence. Under the current rules, the main residence exemption can generally continue while the new home is being built, for up to four years, if the relevant conditions are met.
To access this rule, specific conditions must be satisfied, including generally moving into the new dwelling as soon as practicable after construction and continuing to use it as your main residence for at least three months. For example, if you demolish your old Perth home, rent somewhere temporarily and build a new family home on the same land, the property may continue to qualify for the main residence exemption during construction.
However, the outcome can change if:
- Construction takes longer than permitted
- You do not move into the new property as required
- Part of the property is rented
- Part of the land is sold
- You have another property that you treat as your main residence
Before demolishing the existing home, it is worth checking how the rules apply to your circumstances.
Renovations, Extensions and Granny Flats
A renovation or extension will generally not create a CGT problem simply because you have spent money improving your home. If the entire property continues to be your main residence, the main residence exemption will generally remain important. The position can become more complicated when part of the property is used to generate income. For example, you might build a granny flat and later rent it out, use part of the home as a business premises or convert a separate area into a long-term rental.
In these situations, keep records showing:
- When the income-producing use started
- The area being used
- Building and renovation costs
- Rental agreements
- Plans and drawings
- Relevant property valuations
Tip: Keep your renovation invoices even if you do not expect to sell the property soon.
Good records can become valuable if the property’s use changes in the future.
Subdividing Your Property
Subdividing your block and selling part of it can create a good opportunity, but it may also have tax consequences. For example, if you subdivide your backyard and sell the new vacant block separately from your home, the main residence exemption generally does not apply to the sale of that vacant block. The tax treatment will depend on factors such as the size and use of the land, your intentions and whether the sale is treated as a capital transaction or a profit-making activity. A valuation may also be useful to establish the value of different parts of the property at relevant dates.
What About Building a Duplex?
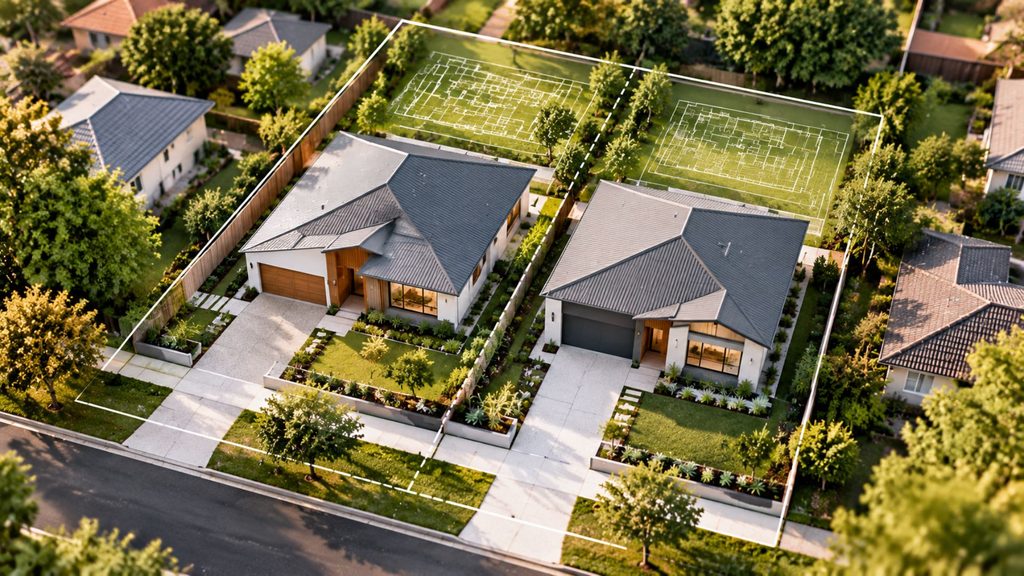
A duplex project can be more complicated because you may intend to live in one dwelling and sell the other. For example, you may own an existing family home, demolish it and construct two new dwellings. You then move into one and sell the other.
The tax outcome will depend on a range of factors, including:
- The property’s status before development
- The timing of the project
- The proposed CGT transition rules
- How the land is allocated between the two dwellings
- Your intention when the development began
- Whether the sale is treated as capital or ordinary income
- Whether GST applies
The proposed 1 July 2027 CGT changes make the timing and documentation of these projects particularly important. However, homeowners should not assume that delaying a project until after 1 July 2027 will automatically reduce tax.
The project should be assessed on its own facts before demolition, subdivision or construction begins.
The Important Question: Are You Building to Sell?
One of the biggest potential traps is assuming that the profit from selling a newly developed property will automatically be treated as a capital gain.
That is not necessarily the case.
If you develop a property with the intention of making a profit from selling it, the resulting profit may potentially be treated as ordinary income rather than a capital gain. GST may also need to be considered where new residential premises are sold.
Factors that may be relevant include:
- Your original intention
- The scale of the development
- How the project is financed
- The extent of construction
- Whether you have undertaken similar projects
- Whether the property was intended to be held or sold
This is particularly important for homeowners considering a duplex or subdivision where one or more properties will be sold. Tip: Get tax advice before signing building contracts or committing to a development if selling is part of the plan.
What If the Project Is Already Underway?
The transition to the proposed new CGT rules can become more complicated if your property has already been demolished or development has started before 1 July 2027.
The tax outcome may depend on:
- The property’s use
- The stage of the project
- How the final legislation applies to gains arising before and after the transition date
Detailed records of the property’s condition and the work completed around relevant dates may therefore become important.
Keep evidence such as:
- Dated photographs
- Council approvals
- Development applications
- Building plans
- Demolition invoices
- Building contracts
- Progress claims
- Finance records
- Property valuations
These records can help establish what the property looked like and what work had been completed at important dates.
Don’t Forget Inherited Properties
Inherited properties can have their own CGT rules. For example, special rules can apply when a deceased person’s main residence is inherited and subsequently sold.
The tax outcome can change if the property is:
- Rented
- Occupied
- Subdivided
- Redeveloped
If you inherit a property and are considering a major renovation, subdivision or development, get advice before starting work. A valuation at the date of death may be relevant depending on the CGT history of the property. Records and, where appropriate, valuation evidence around other relevant dates may also become important under the proposed reforms.
Keep Good Property Records
Property owners should not wait until they are ready to sell before looking for their records.
Keep:
- Purchase contracts
- Settlement statements
- Property valuations
- Renovation invoices
- Building contracts
- Council approvals
- Development applications
- Surveyor reports
- Subdivision costs
- Legal costs
- Finance records
- Dated photographs
- Records showing when the property was occupied or rented
Tip: Create a digital property folder and save documents as the project progresses. It is much easier than trying to reconstruct years of costs later.
What Should Property Owners Do Now?
If you are considering renovating, rebuilding or developing your home, start with the purpose of the project rather than the tax outcome.
Before you begin:
- Work out what you intend to do with the property.
- Consider whether the property will remain your main residence.
- Check whether part of the property will be rented or sold.
- Consider the potential CGT and GST implications.
- Obtain a valuation where appropriate.
- Keep detailed records before demolition or construction begins.
- Get professional advice before making major commitments.
The Bottom Line for Property Owners
Renovating, rebuilding or developing your home can create significant opportunities, but the tax implications should be considered before work begins. The proposed 1 July 2027 CGT changes make timing, documentation and record keeping particularly relevant for homeowners considering major property projects. Whether you are planning a knock-down rebuild, granny flat, subdivision or duplex, the best approach is to understand the tax implications before you demolish, develop or sell.
How Can We Help?
Property tax outcomes can depend heavily on decisions made before a project begins. If you are considering a knock-down rebuild, granny flat, subdivision, duplex or other development, we recommend speaking with us before you demolish, sign building contracts, change the property’s use or commit to a sale. We can help you understand the potential CGT, income tax and GST implications and identify the records or valuations that may be required.
Contact Camden Professionals on 08 9221 5522 or email info@camdenprofessionals.com.au to discuss your circumstances.
Frequently Asked Questions
Does renovating my home trigger CGT?
Generally, renovating your main residence does not by itself trigger CGT. However, tax issues can arise if part of the property is used to generate income or if the property is later subdivided or sold.
Does a knock-down rebuild affect my main residence exemption?
Potentially. The main residence rules can allow the exemption to continue during qualifying construction periods, generally for up to four years. Specific conditions apply.
Should I get my property valued before 1 July 2027?
For some property owners, valuation evidence around the transition date may be useful, particularly where the property is partly taxable, is being redeveloped or subdivided, or its use is changing. Whether a formal valuation is required will depend on your circumstances and the final legislation, so obtain advice before commissioning one solely for tax purposes.
Will waiting until after 1 July 2027 reduce my CGT?
Not necessarily. The proposed reforms may produce different outcomes depending on the property and project. The timing should be assessed alongside the main residence exemption, transition rules and intended use of the property.
Is building a duplex subject to CGT?
It can be. The tax treatment depends on factors including how the property was used, your intention, whether one dwelling is sold and whether the activity is treated as a capital transaction or a profit-making development.
Can GST apply when I sell a new property?
GST can potentially apply to the sale of new residential premises in certain circumstances. This should be considered before starting a development intended for sale.
General Information Warning
The material on this page and on this website has been prepared for general information purposes only and is not intended to provide tax advice for any person’s specific circumstances. Tax outcomes depend on the individual facts and the law applying at the relevant time.
Before acting on the information in this article, you should obtain professional advice that takes into account your particular circumstances and the details of the proposed transaction or property project.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Division 296 Tax Explained
If you’ve built up a substantial superannuation balance, there’s an important change to understand from the 2026–27 financial year.
What is Division 296 Tax?
Division 296 tax is an additional tax that applies to certain superannuation earnings where an individual’s Total Superannuation Balance (TSB) is above the legislated large superannuation balance threshold. For the 2026–27 financial year, that threshold is $3 million.
There is also a second threshold of $10 million, known as the very large superannuation balance threshold.
The Basic Structure:
Total Super Balance
Up to $3 million
No additional tax.
More than $3 million
Additional 15% on relevant earnings.
More than $10 million
Additional 15% above $3 million, plus a further 10% on relevant earnings attributable to the portion above $10 million.
For balances between $3 million and $10 million, Division 296 can impose an additional 15% tax on the relevant earnings attributable to the portion above $3 million. For the portion above the $10 million very large superannuation balance threshold, a further 10% applies, meaning the Division 296 component can reach 25% on the relevant earnings attributable to that portion.
When considered alongside the ordinary 15% tax generally applying to earnings in the accumulation phase, the combined tax rate can therefore be up to 30% and 40% respectively.
Importantly, these rates do not apply to your entire super balance.
For example, having $4 million in super does not mean the whole $4 million is taxed at 30%. The tax is calculated on relevant earnings attributable to the amount above the threshold.
When Does Division 296 Tax Start?
Division 296 applies from 1 July 2026, with 2026–27 being the first affected financial year. For the first year, your Total Superannuation Balance at 30 June 2027 is used to determine whether the rules apply.
The first Division 296 assessments are expected from the ATO during 2027–28, once super funds have reported the required information.
Who is Likely to be Affected?
Division 296 is aimed at individuals with substantial superannuation savings. You may be affected if your Total Superannuation Balance is above $3 million and you have relevant superannuation earnings for the year.
This can include people with:
- Large accumulation super accounts
- Self-managed super funds (SMSFs)
- Retirement-phase pensions
- Defined benefit interests
- Multiple superannuation accounts
- A combination of different types of super interests
It is important to remember that your TSB is not necessarily the same thing as the balance shown on one particular superannuation statement.
Your Total Superannuation Balance generally considers the value of your superannuation interests across your super arrangements. The ATO has also confirmed that changes to the way super interests are valued and reported are important to the new system.
Does Division 296 Apply to Retirement-Phase Super?
Yes. One common misconception is that Division 296 only affects people who are still working and building their super.
That is not the case.
Superannuation interests in retirement phase can also be included when determining your Total Superannuation Balance. This means retirees with substantial superannuation savings need to consider Division 296 as part of their retirement planning.
For people who have moved from accumulation into pension phase, it is particularly important to understand how their pension interests are valued and how earnings are attributed under the new rules.
How is Division 296 Tax Calculated?
The calculation is more complicated than simply taking 15% of investment earnings. Broadly, the calculation involves determining your relevant superannuation earnings and then working out what proportion relates to the part of your super balance above the applicable threshold.
For example, imagine a person has:
- A Total Superannuation Balance of $4 million
- Relevant superannuation earnings of $200,000
- A $3 million large super balance threshold
The proportion of the balance above $3 million is 25%.
The Division 296 calculation therefore looks at the relevant earnings attributable to that excess portion rather than simply applying 15% to the entire $200,000.
Using this simplified example, 25% of the $200,000 relevant earnings, or $50,000, would be attributable to the portion above $3 million.
Applying the 15% Division 296 rate would produce an illustrative Division 296 liability of $7,500.
The actual statutory calculation can differ because contributions, withdrawals and other adjustments may affect the earnings and proportion calculations.
This is why calculating Division 296 tax requires more than looking at your investment return for the year. The legislation establishes specific concepts including taxable superannuation earnings, total superannuation earnings, relevant superannuation earnings and Division 296 fund earnings.
What Happens if Your Super Investments Fall?
Division 296 allows certain negative earnings to be carried forward and offset against future earnings. This recognises that super investments can rise and fall over time.
This is particularly relevant for SMSFs and members with large investment portfolios, where market fluctuations can significantly affect annual earnings.
What About Capital Gains?
Under the final Division 296 legislation, the regime generally focuses on realised earnings rather than taxing unrealised increases in asset values. This is an important change from the earlier proposal, which would have brought unrealised gains into the calculation.
For SMSFs holding assets such as shares or property, an increase in market value by itself does not generally create Division 296 earnings until the gain is realised, subject to the specific statutory calculation rules.
Important 30 June 2026 Transition Rules for SMSFs
For certain small superannuation funds, including eligible SMSFs, transitional CGT rules may be relevant for assets held at 30 June 2026.
An eligible fund may be able to make an irrevocable choice that uses the asset’s market value at 30 June 2026 in determining the Division 296 cost base for future realised gains.
This can be particularly important for SMSFs holding property, shares or other assets with substantial unrealised gains accumulated before Division 296 commenced.
Trustees should obtain advice before making any election and ensure appropriate valuation evidence is retained.
Division 296 and SMSFs
SMSF trustees may face additional reporting and record-keeping requirements under Division 296.
The ATO will use information reported through the SMSF annual return to help calculate individual liabilities.
In some cases, calculating a member’s share of fund earnings may require an actuary’s certificate, making accurate valuations and documentation particularly important.
How Will the ATO Collect Division 296 Tax?
Division 296 is a personal tax liability. The tax is not simply deducted from your super fund’s normal tax bill.
Instead, the ATO will calculate the liability and issue an assessment to the individual.
The ATO has explained that the Division 296 assessment is separate from tax paid by the superannuation fund and that an individual can generally either pay the liability personally or elect to have money released from superannuation to help pay it.
Once an assessment is issued, the liability is generally due 84 days after the date of the notice of assessment.
If you want to use your super to help pay the liability, the release election generally needs to be made within 60 days of the assessment.
That makes it important not to ignore a Division 296 assessment if you receive one.
Can You Pay Division 296 Tax From Your Super?
Yes. Eligible individuals can generally choose to pay the tax personally or release money from their super to cover the liability.
However, withdrawing from super reduces the amount available for retirement, so consider the decision as part of your overall retirement strategy.
What About Defined Benefit Pensions?
Division 296 can apply to defined benefit interests, but special valuation and payment rules apply.
In some cases, payment may be deferred until the benefit becomes payable. Professional advice can help determine how the rules apply to your situation.
Are There Exemptions?
Some limited exemptions apply, including for certain child recipients of super income streams and structured settlement contributions.
Special transitional rules may also apply in the event of death during 2026–27.
What Does Division 296 Mean for Your Retirement Strategy?
For someone approaching $3 million in super, Division 296 adds another consideration to retirement planning.
That doesn’t necessarily mean you should rush to withdraw money or change your investment strategy.
Instead, the new tax should be considered alongside:
- Contribution strategies
- Investment returns
- Retirement timing
- Pension strategies
- SMSF structures
- Asset allocation
- Estate planning
- Superannuation tax concessions
- Cash-flow requirements
- Personal tax circumstances
It is also important not to make decisions based solely on the $3 million threshold.
Superannuation remains a highly concessional retirement structure, and the tax treatment of investment earnings inside super can still be attractive compared with investing outside super.
The right strategy depends on your individual circumstances.
What Should You Do If Your Super Is Approaching $3 Million?
If your super is approaching $3 million, review your position now rather than waiting for an ATO assessment.
Check your Total Superannuation Balance, keep SMSF valuations and records up to date, and consider how future contributions, investment returns and pension withdrawals could affect your balance.
It’s also a good time to review your estate planning.
Importantly, Division 296 does not require you to reduce your super below $3 million. It changes the tax treatment of certain earnings associated with large super balances.
The ATO’s Role in Division 296
The ATO will calculate Division 296 liabilities using information reported by super funds and SMSFs.
Funds and trustees therefore have additional reporting responsibilities under the new rules.
Planning Ahead for Division 296
If you have, or expect to have, more than $3 million in super, consider how Division 296 fits into your investment, retirement, tax and estate planning strategy.
The $3 million and $10 million thresholds are also subject to indexation over time.
If you have a large super balance, speak with your accountant or financial adviser about how Division 296 may affect your retirement strategy.
At Camden Professionals, together with Investax Group, we work with SMSF trustees and members to understand how superannuation tax changes such as Division 296 may affect their tax, retirement and estate planning.
Where financial advice is required, we can work alongside your licensed financial adviser.
Division 296 is complex, and individual outcomes depend on your circumstances.
This article should not be relied upon as personal financial or tax advice.
Division 296 Tax FAQs
Is Division 296 a Tax on My Entire Super Balance?
No. Division 296 is an additional tax on relevant superannuation earnings attributable to the portion of your balance above the applicable threshold.
When Does Division 296 Start?
Division 296 applies from 1 July 2026, with the first affected financial year being 2026–27.
First assessments are expected in the 2027–28 income year.
Is the Division 296 Threshold $3 Million?
Yes. The large superannuation balance threshold is $3 million for 2026–27.
It is subject to indexation in later years.
What Happens Above $10 Million?
A further 10% Division 296 tax applies to the relevant earnings attributable to the portion above the $10 million very large superannuation balance threshold.
This means the additional Division 296 component can reach 25% for the relevant portion above $10 million.
Does Division 296 Apply to SMSFs?
Yes. Division 296 can apply to SMSF members as well as members of APRA-regulated funds and people with defined benefit interests.
Can I Pay Division 296 Tax From My Super?
Generally, yes.
Eligible individuals can elect to have money released from super to help pay the liability, subject to the relevant time limits.
Does Division 296 Mean I Should Keep My Super Below $3 Million?
Not necessarily.
Reaching $3 million does not mean you have to withdraw your super.
The appropriate strategy depends on your investment, retirement, tax and estate planning circumstances.
Sources
- Australian Taxation Office (ATO) – Division 296 administrative and reporting information, including assessment, payment and release arrangements.
- Australian Government – Income Tax Assessment (1997 Act) Amendment (Building a Stronger and Fairer Super System and Other Measures) Regulations 2026, providing supporting valuation and calculation rules.
- Australian Parliament – Parliamentary Bills Digest explaining the purpose and tiered structure of Division 296.
- Australian Government Actuary / Commonwealth Superannuation Corporation – current explanation of Division 296 and its application from 1 July 2026.
How Can We Help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Western Australian Property Market Outlook September 2026
The Western Australian property market is entering a new phase in September 2026. After several years of strong price growth, tight housing supply and intense buyer competition, Perth’s property market is showing signs of normalisation.
For buyers, investors and business owners, rising property listings are creating more choice, while elevated interest rates continue to influence borrowing capacity, repayments and investment decisions.
However, a more balanced market does not mean every property is becoming less attractive. Location, property type, rental demand and affordability remain important factors shaping opportunities across Perth and regional WA.
The key for September 2026 is to look beyond headline property prices. Whether you’re purchasing a home, investing in residential property or acquiring commercial premises, understanding cash flow, financing costs and long-term market fundamentals is essential.
Perth Property Market Outlook September 2026
More Listings, More Buyer Choice
Perth’s residential market is shifting towards more balanced conditions as properties take longer to sell and buyers become more selective.
- According to REIWA, active listings reached 7,335 properties at the end of August 2026, up 7.8% from July and 146.1% compared with August 2025. REIWA attributes the shift to easing demand and longer selling times.
- Despite the increase in stock, Perth house prices remain elevated. REIWA’s September data puts the median house sale price at $955,125 for the 12 months to August 2026, while the median unit price reached $690,000.
The market is not moving uniformly. With more stock available, buyers may have greater scope to negotiate, while sellers may need to be more realistic on pricing and presentation. For prospective purchasers, additional listings offer more opportunity to compare properties and make considered decisions rather than compete in a highly pressured market.
WA Property Market Outlook: What Buyers and Investors Should Know
Residential Property
Higher listings are giving buyers more choice, while affordability and borrowing capacity remain key considerations.
Units and Apartments
Units may appeal to buyers seeking a lower entry price than detached houses, although location, strata costs and rental demand need careful assessment.
Commercial Property
Quality, location and tenant demand remain important, particularly as businesses weigh the cost of leasing against purchasing their own premises.
Perth House Prices and Residential Demand
Perth’s residential property market remains supported by established demand, but the rapid growth conditions seen in previous years appear to be easing.
REIWA’s August results indicate that annual median prices remain high, even as quarterly conditions have softened. The distinction matters: annual median figures can lag more recent changes in buyer demand and selling prices.
For buyers, September may provide greater scope to negotiate, conduct due diligence and compare properties. For sellers, the increase in available stock means realistic pricing and strong presentation may become increasingly important.
Rather than relying on broad Perth-wide growth expectations, buyers should assess individual suburbs, comparable sales, property condition and their ability to manage repayments.
WA Rental Market and Property Investment
Perth’s rental market remains relatively tight, although conditions vary by property type and location.
REIWA’s September market snapshot recorded 1,974 properties available for rent in the week ending 20 September, compared with 2,122 in the corresponding week a year earlier. Median weekly rents for the 12 months to August were $750 for houses and $700 for units.
WA Rental Market and Property Investment
For property investors, rental demand can help support income, but a strong advertised rent does not automatically translate into a strong investment return.
Before Purchasing, Consider:
- Expected rental income and realistic vacancy periods.
- Mortgage repayments under different interest-rate scenarios.
- Council rates, insurance, maintenance and property management fees.
- Land tax and other applicable holding costs.
- Potential capital expenditure and future resale demand.
Investors should assess net cash flow, not just gross rental yield. A property that appears attractive based on rent alone may place pressure on household finances if interest costs or maintenance expenses increase.
Perth Office and Commercial Property Outlook
Perth’s office market is becoming increasingly differentiated, with quality, location and tenant demand continuing to influence leasing and purchasing decisions.
High construction and labour costs continue to influence development feasibility, which may encourage some owners to consider refurbishing existing buildings rather than undertaking new developments.
For small business owners, strata office properties in areas such as West Perth, Leederville, Subiaco and East Perth may provide alternatives to premium CBD accommodation.
Purchasing business premises can provide greater control and potentially build a long-term asset. However, it also ties up capital that may otherwise be used to fund operations, employ staff or grow the business.
Before buying, business owners should compare the full cost of ownership with leasing, including finance, strata levies, maintenance and the impact on working capital. The right decision depends on business cash flow, growth plans and the proposed ownership structure.
Interest Rates and Borrowing Capacity
Interest rates remain a major influence on the September 2026 property outlook.
At its 11 August meeting, the Reserve Bank of Australia (RBA) held the cash rate at 4.35%, following three increases earlier in 2026. The RBA noted that inflation remained too high and that previous rate increases were still working through the economy.
The RBA’s next monetary policy meeting is scheduled for 28–29 September, meaning interest-rate settings remain an important consideration for buyers making decisions this month. Rather than trying to predict the next rate move, buyers should consider whether a purchase remains affordable under a range of repayment scenarios.
For prospective buyers, higher interest rates can reduce borrowing capacity and increase mortgage repayments. Investors may also face tighter cash flow, particularly where rental income does not fully cover property expenses.
Before committing to a purchase, consider whether you could comfortably manage repayments if rates increased further or your circumstances changed.
A property purchase should remain financially sustainable under less favourable conditions, not just today’s assumptions.
Regional WA Property Market Outlook
While Perth attracts significant attention, regional Western Australian property markets can offer different opportunities and risks.
Regional centres influenced by resources, infrastructure, agriculture, tourism and local employment may experience market conditions that differ considerably from metropolitan Perth.
For buyers and investors, local economic conditions, population trends, employment stability and rental demand are important considerations.
A regional property with an attractive purchase price may still carry risks if its tenant pool is limited or the local economy is heavily dependent on one industry.
Rather than assuming regional WA will move in line with Perth, buyers and investors should assess each location on its own fundamentals, including employment drivers, population trends, housing supply and rental demand.
What the September 2026 Outlook Means for Buyers
The changing WA property market reinforces the importance of making decisions based on your financial position rather than trying to time the market perfectly.
With more properties available and borrowing costs still elevated, buyers may have more time and choice than during the highly competitive conditions of recent years. This makes property selection, due diligence and affordability particularly important.
Before Purchasing, Consider:
- Your borrowing capacity: Understand your repayments, deposit requirements and available equity.
- Your cash flow: Model the impact of interest rates, vacancies and unexpected expenses.
- Your investment timeframe: Consider whether the property aligns with your long-term financial goals.
- Your tax position: Understand how ownership structure, rental income, deductible expenses and capital gains tax may affect your overall return.
- Your exit strategy: Consider resale demand, ongoing marketability and whether the property will suit future buyers.
For existing property owners, September is also an opportunity to review portfolio performance, assess debt levels and ensure your investment strategy remains appropriate as market conditions evolve.
The Bottom Line: A More Balanced WA Property Market Calls for Careful Decisions
Western Australia’s property market appears to be entering a more measured phase in September 2026. Rising listings are giving buyers more choice, while elevated interest rates and changing demand are placing greater emphasis on affordability, cash flow and careful property selection.
Perth’s residential market continues to show elevated median prices, while rental conditions remain relatively tight. Commercial property opportunities are increasingly shaped by location, quality and the financial needs of businesses.
For buyers, investors and business owners, the focus should be on more than short-term price movements. Market conditions can change quickly, and broad Perth or WA figures will not necessarily reflect an individual suburb or property. Understanding the numbers, managing risk and considering the longer-term fundamentals can help support more informed property decisions.
Frequently Asked Questions
Is September 2026 a good time to buy property in Perth?
Increasing listings may provide buyers with more choice and negotiating opportunities. However, affordability, property quality and individual financial circumstances remain important.
Are Perth property prices still rising?
REIWA’s annual median data continues to show elevated prices, while more recent conditions point to a market that is becoming more balanced. Annual median figures can lag changes occurring within individual suburbs and property segments, so they should not be viewed as a prediction of future price movements.
Is WA property a good investment in 2026?
Investment suitability depends on the individual property, purchase price, rental income, holding costs, borrowing capacity and long-term objectives. Current market strength does not guarantee future capital growth or positive cash flow.
What should WA property investors consider before buying?
Investors should assess rental demand, vacancy risk, interest costs, maintenance, tax implications and the property’s potential resale market.
How can an accountant help with property investment?
An accountant can help assess cash flow, ownership structures, tax implications and investment costs to support informed property decisions.
Sources:
- REIWA – Perth Market Insights
- REIWA – Perth Listings Exceed 7,000
- REIWA – Perth Market Conditions
- Reserve Bank of Australia – Monetary Policy
- WA Treasury – Housing Market
- Small Business Development Corporation WA
How Can We Help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
Camden Professionals, together with Investax Group, can also help property investors and business owners understand the cash-flow, ownership and tax considerations that sit behind a property decision, where advice is required.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
7 Ways to Build a More Valuable Business
Building a successful business is about more than growing revenue and profits.
If you’re planning to sell, bring in a partner or prepare for retirement, one question matters:
What is your business worth, and how can you increase its value?
Profit alone won’t attract premium buyers. They want a business with sustainable earnings, loyal customers and the systems, people and potential to thrive without you.
This is particularly important for small and medium-sized businesses, where the owner may still be responsible for winning new clients, managing staff, overseeing operations and making most of the important decisions.
The good news is that business value can be strengthened over time. By improving financial performance, reducing risk and building a business that can operate independently of you, you can create a more valuable and resilient business.
Whether you plan to sell in three years, pass the business to your children or simply build a stronger financial future, here are seven practical ways to increase your small business valuation.
Focus on Sustainable Revenue, Not Just Sales Growth
Growing revenue is important, but buyers also want to understand how reliable that revenue will be after the business changes hands.
A business generating $2 million in annual revenue from long-term customer contracts may be viewed differently from one generating the same amount through unpredictable, one-off projects. Predictable revenue gives potential buyers greater confidence in future cash flow and earnings. It can also make the business less vulnerable to seasonal fluctuations or changes in market conditions.
For small business owners, improving revenue quality could involve:
- Developing recurring service agreements or subscription-based offerings.
- Building long-term customer relationships.
- Introducing maintenance, support or repeat-purchase services.
- Improving customer retention and renewal rates.
- Reducing reliance on constantly winning new customers to maintain revenue.
You do not need to completely change your business model. Even introducing a recurring revenue component can help improve income predictability.
The goal is to build revenue that a buyer can reasonably expect to continue after the sale.
Improve Profitability and Protect Your Margins
Revenue growth means little if your costs are growing just as quickly. Buyers look beyond reported profit to assess maintainable earnings and the business’s ability to generate sustainable profits. Rising wages, supplier costs, rent and financing expenses can erode margins despite strong sales.
Regularly reviewing financial performance helps identify cost pressures, protect margins and improve profitability.
Practical Steps Include:
- Reviewing gross profit margins across products and services.
- Identifying unprofitable customers or service lines.
- Monitoring overheads and unnecessary expenditure.
- Reviewing pricing to reflect current operating costs.
- Separating genuine one-off expenses from ongoing business costs.
If the owner receives expenses or remuneration that may be adjusted when a buyer takes over, these should be clearly documented and supported by evidence. Buyers and their advisers will independently assess any earnings adjustments.
Strong profitability is not simply about achieving one exceptional year. It is about demonstrating consistent, sustainable earnings that can continue under new ownership.
Reduce Customer Concentration Risk
One of the biggest risks for a small business is relying too heavily on a handful of customers. If one customer accounts for 40% of your revenue, losing that relationship could have a significant impact on profitability and cash flow.
Buyers will want to understand what would happen if a major customer reduced spending, changed suppliers or decided not to renew a contract. A diversified customer base can reduce this exposure and make the business less vulnerable to unexpected changes.
To Strengthen Your Customer Portfolio:
- Identify your largest customers as a percentage of total revenue.
- Develop a strategy to attract new customers across different segments.
- Build relationships with multiple decision-makers within key accounts.
- Formalise customer agreements where appropriate.
- Monitor customer retention, churn and repeat business.
Customer diversification does not mean abandoning valuable long-term relationships. It means ensuring that the business is not overly dependent on any single customer to remain profitable.
Build a Business That Does Not Depend on You
For many owner-managed businesses, the owner is the business. If you’re the driving force behind sales, customer relationships and daily operations, your involvement may be limiting your business’s value. Buyers want confidence that the business can thrive without you, not lose momentum when you leave.
This is often referred to as key-person risk, and it can affect both buyer confidence and the terms of a transaction.
To Reduce Owner Dependency, Consider:
- Developing a capable management team.
- Delegating important operational responsibilities.
- Documenting key processes and decision-making procedures.
- Establishing customer relationships that extend beyond the owner.
- Training employees to manage critical business functions.
Building a capable team can also improve your work-life balance today, giving you more time to focus on strategy, growth and long-term planning.
Strengthen Your Systems and Financial Reporting
Reliable systems and accurate financial information help buyers understand how a business operates and whether its reported performance can be trusted.
If your financial reporting is inconsistent, your processes are undocumented or important information exists only in the owner’s head, a buyer may see additional risk and complexity. Good business systems are not just for larger organisations. Even a small business can benefit from structured reporting, documented procedures and appropriate technology.
Focus on Establishing:
- Accurate, up-to-date accounting records.
- Monthly profit and loss statements and cash flow reports.
- Reliable budgeting and financial forecasting.
- Documented operational procedures.
- Appropriate customer relationship management and business software.
- Clear employment, supplier and customer agreements.
Good governance is also important. Keep business and personal expenses separate, maintain appropriate company records and ensure tax and regulatory obligations are up to date.
For Australian small businesses, working with a qualified accountant and using resources from organisations such as the Australian Small Business and Family Enterprise Ombudsman (ASBFEO) can help owners identify practical ways to improve business management and prepare for future growth.
The more transparent and organised your business is, the easier it becomes for a potential buyer to conduct due diligence and understand what they are acquiring.
Protect Your Intellectual Property and Competitive Advantage
Buyers want to know what makes your business different and why customers will continue choosing it over competitors. If your products, services or operating model can be easily replicated, it may be harder to demonstrate a sustainable competitive advantage.
Intellectual Property (IP) Can Take Many Forms, Including:
- Registered trade marks, patents or designs.
- Proprietary software, technology or processes.
- Exclusive distribution or licensing arrangements.
- Established brands and customer databases.
- Specialised industry knowledge and expertise.
Demonstrate How the Business Can Scale
A business that can grow without increasing costs at the same rate may offer buyers greater opportunities for future earnings.
For example, a business with established systems, available team capacity and repeatable processes may be able to increase sales without needing to significantly expand its overheads. By contrast, if every increase in revenue requires the owner to hire more staff, purchase additional equipment or personally work longer hours, growth may be more difficult to sustain.
Small Business Owners Can Improve Scalability By:
- Standardising service delivery and operational processes.
- Using technology to automate repetitive tasks.
- Improving staff productivity and resource allocation.
- Identifying new markets or complementary services.
- Monitoring capacity, margins and the cost of acquiring customers.
Buyers do not necessarily expect a business to have unlimited growth potential. They want evidence that realistic growth opportunities exist and that the business has the infrastructure to pursue them.
A documented growth strategy, supported by credible financial forecasts and operational capacity, can help demonstrate that potential.
Why You Should Start Preparing for a Business Sale Early
One of the most common mistakes business owners make is waiting until they are ready to sell before thinking about business valuation. By the time you’re ready to sell, it may be too late to fix the issues that undermine value.
Customer concentration, declining margins, weak reporting and owner dependency take time to resolve.
Start planning your exit three to five years ahead. Early preparation gives you time to strengthen profitability, reduce risk and keep your options open, whether you sell, bring in a partner or continue growing.
The result? A more valuable, resilient business that works for you, not just because of you.
A Simple Business Value-Building Checklist
Use the following checklist to identify areas that may need attention before a future sale or succession.
Business Readiness Checklist
- Review revenue quality and recurring income
- Assess profit margins and sustainable earnings
- Measure customer concentration and retention
- Reduce reliance on the business owner
- Improve financial reporting and operational systems
- Review intellectual property and key contracts
- Document a realistic growth and scalability plan
Use this as a starting point, rather than a formal valuation. A professional business valuation will consider the specific circumstances, financial performance, risks and market conditions relevant to your business.
How Your Accountant Can Help Increase Business Value
Your accountant can help prepare your business for growth, succession or sale by assessing maintainable earnings, improving financial reporting, identifying risks and strengthening cash flow.
They can also coordinate with valuation and legal specialists to support exit planning. Business value goes beyond revenue and profit, reflecting your financial performance, industry, assets, risks and market conditions. Getting professional advice early can help you understand your starting position and prioritise improvements that align with your longer-term objectives.
Frequently Asked Questions
What increases the value of a small business?
Key factors include sustainable earnings, predictable revenue, customer diversification, strong management, reliable systems, competitive advantages and the ability to grow without excessive additional costs.
How is a small business valuation calculated?
Depending on the business, valuation methods may include an earnings multiple, discounted cash flow analysis or an asset-based approach. The appropriate method depends on the business’s circumstances and the purpose of the valuation.
How long should I prepare before selling my business?
Ideally, begin preparing three to five years before a planned sale. This allows time to improve profitability, reduce business risks and establish systems that support a successful ownership transition.
Does higher revenue always mean a higher business valuation?
No. Buyers also consider profitability, revenue quality, risk, cash flow and the sustainability of earnings. A business with lower revenue but stronger margins and more predictable income may attract a different valuation.
Can my accountant help me prepare my business for sale?
Yes. An accountant can help improve financial reporting, assess sustainable earnings, identify financial risks and support exit planning. A formal valuation or transaction may also require specialist advisers.
The Bottom Line: Build a Business That’s Worth More
Increasing your small business valuation is not something that should begin when you decide to sell. It is an ongoing process of improving profitability, reducing risk, strengthening systems and creating a business that can thrive without relying entirely on you.
The earlier you start, the more opportunities you have to strengthen business performance, improve future options and prepare for a successful transition.
Whether your goal is to sell, plan for succession or build a more profitable business for the long term, understanding what drives business value can help you make better decisions today.
Ready to Build a More Valuable Business?
At Investax and Camden Professionals, our accounting and business advisory team can help small business owners review financial performance, identify opportunities to improve profitability and develop a strategy for sustainable growth and future succession.
Whether you are planning an exit in the next few years or simply want to build a stronger business, contact Investax to discuss how proactive tax planning, financial reporting and business advisory support can help you prepare for what’s next.
How Can We Help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
General Advice Warning
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
2027 Property Valuations and CGT Changes: What Investors Need to Know
Australia’s CGT reforms, taking effect from 1 July 2027, could significantly change how property investors calculate tax when selling. The existing 50% CGT discount will largely be replaced by inflation-indexed cost bases and a minimum 30% tax rate on real capital gains for affected assets, while pre-reform gains retain existing treatment.
For investors, the key challenge is distinguishing capital growth before and after the transition date. A professional valuation on 1 July 2027 could help establish this split and support future CGT calculations.
While not compulsory for everyone, a reliable valuation could prove valuable, particularly for long-term investors planning to sell years down the track.
What Are the 2027 Capital Gains Tax Changes?
The Australian Government’s 2026–27 Budget reforms introduce a new approach to taxing capital gains from 1 July 2027. The legislation has been enacted, with transitional arrangements applying to assets held before the change.
Under the new rules, the existing 50% CGT discount will generally be replaced by cost base indexation for inflation, alongside a minimum 30% tax rate on real capital gains.
The key changes are summarised below.
CGT Feature
Current Rules
Generally, 50% for eligible individuals and trusts.
From 1 July 2027
Replaced by inflation-based indexation for affected assets.
Pre-reform Capital Growth
Existing CGT treatment.
Post-reform Capital Growth
50% discount may apply.
Indexation and minimum 30% tax rate apply under the new rules.
Qualifying New Residential Builds
Existing CGT discount.
Investors can choose the old or new CGT arrangements.
For property investors, the important point is that the reform does not simply apply a new tax calculation to the entire profit made when a property is eventually sold. The transitional arrangements distinguish between gains accrued before and after 1 July 2027. That distinction is where a property valuation could become valuable.
Why Is 1 July 2027 a Critical Date for Property Investors?
Under the transitional rules, an eligible asset held across 1 July 2027 is effectively divided into two periods for CGT purposes.
Capital Growth Before 1 July 2027
Capital growth before 1 July 2027 generally retains the existing CGT treatment.
Capital Growth From 1 July 2027
Capital growth from 1 July 2027 is subject to the new indexation and minimum-tax arrangements.
The legislation provides for a deemed disposal and reacquisition at the transition date, with the tax consequences deferred until the asset is actually sold. Taxpayers can generally establish the pre- and post-reform split using the property’s market value at 1 July 2027 or a prescribed apportionment method.
Example: How a 2027 Valuation Could Affect Your CGT
Consider an Australian investor who purchased an established investment property for $500,000 and later sells it for $1 million. For simplicity, assume the property is worth $800,000 on 1 July 2027, with no other cost base adjustments.
Illustrative Property Capital Growth
Original purchase price
$500,000
Pre-1 July 2027 growth: $300,000
Illustrative transition-date value
$800,000
Post-transition growth: $200,000
Eventual sale price
$1,000,000
The $300,000 pre-reform gain and $200,000 post-reform gain would be treated under different CGT arrangements, subject to the applicable rules and adjustments.
This is a simplified illustration, not a CGT calculation. Indexation, eligible costs, capital improvements, ownership structure and other factors can affect the actual taxable gain.
The example highlights why the transition-date value matters. If the property’s value is incorrectly estimated, the allocation of capital growth between the two tax regimes could also be affected.
Is a Property Valuation Mandatory Under the New CGT Rules?
No. A formal market valuation is not the only method available under the transitional arrangements. The legislation provides for a prescribed apportionment method as an alternative to using market value at the transition date. The precise application of that method and relevant administrative guidance should be checked as the ATO provides
Although a valuation isn’t mandatory, it may still be worthwhile. Property growth varies by location and individual features, so a prescribed apportionment method may not accurately reflect a property’s actual value at the transition date.
An independent valuation can provide credible evidence to help allocate capital gains between the old and new CGT rules. While it won’t automatically reduce tax, it may help support your CGT position when you eventually sell.
Why a Retrospective Property Valuation May Be More Difficult
Investors do not necessarily need to commission a valuation on 1 July 2027 itself. A retrospective valuation may be possible, provided it establishes the property’s market value at the relevant date and meets applicable requirements.
However, reconstructing a property’s value many years later can be challenging.
The Australian Property Institute (API) has highlighted the importance of reliable valuation evidence for the CGT transition. Its guidance indicates that valuation evidence prepared close to the transition date is likely to be more reliable and defensible than an assessment reconstructed years later.
Consider What Could Happen Between 2027 and the Eventual Sale:
- The property may undergo substantial renovations or redevelopment.
- The surrounding suburb may experience significant infrastructure or zoning changes.
- Comparable properties may be renovated, redeveloped or sold under very different market conditions.
- Photographs, maintenance records and other evidence of the property’s 2027 condition may no longer be available.
For a property sold in 2040, establishing its precise condition and market value in 2027 could require considerable investigation. The practical takeaway: If you intend to retain an investment property for the long term, preserving reliable evidence of its 2027 value could make your eventual CGT reporting easier.
What Type of Property Valuation Should Investors Obtain?
Not all property estimates are equal. An automated estimate from a property website or an informal real estate agent’s appraisal may provide a useful indication of market value. However, it is not necessarily a substitute for a professional valuation prepared for a tax-related purpose.
The API distinguishes professional valuation reports from desktop estimates and automated valuation models. Its guidance emphasises the importance of appropriate valuation evidence and supporting comparable sales information.
Valuation Type
Automated Property Estimate
Useful as an initial guide, but may not reflect property-specific features.
Real Estate Agent Appraisal
May help assess likely selling prices, but is not the same as an independent valuation.
Professional Retrospective Valuation
Can assess market value at a specified past date, subject to available evidence.
Professional Valuation Close to the Transition Date
Can provide contemporaneous evidence of market value and property condition.
For a potentially significant future CGT liability, speak with your accountant about the appropriate valuation method and engage a suitably qualified independent property valuer.
Retain the full report, engagement details and supporting evidence with your permanent CGT records. Your accountant can help determine how the valuation should be used under the applicable tax rules.
Does the 2027 CGT Reform Affect Your Family Home?
Most homeowners need not worry. Properties qualifying for the full main residence exemption generally remain CGT-exempt under the 2027 reforms. However, properties used partly for rental or income-producing purposes may require closer review.
You may need to seek tax advice if you:
- Convert your former home into a rental property.
- Rent out part of your home while continuing to live there.
- Own a holiday home that does not qualify for the main residence exemption.
- Have used a property partly for business purposes.
The ATO’s guidance on the property and capital gains tax rules can help homeowners understand when CGT may apply. Where a property has mixed or changing use, a valuation may be relevant to establishing the tax position.
What About New Builds and Other Property Investments?
Qualifying new builds may retain the 50% CGT discount or opt for the new rules, while eligible affordable housing has specific concessions. Separate negative gearing reforms affect certain established properties acquired after 12 May 2026. Investors should review eligibility, ownership structure and tax implications with their adviser.
What Should Property Investors Do Before 1 July 2027?
There is no need to order a transition-date valuation today. A valuation prepared now would not establish the property’s market value on 1 July 2027. Instead, investors can use the months ahead to organise their records and plan with their accountant.
- Locate the original purchase contract and settlement statement.
- Keep records of stamp duty, legal fees and eligible acquisition costs.
- Collect invoices for renovations, extensions and capital improvements.
- Retain photographs and records showing the property’s condition.
- Review ownership structure and any main residence exemption history.
- Discuss transition-date valuation requirements with your accountant.
- Arrange suitable valuation evidence close to the transition date, if appropriate.
- Store the valuation and supporting records with your permanent CGT documents.
For investors with multiple properties, early planning may be particularly useful. A portfolio of five or 10 properties can involve different acquisition dates, ownership structures, property improvements and valuation requirements.
The objective is not to obtain unnecessary reports. It is to identify which properties may benefit from valuation evidence and ensure the relevant records are available when needed.
Final Note – Why CGT Planning Matters for Long-Term Property Investors
Capital gains tax is often a long-term consideration. Investors may hold property for decades, meaning decisions made today can affect the tax outcome when the asset is eventually sold. Early tax planning and record-keeping are essential for long-term investors. A valuation confirming your property’s 1 July 2027 value could help your accountant calculate future CGT with confidence. Plan ahead, rather than waiting until you sell.
Frequently Asked Questions
Do all property investors need a valuation on 1 July 2027?
No. The transitional rules provide for market value or a prescribed apportionment method. Whether a professional valuation is worthwhile depends on the property and your circumstances.
Can I get a retrospective property valuation after 2027?
A retrospective valuation may be possible, but reliable contemporaneous evidence can be more difficult to obtain as time passes. Consider discussing the timing and valuation requirements with your accountant.
Will the 2027 CGT changes apply to my existing investment property?
The reforms distinguish between gains accrued before and after 1 July 2027. Existing investments are not automatically exempt from the new CGT arrangements on future capital growth.
Does the CGT reform affect my principal place of residence?
A property that qualifies for the full main residence exemption generally remains exempt. Properties with mixed or changing use may require closer review.
Should I get a property valuation now?
A valuation obtained now will not establish the property’s value at the 1 July 2027 transition date. Focus on organising your records and planning for appropriate valuation evidence closer to the relevant date.
Speak to Investax About Your Property CGT Strategy
The 2027 CGT reforms are a timely reminder to review your property tax strategy. Investax can help you assess the changes, review ownership structures, organise records and plan for future valuations. Early advice can help you prepare for a future property sale.
How Can We Help?
If you have any questions or would like further information, please feel free to give our office on 08 9221 5522 or via email – info@camdenprofessionals.com.au or arrange a time for a meeting so we can discuss your requirements in more detail.
Australian References and Sources
- Australian Treasury – Budget 2026–27 Tax System Changes. CGT reforms, transitional arrangements and new-build treatment.
- Parliament of Australia – Treasury Laws Amendment (Tax Reform No. 1) Bill 2026. Legislative summary and CGT transition provisions.
- Australian Property Institute – The CGT Changes and Property Valuations: What You Need to Know. Valuation evidence and transition-date considerations.
- Australian Taxation Office – Property and Capital Gains Tax. Property CGT, main residence exemption and relevant tax obligations.
Disclaimer: This article provides general information only and is not tax, legal or financial advice. The application of CGT rules depends on individual circumstances, ownership structure and eligibility. Investors should seek professional advice before making property or tax decisions.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Has Your Business Outgrown Its Structure?
When you first start a business, choosing a structure may seem like a straightforward decision.You might operate as a sole trader, partnership, company or trust based on your circumstances at the time.
But businesses change.As revenue increases, employees are hired, new owners become involved or the business expands into new markets, the structure that worked when the business started may no longer reflect how it operates today.
A business structure can affect taxation, registrations, reporting requirements, administration, ownership, control and personal liability.There is no single structure that is right for every Australian business, but changing circumstances can make a business structure review worthwhile.
What is a business structure?
In Australia, common business structures include sole trader, partnership, company and trust.Each structure has different legal, tax and administrative characteristics.
A sole trader structure is generally simple to establish and operate, while a company is a separate legal entity with its own obligations.Partnerships involve two or more people carrying on a business together, while trusts can provide a different way of holding and distributing business or investment assets.
The structure chosen can influence how the business is controlled, how income is treated and the extent to which owners may be personally exposed to business liabilities.Business.gov.au recommends considering factors such as the costs involved, tax implications, personal liability, control and the amount of paperwork and reporting required when choosing a structure.As a business develops, those considerations can change.
Signs your business structure may need a review
Business growth does not automatically mean you need to restructure.However, certain developments may be a good reason to revisit the original decision.
Your revenue has increased
A business that started with modest revenue may look very different several years later.Increasing turnover can change the tax and cash-flow considerations surrounding the business.It may also mean that the owner needs to consider whether the current structure remains appropriate for the scale and complexity of the operation.
You are employing staff
Taking on employees can introduce additional responsibilities, including PAYG withholding, superannuation and other employer obligations.While employing staff does not necessarily require a new business structure, it can be a useful trigger for a broader business health check.
New owners are becoming involved
Bringing a spouse, family member, business partner or investor into the business can significantly change ownership and control arrangements.The existing structure may not provide the most suitable framework for the new ownership arrangements, particularly where different people will have different financial interests or responsibilities.
The business is expanding
Expansion into new products, services, locations or markets can introduce new commercial risks and administrative requirements.For example, a business that began as a small consulting operation may eventually employ staff, enter significant contracts, lease premises and take on larger financial commitments.As the risks and responsibilities change, it can be sensible to review whether the existing structure continues to provide an appropriate foundation.
Your long-term goals have changed
Your original business plan may have been based on remaining a small owner-operated business.Several years later, you may be considering selling the business, bringing in investors, expanding interstate or passing the business to the next generation.Those future plans can be relevant when reviewing the current structure.

A structure review is about more than tax
Tax is an important consideration when reviewing a business structure, but it should not be the only one.The ATO recognises that different structures have different tax and reporting obligations.The broader commercial consequences should also be considered.
A review may consider:
- Ownership and control – who owns the business and who makes important decisions?
- Personal liability – what exposure do owners have to business debts and risks?
- Tax obligations – how is business income taxed and what reporting is required?
- Administration – how much record keeping, reporting and compliance is involved?
- Succession planning – what happens if an owner retires, dies or wants to exit?
- Growth – can the structure accommodate future expansion or additional owners?
- Exit planning – could the current structure affect a future sale or transfer?
A structure that appears attractive because of a particular tax outcome may not necessarily be suitable when these broader considerations are considered.
When should you review your business structure?
There is no universal timetable for reviewing a business structure.Instead, consider undertaking a review when there has been a significant change in the business or when future plans have changed. Useful questions include:
- Has the business grown significantly since it began?
- Has turnover or profitability changed substantially?
- Have you started employing staff?
- Have new owners or investors become involved?
- Has the business taken on significant debt or commercial risk?
- Are you expanding into new markets or locations?
- Have your personal or business goals changed?
- Are you considering selling or transferring the business?
- Has the current structure become increasingly difficult to administer?
If the answer to several of these questions is yes, it may be time to discuss whether the existing structure remains appropriate.

What happens if you decide to restructure?
Changing a business structure is not simply an administrative exercise.Depending on the circumstances, restructuring can have tax, legal, accounting and administrative consequences.
The ATO provides specific guidance on changing business structures and notes that there can be tax implications when moving from one structure to another.
These can include capital gains tax, income tax and other consequences depending on what is being transferred and how the restructure is undertaken.
There may also be new registrations, record-keeping requirements, contracts, licences or reporting obligations to consider.For this reason, business owners should obtain appropriate professional advice before implementing a restructure rather than changing the structure first and considering the consequences afterwards.
The business is expanding
Expansion into new products, services, locations or markets can introduce new commercial risks and administrative requirements.For example, a business that began as a small consulting operation may eventually employ staff, enter significant contracts, lease premises and take on larger financial commitments.As the risks and responsibilities change, it can be sensible to review whether the existing structure continues to provide an appropriate foundation.
Your long-term goals have changed
Your original business plan may have been based on remaining a small owner-operated business.Several years later, you may be considering selling the business, bringing in investors, expanding interstate or passing the business to the next generation.Those future plans can be relevant when reviewing the current structure.

A structure review is about more than tax
Tax is an important consideration when reviewing a business structure, but it should not be the only one.The ATO recognises that different structures have different tax and reporting obligations.The broader commercial consequences should also be considered.
A review may consider:
- Ownership and control – who owns the business and who makes important decisions?
- Personal liability – what exposure do owners have to business debts and risks?
- Tax obligations – how is business income taxed and what reporting is required?
- Administration – how much record keeping, reporting and compliance is involved?
- Succession planning – what happens if an owner retires, dies or wants to exit?
- Growth – can the structure accommodate future expansion or additional owners?
- Exit planning – could the current structure affect a future sale or transfer?
A structure that appears attractive because of a particular tax outcome may not necessarily be suitable when these broader considerations are considered.
A business health check can identify opportunities
A business structure review can be part of a broader business health check.Business owners regularly review their pricing, staffing, cash flow, marketing and operational systems. The legal and tax structure supporting those activities deserves similar attention. A review can help identify whether the current structure continues to align with the business’s:
- current operations;
- ownership arrangements;
- risk profile;
- tax obligations;
- administration requirements; and
- long-term objectives.
It may also confirm that the existing structure remains appropriate and that no change is necessary.That can be just as valuable as identifying a potential restructure.
Recent tax reforms make structure reviews more important
The 2026–27 Federal Budget introduced significant proposed changes affecting business and investment structures, including a 30% minimum tax on discretionary trusts from 1 July 2028.Since the Budget, the Government has released a consultation paper and, more recently, exposure draft legislation providing further detail on how the new trust rules are intended to operate.
The latest proposals also include expanded restructuring options and rollover relief for eligible businesses and taxpayers considering whether their existing trust structure remains appropriate.These changes do not mean that every business operating through a discretionary trust needs to restructure.However, with significant tax reforms approaching, business owners should consider whether the structure they established years ago remains suitable for their current business, ownership arrangements and longer-term objectives.
Don’t wait until the business changes again
The structure selected when a business first started trading may have been entirely appropriate at the time.But businesses evolve. A growing business may have different ownership arrangements, greater revenue, additional employees, increased commercial risk and more ambitious plans than it did several years earlier. That does not automatically mean the business needs a new structure.
It does mean that the original decision should not necessarily be treated as permanent. Regularly reviewing the structure can help ensure it continues to reflect the way the business operates and the objectives of its owners. Before making any changes, obtain advice on the potential tax, legal and administrative consequences of restructuring.
Frequently Asked Questions
How often should I review my business structure?
There is no set period that applies to every business.A review can be particularly useful after significant changes in ownership, revenue, staffing, risk or business objectives.
Does business growth mean I need to change my structure?
Not necessarily.Growth can be a reason to review your structure, but whether a change is appropriate depends on your specific circumstances.
Is choosing a business structure mainly about tax?
No. Tax is one consideration. Ownership, control, personal liability, administration, succession and future growth should also be considered.
Can I change my business structure later?
Yes, but changing structures can have tax, legal and administrative consequences. Professional advice should be obtained before implementing a restructure.
What are the main business structures in Australia?
The common structures are sole trader, partnership, company and trust. Each has different legal, tax and administrative characteristics.
Where can I find Australian government information about business structures?
Business.gov.au provides information about choosing and changing business structures, while the ATO provides tax information and guidance relevant to different structures.
Do the recent Federal Budget and proposed trust tax changes mean I should review my business structure?
Potentially. The 2026–27 Federal Budget proposed significant changes affecting discretionary trusts, and the subsequent consultation paper and exposure draft legislation have provided further detail on how these changes may operate from 1 July 2028.These reforms do not mean every business needs to restructure, but businesses operating through trusts may benefit from reviewing whether their existing structure remains appropriate before the new rules commence.
How Can We Help?
If you have any questions or would like further information, please contact Camden Professionals on:
Phone: 08 9221 5522
Email: info@camdenprofessionals.com.au
You can also arrange a meeting so we can discuss your requirements in more detail.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Setting Up an SMSF: What You Need to Know Before You Start
Thinking about setting up a Self-Managed Super Fund (SMSF)? An SMSF can give you greater control over how your retirement savings are invested, but it also comes with significant responsibilities.
Unlike an APRA-regulated super fund, where a professional trustee is responsible for managing the fund, an SMSF puts those responsibilities largely in the hands of its trustees. That means choosing an SMSF is not simply about investment choice. You need to consider the costs, administration, investment strategy, compliance requirements and whether managing your own super is appropriate for your circumstances.
What Is an SMSF?
A Self-Managed Super Fund is a private superannuation fund established for a small number of members. The members are generally also trustees, or directors of a corporate trustee.
- The key difference is control. SMSF trustees are responsible for making investment decisions and ensuring the fund complies with superannuation and tax laws.
- The ATO requires an SMSF to have an investment strategy before it starts investing. The strategy must reflect the purpose and circumstances of the fund and its members and must be reviewed regularly.
- This makes an SMSF quite different from simply selecting an investment option within an existing super fund.
Is an SMSF Right for You?
Before establishing an SMSF, consider why you want one. An SMSF may appeal to people who want greater control over their investments, have more complex investment needs or want to manage a broader range of assets within the superannuation rules. However, control also means responsibility.
As an SMSF trustee, you are responsible for ensuring investments comply with the law, maintaining records, preparing reports, arranging an annual audit and ensuring the fund’s investment strategy remains appropriate. The ATO makes it clear that trustees remain responsible for the fund’s investments even when professional advisers are used.
1. Look at the Investment Options
One of the main reasons people consider an SMSF is investment flexibility. Depending on the fund’s investment strategy and the superannuation rules, an SMSF can invest in assets such as shares, managed investments, term deposits and property. But greater choice does not mean every investment is permitted.
The ATO states that SMSF investments must be permitted under the fund’s trust deed and superannuation law, have clear legal ownership, be made on a commercial arm’s-length basis and satisfy the sole purpose test. There are also restrictions around transactions involving members and related parties. For example, the ATO states that, subject to limited exceptions, an SMSF generally cannot acquire assets from members or related parties, provide financial assistance to members or related parties, or use fund assets to provide a present-day benefit. Before investing, make sure you understand both the opportunity and the restrictions.
2. Have a Clear SMSF Investment Strategy
The ATO says an SMSF investment strategy should consider matters including:
- Diversification
- Investment risk and likely returns
- Liquidity
- The fund’s ability to meet expenses and retirement benefits
- The circumstances and needs of members
- Members’ retirement timeframes and risk appetite
Your investment strategy should be in writing and reviewed regularly. This is important because an SMSF should not be established simply to buy a particular asset. The investment strategy needs to explain how the fund’s investments relate to the retirement objectives of its members. This is important because where an SMSF is established with a particular investment in mind, trustees still need to consider whether that investment is appropriate having regard to the fund’s overall investment strategy and the circumstances of its members.
3. Compare SMSF Costs
Running an SMSF involves ongoing costs.
These can include:
- Establishment costs
- Accounting and tax return preparation
- Annual audit fees
- ATO supervisory levy
- Administration costs
- Investment advice
- Legal costs
- Brokerage and investment expenses
- Insurance where appropriate
The important question is not simply how much an SMSF costs each year. It is whether the benefits, flexibility and control justify those costs for your circumstances. For some people, the costs and administration of an SMSF may outweigh the benefits. For others, particularly those with more complex investment requirements, the additional control may be an important consideration.
4. Consider Your Investment Performance
Investment performance should be considered carefully, but it should not be the only reason for choosing an SMSF. Past performance does not guarantee future returns. If you are comparing an existing APRA-regulated super product with the potential benefits of an SMSF, make sure you are comparing like with like. Consider:
- Investment returns
- Investment risk
- Fees and expenses
- Diversification
- Liquidity
- Asset allocation
- Your investment timeframe
APRA conducts an annual performance test for certain APRA-regulated superannuation products. The test is designed to improve transparency and hold trustees accountable for underperformance. APRA also publishes broader product performance information covering investment returns, fees and performance-test outcomes. These resources can provide useful information when comparing an existing super fund with other APRA-regulated options.
5. Don’t Forget Insurance
Insurance is another issue to consider when deciding whether to establish an SMSF. Some super funds provide members with insurance options such as:
- Life insurance
- Total and permanent disability cover
- Income protection
If you move from an existing fund to an SMSF, you should check what insurance arrangements you currently have and whether transferring or replacing that cover could affect you. Insurance should be considered separately from the investment decision because losing existing cover can have important consequences.
6. Understand the SMSF Trustee Responsibilities
Perhaps the biggest difference between an SMSF and an APRA-regulated super fund is the level of responsibility placed on the trustee. SMSF trustees need to ensure the fund:
- Complies with superannuation legislation
- Maintains appropriate records
- Has and follows an investment strategy
- Meets tax and reporting obligations
- Arranges an annual independent audit
- Makes investments on an arm’s-length basis
- Complies with contribution and payment rules
The ATO also warns SMSF trustees about investment schemes that promise unusually high returns.Trustees need to understand what they are investing in and ensure every investment decision is consistent with the fund’s purpose and legal requirements.
7. Think About Property and Other Complex Investments
The Australian Taxation Office (ATO) has strict rules governing when a self-managed super fund (SMSF) can invest in property. Generally, the property must be acquired for the sole purpose of providing retirement benefits to fund members, rather than for personal use or benefit. An SMSF generally cannot acquire residential property from a member or related party, and residential property owned by the SMSF cannot be used by members or their relatives.
Different rules can apply to eligible business real property, including commercial property used in a business. Any property investment must also be consistent with the fund’s investment strategy and comply with the relevant superannuation rules. Recent changes have also affected the ability of SMSFs to borrow to purchase residential property.
From 10 August 2026, SMSFs are generally no longer able to enter into new limited recourse borrowing arrangements (LRBAs) to acquire residential property. Existing arrangements entered into before the change may be protected under transitional rules.
Importantly, the restriction does not extend to eligible commercial property, so SMSFs may still be able to use an LRBA to acquire business or commercial property where the relevant superannuation and borrowing rules are satisfied.
For anyone considering establishing an SMSF specifically to purchase property, it is important to understand these rules before setting up the fund or entering into a purchase contract. Professional advice should be obtained to ensure the proposed investment and funding arrangement comply with the relevant superannuation and tax requirements.
8. SMSF or APRA-Regulated Super Fund?
The decision does not have to be based simply on investment choice. An APRA-regulated super fund generally provides professional trustee oversight, investment options and administration without requiring the member to manage the fund’s compliance themselves. An SMSF provides greater direct control but places considerably more responsibility on the trustees. The right structure depends on your objectives, investment preferences, circumstances, costs and willingness to take on the responsibilities of being an SMSF trustee.
Final Thoughts
Choosing an SMSF is a significant financial decision. The attraction is usually greater control and flexibility, but those benefits come with additional administration, costs and legal responsibilities. Before establishing an SMSF, consider your investment objectives, the types of assets you want to invest in, the likely costs, insurance arrangements and the time and expertise required to manage the fund. The ATO provides detailed guidance on establishing and running an SMSF, including investment strategies and investment restrictions.
APRA also publishes performance information that can help consumers understand how APRA-regulated superannuation products are performing.An SMSF should be established because it is appropriate for your overall retirement strategy, rather than simply because it offers more investment choices.
FAQs About Choosing an SMSF
What is an SMSF?
A Self-Managed Super Fund is a private superannuation fund where the members generally act as trustees and are responsible for managing the fund and complying with superannuation laws.
How many members can an SMSF have?
An SMSF can have up to six members, subject to the relevant superannuation rules.
Do SMSFs need an investment strategy?
Yes.The ATO requires an SMSF to have an investment strategy and to review it regularly.
Can an SMSF invest in property?
Yes, an SMSF can invest in certain types of property, but strict superannuation rules apply.
The investment must be consistent with the fund’s investment strategy and satisfy the relevant legal requirements.
Are SMSFs regulated by APRA?
No. SMSFs are regulated by the Australian Taxation Office (ATO). APRA regulates most large superannuation entities, including APRA-regulated super funds.
What should I consider before setting up an SMSF?
Consider investment choice, costs, administration, insurance, compliance responsibilities, your investment strategy and whether you are comfortable taking responsibility for managing your own superannuation.
How Can We Help?
If you have any questions or would like further information, please contact Camden Professionals on:
Phone: 08 9221 5522
Email: info@camdenprofessionals.com.au
You can also arrange a meeting so we can discuss your requirements in more detail.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.
Downsizer Contributions: How Selling Your Home Could Boost Your Superannuation
For many Australians approaching retirement, selling the family home can be about more than finding a smaller or more manageable property. It can also create an opportunity to strengthen retirement savings through a downsizer contribution to superannuation.
The Australian Government’s downsizer rules allow eligible homeowners to contribute some of the proceeds from selling their home directly into superannuation. For eligible individuals, the contribution can be up to $300,000, while an eligible couple may potentially contribute up to $600,000 between them, subject to each person’s eligibility and the applicable rules.
- The eligible age for a downsizer contribution is currently 55 years or older.
- Since 1 January 2023, you must be at least 55 years old when making the contribution.
- There is no maximum age limit for a downsizer contribution, provided you meet the other eligibility requirements.
However, downsizing does not automatically mean there will be hundreds of thousands of dollars available to put into super. Property prices, selling costs and the cost of the replacement home all need to be considered.Understanding the rules before selling is important because there are specific eligibility requirements, contribution deadlines and conditions that need to be satisfied.
Why Downsizing Doesn’t Always Mean Having More Cash
The term “downsizing” can sometimes create the impression that selling a large family home will automatically release a substantial amount of money.
That is not necessarily the case.
Many Australians sell their existing home and purchase another property in a desirable location. They may choose a newer apartment, a low-maintenance townhouse or a property closer to family, the coast, healthcare services or a major city.
In some areas, the replacement property can cost almost as much as the home being sold. There are also selling costs, legal fees, moving expenses, stamp duty where applicable and other transaction costs to consider. This means the amount available for a downsizer contribution will depend on the individual’s circumstances and the actual proceeds available from the sale. For those who do have surplus funds, however, the downsizer rules can provide an opportunity to move a significant amount into the superannuation system.
Downsizer Contribution Eligibility: What Are the Rules?
The ATO sets out a few conditions that must be met before a contribution can qualify as a downsizer contribution.
Generally, you must:
- Be 55 years of age or older when making the contribution.
- Have owned the property for at least 10 years before the sale, generally measured from the date of acquisition to the date of disposal.
- Have owned the property as an individual or jointly with your spouse.
- You or your spouse must have held an ownership interest in the property, and the relevant 10-year ownership requirement must be satisfied.
- Make the contribution from the proceeds of selling an eligible Australian residential property.
- Satisfy the relevant main residence requirements.
- Make the contribution within the required timeframe.
- Have not previously made a downsizer contribution from the sale of another dwelling.
The ATO states that the contract for sale must generally have been entered into on or after 1 July 2018. The contribution must generally be made within 90 days of the change of ownership, unless the Commissioner grants an extension. It is therefore important not to treat the downsizer contribution as an informal arrangement that can be organised whenever convenient after settlement.
The 90-Day Downsizer Contribution Deadline
One of the most important practical considerations is timing. Eligible downsizer contributions generally need to be made within 90 days from the change of ownership of the property. The ATO can grant an extension in certain circumstances.
This means homeowners planning to use the downsizer rules should consider their superannuation arrangements before the property settles. Waiting until after settlement to investigate the rules could create unnecessary pressure, particularly if there are questions about eligibility or the amount that can be contributed. The timing should also be considered alongside the settlement of the replacement property, because selling the existing home and buying another property can involve significant cash-flow requirements.
How Much Can You Contribute?
An eligible individual can generally make a downsizer contribution of up to $300,000 from the proceeds of selling an eligible home. The ATO states that the maximum amount an individual can contribute from the sale of one home is the lesser of:
- $300,000, or
- the sale proceeds remaining after taking into account other downsizer contributions made by the individual or their spouse.
Importantly, multiple downsizer contributions can potentially be made from the sale of the same home, provided the total does not exceed the applicable maximum. For example, an eligible homeowner might contribute $150,000 shortly after settlement and another $150,000 later, provided the relevant conditions are met. A couple may also be able to contribute up to $300,000 each if both individuals meet the requirements.
Does a Downsizer Contribution Count Towards Your Normal Super Contribution Caps?
A qualifying downsizer contribution does not count towards your concessional or non-concessional contribution caps. This can make the downsizer rules particularly useful for people who may otherwise have limited opportunities to contribute a significant amount into super. However, once contributed, the money becomes part of your superannuation balance and the normal superannuation rules will apply. The contribution should therefore be considered as part of your broader retirement and superannuation strategy rather than in isolation.
Can Downsizer Contributions Help Build Retirement Wealth?
For homeowners who have substantial equity in their property, downsizer contributions can provide another way to structure retirement savings. Money held in the family home can provide security and reduce housing costs, but it does not generally produce investment income in the same way as assets held within superannuation.
Moving some surplus capital into super may allow the money to form part of a broader retirement investment strategy. However, contributing money to super also means the funds become subject to the superannuation rules.
The decision should therefore be considered as part of an overall retirement plan rather than simply as a tax strategy. The appropriate approach will depend on factors such as:
- Age
- Existing superannuation balances
- Pension arrangements
- Investment objectives
- Cash-flow requirements
- Estate planning
What Does This Have to Do with SMSFs?
Downsizer contributions can also be relevant to people who have a Self-Managed Super Fund (SMSF). An SMSF is a superannuation fund that members manage themselves. SMSFs are regulated by the Australian Taxation Office, rather than APRA. APRA’s own licensing guidance confirms that SMSFs are not RSEs and are instead regulated by the ATO.
This distinction is important. An SMSF trustee remains responsible for ensuring that contributions are correctly accepted and recorded and that the fund complies with superannuation legislation. The supplied material also highlights that SMSF trustees remain responsible for the fund’s investment strategy and compliance even where professional investment managers or other advisers are engaged.
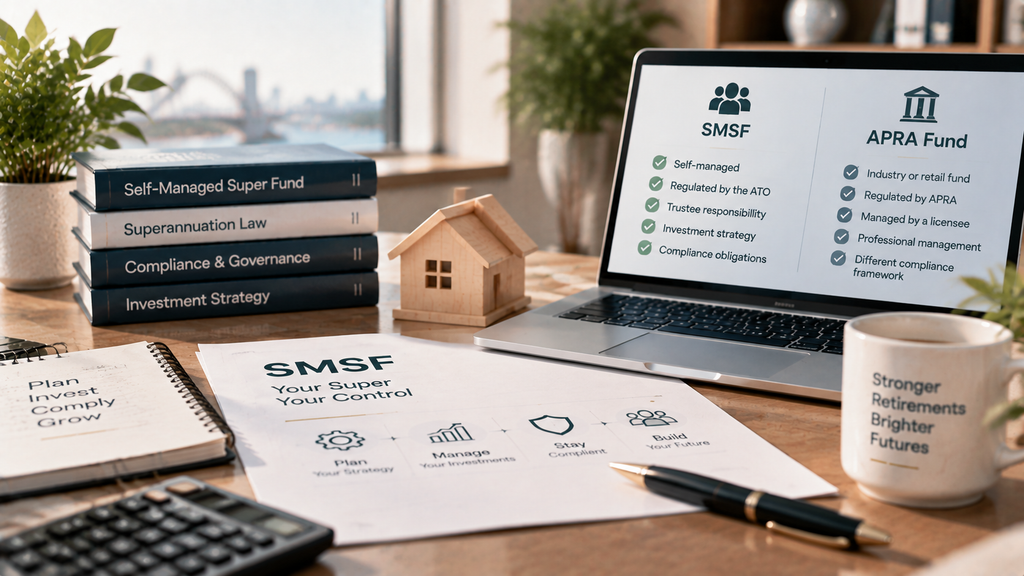
SMSFs vs APRA-Regulated Super Funds
Most Australians have their superannuation with an APRA-regulated fund, such as an industry or retail super fund. APRA oversees registrable superannuation entities and their licensed trustees. APRA’s prudential framework includes requirements covering areas such as:
- Governance
- Investment governance
- Risk management
- Insurance
- Member outcomes
For example, APRA’s SPS 530 Investment Governance requires RSE licensees to maintain an investment governance framework, establish investment objectives and strategies, conduct due diligence and undertake stress testing. APRA’s SPS 510 Governance also establishes minimum governance requirements for RSE licensees and places ultimate responsibility for sound and prudent management with the board. These APRA requirements apply to APRA-regulated superannuation entities and should not be confused with the regulatory framework governing SMSFs.
Most industry and retail super funds are regulated by APRA, while SMSFs are regulated by the ATO. The key practical difference is that SMSF trustees take direct responsibility for the fund’s compliance, investment strategy and administration. For SMSF members, the ATO is the key regulator.
What Are the Risks of an SMSF?
Having greater control over superannuation can also mean greater responsibility. SMSF trustees are responsible for making sure the fund’s investment strategy is appropriate, keeping records, meeting reporting obligations and complying with the superannuation laws. SMSFs do not have the same protections available to members of APRA-regulated funds.
There are also ongoing costs, including:
- Accounting
- Administration
- Auditing
- Regulatory levies
- Investment advice
- Potentially legal and insurance expenses
This means an SMSF should not be established simply because a downsizer contribution is available. The decision to use an SMSF should be considered separately from the decision about whether a downsizer contribution is appropriate.
Can You Use a Downsizer Contribution More Than Once?
Generally, no. The downsizer rules contain a once-only requirement. The ATO states that an individual must not have previously made a downsizer contribution from the sale of any dwelling. This can include multiple partial disposals of an ownership interest in the same dwelling.
This makes it particularly important to understand the rules before making the contribution. A decision to make a downsizer contribution can have long-term consequences because the opportunity generally cannot simply be repeated when another property is sold in the future.
What About the Capital Gains Tax Rules?
The property must generally satisfy the relevant main residence requirements for the downsizer rules. The ATO’s eligibility guidance refers to both an ownership test and a main residence test. This is an important area where professional advice can be useful, particularly where a property has been:
- Used partly as an investment property
- Rented out for periods
- Inherited
- Jointly owned
- Subject to other ownership arrangements
Not every residential property transaction will automatically qualify.
Downsizer Contributions and Capital Gains Tax (CGT)
Selling a property may also create Capital Gains Tax considerations.The tax outcome will depend on the individual’s circumstances, including:
- How the property was used
- Whether it was used to produce income
- Ownership history
- The period the property was held
- Whether any exemptions or concessions apply
The downsizer contribution rules and Capital Gains Tax rules are separate considerations.Meeting the downsizer contribution requirements does not automatically mean there are no CGT implications. Understanding both areas before selling can help avoid unexpected tax outcomes.
Is Downsizing the Right Strategy for You?
Downsizing can be an effective retirement planning strategy for some Australians, but it is not suitable for everyone.The decision involves more than just the opportunity to contribute money into superannuation.Factors to consider may include:
- Future housing needs
- Lifestyle preferences
- Access to funds
- Retirement income requirements
- Superannuation position
- Tax implications
- Estate planning objectives
For some people, remaining in their current home may continue to be the preferred option. For others, selling the family home and contributing surplus funds into superannuation may better align with their retirement goals.
What Should You Consider Before Making a Downsizer Contribution?
Before selling your home, consider:
Your Eligibility
Make sure all downsizer contribution requirements are satisfied before proceeding.
Your Financial Position
Review:
- The expected sale proceeds
- Replacement property costs
- Selling expenses
- Available cash reserves
Your Superannuation Strategy
Consider how the contribution fits with:
- Your existing super balance
- Retirement income plans
- Investment strategy
Your Estate Planning
A significant contribution into superannuation may affect how your assets are structured and passed on in the future.
How Professional Advice Can Help
Downsizer contributions involve several rules and requirements that need careful consideration. Professional advice can help you understand:
- Whether you qualify
- How much you may be able to contribute
- How the contribution fits into your retirement strategy
- Potential tax considerations
- The impact on your broader financial position
Planning before selling your home can help ensure the decision supports your long-term retirement objectives.
Final Thoughts
Downsizer contributions provide eligible Australians with an opportunity to move some proceeds from the sale of their home into superannuation. For some homeowners, this can help strengthen retirement savings and provide greater flexibility. However, selling a home is a significant financial decision and should be considered carefully. The downsizer rules should be reviewed alongside:
- Retirement plans
- Superannuation strategy
- Tax considerations
- Investment objectives
- Estate planning arrangements
Understanding the requirements before selling can help ensure decisions are made with a clear understanding of the potential outcomes.
Frequently Asked Questions
What is a downsizer contribution?
A downsizer contribution allows eligible Australians to contribute some proceeds from selling their home into their superannuation fund.
How much can I contribute through downsizer rules?
Eligible individuals may be able to contribute up to $300,000 from the sale of an eligible home.
Can couples both make downsizer contributions?
Yes. If both individuals meet the eligibility requirements, each person may be able to contribute up to $300,000.
What age do I need to be to make a downsizer contribution?
You must generally be at least 55 years old when making the contribution and meet the other eligibility requirements.
Does a downsizer contribution count towards normal contribution caps?
No. A qualifying downsizer contribution does not count towards concessional or non-concessional contribution caps.
Can I make a downsizer contribution more than once?
Generally, no. The downsizer rules include a once-only requirement.
Can I make a downsizer contribution into an SMSF?
Yes, provided the SMSF accepts the contribution and all eligibility requirements are satisfied.
How Can We Help?
If you are considering selling your home and want to understand how downsizer contributions may apply to your retirement strategy, Camden Professionals can help review your options.
Our team can assist with:
- Retirement planning considerations
- Superannuation strategies
- Tax implications
- Wealth planning
- Financial structuring considerations
Contact Camden Professionals to discuss your circumstances.
General Information Disclaimer
The material on this page and on this website has been prepared for general information purposes only and not as specific advice to any person. Any advice contained on this page and on this website is General Advice and does not consider any person’s particular investment objectives, financial situation and particular needs.
Before making an investment decision based on this advice you should consider, with or without the assistance of a securities adviser, whether it is appropriate to your particular investment needs, objectives and financial circumstances. In addition, the examples provided on this page and on this website are for illustrative purposes only.
Although every effort has been made to verify the accuracy of the information contained on this page and on this website, Camden Professionals and/or Investax Group, its officers, representatives, employees, and agents disclaim all liability (except for any liability which by law cannot be excluded), for any error, inaccuracy in, or omission from the information contained in this website or any loss or damage suffered by any person directly or indirectly through relying on this information.